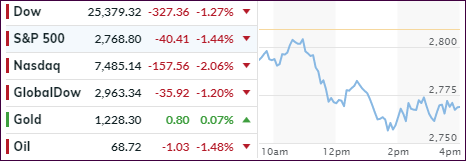
- Moving the markets
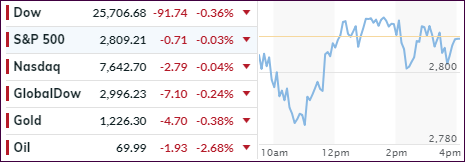
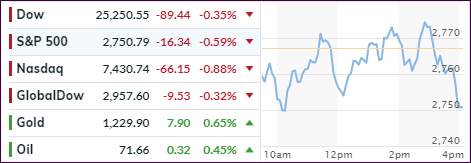
There was no rebound in sight anywhere, as the major indexes opened below their respective unchanged lines, headed south and bounced around the day’s lows without ever threatening the downward momentum.
The S&P 500 has now lost 9 out of the past 11 trading days and closed today right at its 200-day M/A. That leaves open the question as to whether this level will again serve as a springboard for further advances or will simply be a momentary resting place before the index dives into bear market territory.
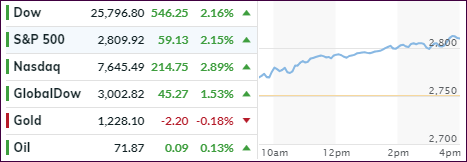
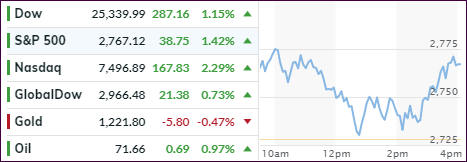
The Dow was off some 450 points at its low, as worries about interest rates and global growth took center stage and removed any bullish sentiment. For sure, this move ended Tuesday’s epic short squeeze, which was declared the biggest one since election day and which has now gone through a total reversal.
It all started with Chinese equites doing their best interpretation of a swan dive with the Yuan joining the party. For background, the Chinese markets have been nothing short of a bloodbath this year with their equivalent of the ‘Nasdaq’ having lost some -35% YTD. Taking a clue from China, Europe followed suit with their indexes not only sinking for the session but diving into the close.
As ZH, pointed out, bond yields spiked yesterday to catch up with stocks, then recoupled and fell today in sync with equities. YTD, 10-year yield has come off its highs, at least for the time being, while the US dollar continues to hover in its trading range, although at the high end.
What could spark a sudden rebound in equities?
While a surprisingly strong earnings season may rank at the top of the list, another reason could be the ending of the blackout period companies have put in place that limits trading from a few weeks before earnings are released until shortly thereafter. Whether these two possibilities are enough to overcome weak economic data and lack of global growth remains to be seen.
Our Trend Tracking Indexes (TTI) continue to support the bearish theme, as you can see in section 3.