S&P 500 Flirts With 2,900 Level

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

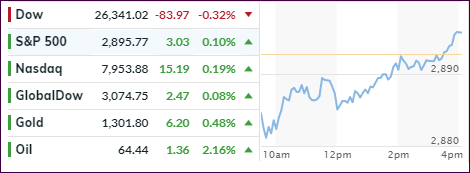
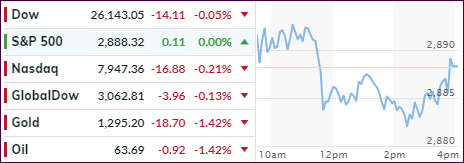
The S&P 500 came within a few points of touching its 2,900 level, but lack of follow through momentum pulled the major indexes off the highs and below the unchanged lines before a rebound limited the damage. The retreat occurred as uneasiness prevailed amongst traders in view of the upcoming earnings season, which kicks off unofficially on Friday.

Analysts have projected S&P 500 earnings to drop -4.2% YoY leaving the big boys on Wall Street a little wary before reviewing not only the latest results but also managements’ outlook for the next 12 months. Until those facts become known, we may see more of the directionless meandering of the indexes, as we witnessed today.

Another fly in the ointment could be the signs of lackluster growth throughout world economies, which may deflate the bullish craving despite the indexes hovering near all-time highs. I think, the markets need a solid driver to push through overhead resistance levels, and meager earnings may simply not be enough.

On the other hand, focused jawboning about the latest and greatest U.S.-China trade talks, along with the Fed uttering more dovish comments might be enough to take out the old highs.

Seems like economic adviser Kudlow took the lead by proclaiming that “I don’t see rates rising again in my lifetime,” which to me indicates that a recession is built in the cake and will have to be dealt with sooner or later. After all, rising interest rates are a sign of a strong economy and not a weak one, while low rates indicate the reverse.

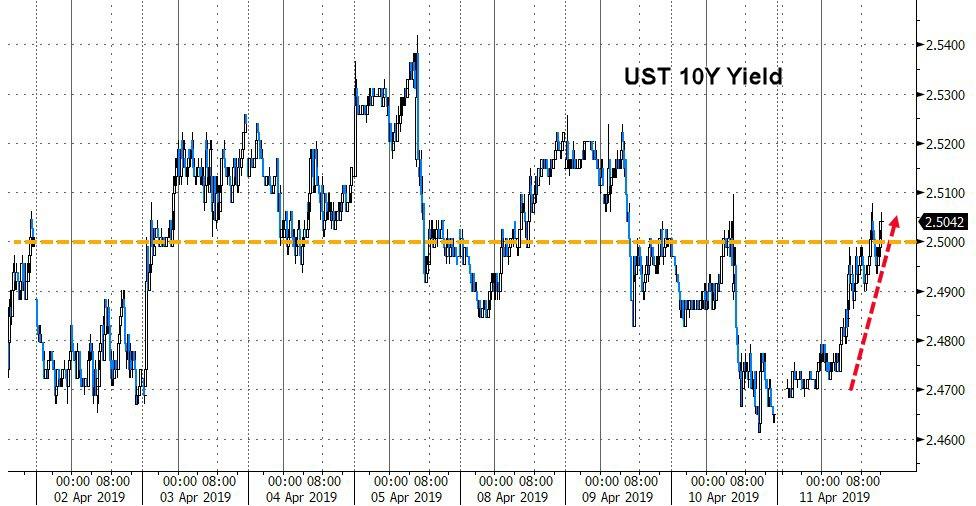
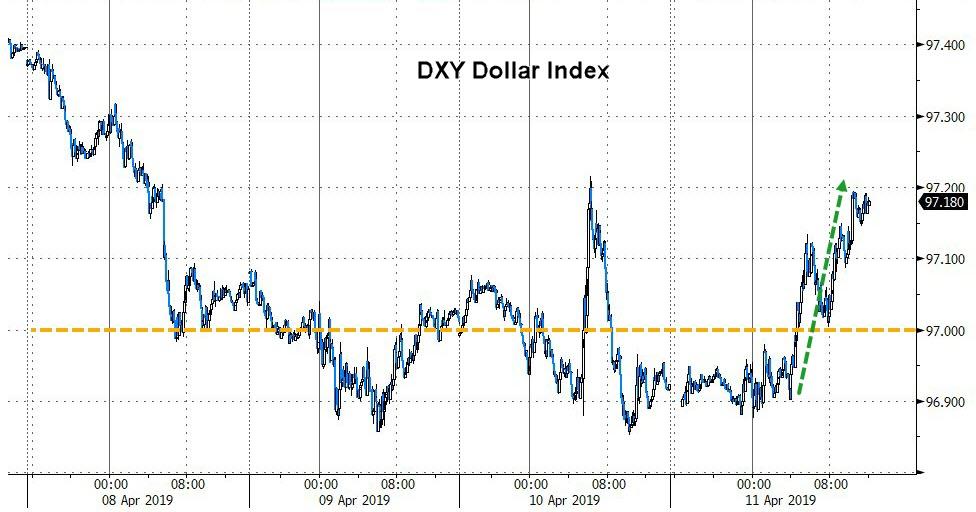
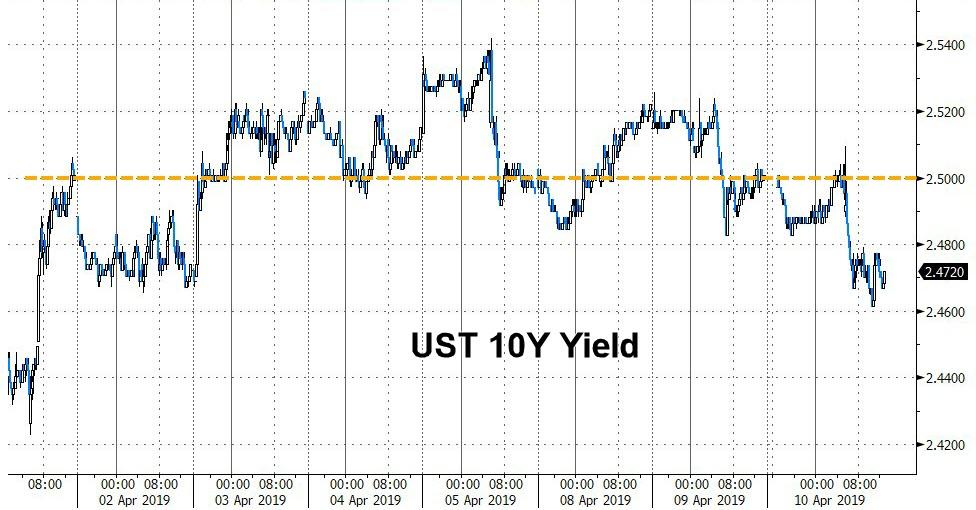
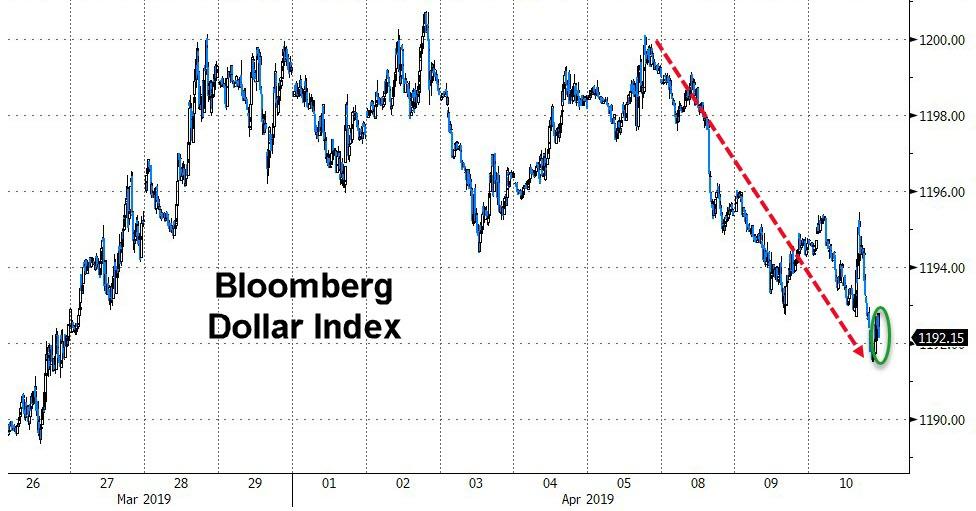
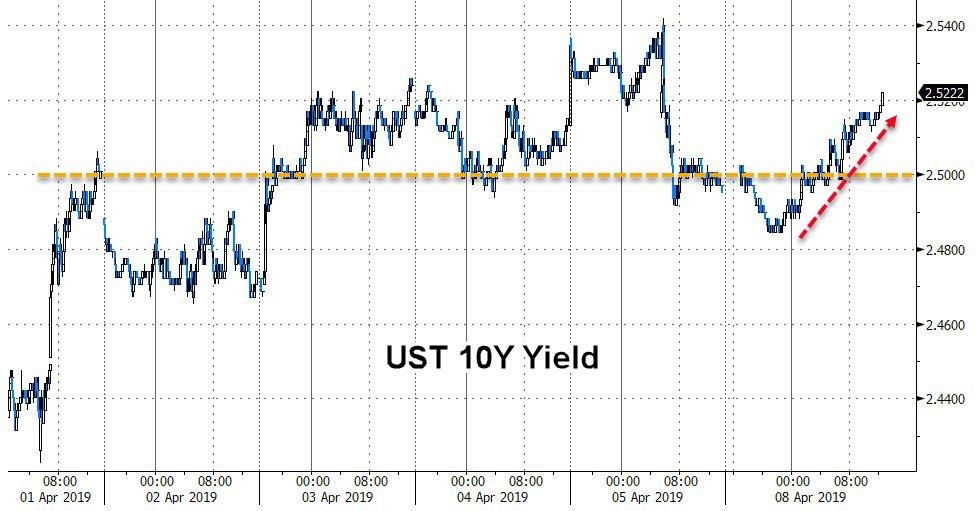
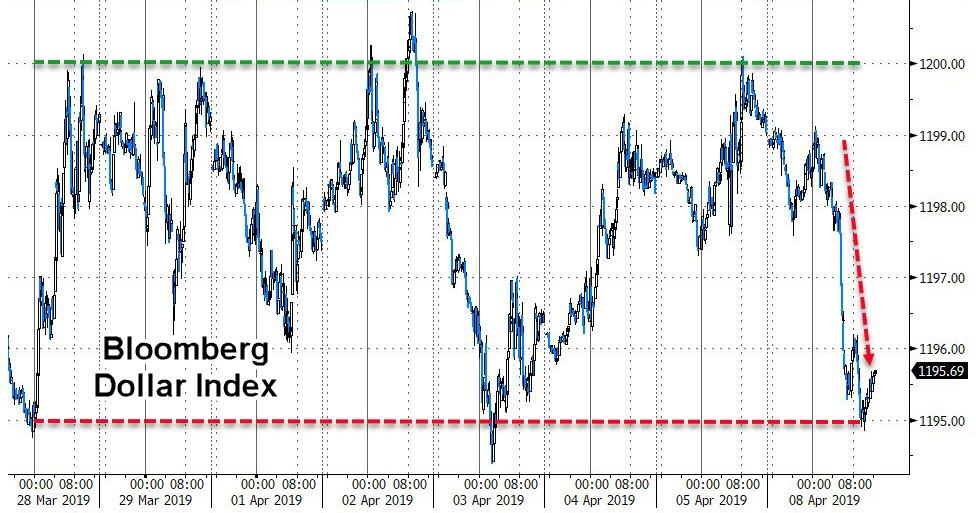
Speaking of reverse, today interest rates rose with the 10-year bond yield having now recaptured the 2.50% level, which helped the dollar index to break its 3-day losing streak.
Read More

Drifting Higher

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

Investors were all over the released March Fed minutes trying to gain some insight as to why the Fed decided to give up on normalizing their monetary policy. Recall that last month the Fed abandoned plans for further rate increases in 2019 due to uncertainty over the lack of growth not just in the U.S. but global economies as well.

Other worries listed were the U.K.’s struggle to leave the EU, ongoing trade tensions between the U.S. and China and allegedly unexpected tame inflation data. In the end, there appeared to be too many unknowns causing the committee to leave interest rates unchanged.

But today, we learned that consumer prices rose at the fastest pace in 14 months in March but, with the following line always used as the saving grace, gains were small when excluding volatile food and energy prices.

The European Central Bank (ECB) seemed to use the same playbook, as they announced no changes to monetary policy and confirmed its intention of leaving rates at current levels till the end of 2019.

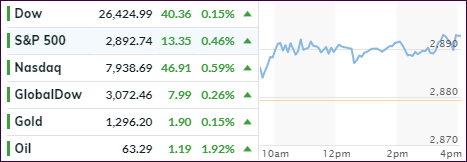
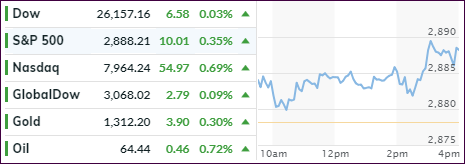
The markets took it all in stride with the major indexes remaining mostly above their unchanged lines with the S&P 500 and Nasdaq seeing more buying at the end of the session than the Dow, which barely slipped into the green.

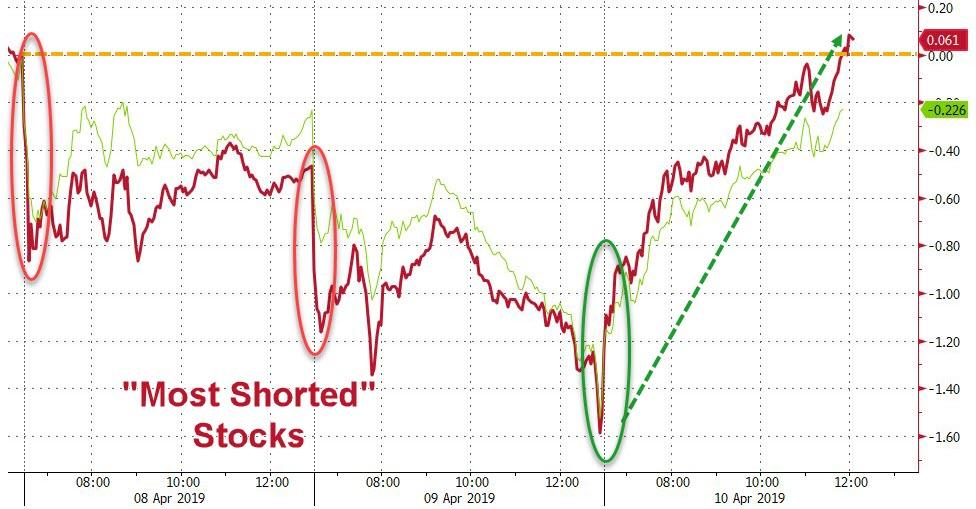
Helping the last hour push was a short squeeze, the biggest since February 27th, while interest rates fell with the 10-year yield now back below the 2.5% level causing the U.S. Dollar index to drop to its lows of the session.

Our Trend Tracking Indexes (TTIs) benefited from the last hour ramp keeping our “Buy” signals intact.

Read More

Digging A Hole And Staying In It

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

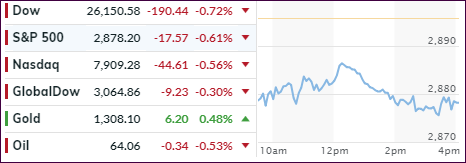
For a while, the markets looked like attempting to repeat yesterday’s feat, namely that an opening dump would be followed by a slow and steady recovery back above the unchanged line. However, mid-day the developing rebound hit a brick wall, reversed, and south we went taking out the early morning lows.

Causing this weakness was Trump’s threat to slap some $11 billion of tariffs on European Union (EU) goods, as retaliation against European subsidies for aircraft manufacturers. Considering that the trade battle with China is still unresolved, this second line of combat is seen as an additional “disrupter” of the already weakening global economies.

On the domestic economic front, we learned that job opening plunged by 538k, which was the biggest drop in 42 months. To me, that is not a surprising development given that most economic data points over the past few months have been anything but encouraging.

The stock market has been ramping higher with total disregard to underlying fundamentals, even though bond yields have been slipping and indicating that not all is well. In the meantime, the Fed has virtually guaranteed that there will be no rate hikes in 2019.

My guess is that they will likely lower rates by mid-year to stimulate activity, as the dreaded “R” word, as in recession, will likely be uttered by the Main Stream Media in the not too distant future.

Today’s pullback moved our Trend Tracking Indexes (TTIs) off their lofty levels, but they remain firmly entrenched on the bullish side of their respective trend lines (section 3).

Read More

Dropping And Popping

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

A sharp early morning drop sent the major indexes reeling before buyers stepped in and pulled the Nasdaq and S&P 500 back out of the basement and into a green close.  The laggard was the Dow, because of Boeing’s production cuts, which left the index in the red.

Not helping the markets were rising bond yields, which pushed the 10-year back above the 2.50% level, while the US Dollar, which usually rallies on higher rates, dumped to the low end of its recent trading range.

In the end, it was a non-eventful trading day that did not affect our Trend Tracking Indexes (TTIs) much. However, economist David Rosenberg tweeted a picture of the front cover of Barron’s magazine implying that, if you hold the view that the opposite usually happens of what major publications feature, we could be seeing the makings of a market top.

Read More

ETFs On The Cutline – Updated Through 04/05/2019

Ulli ETFs on the Cutline Contact

ETFs On The Cutline – Updated Through 04/05/2019

Below, please find the latest High-Volume ETF Cutline report, which shows how far above or below their respective long-term trend lines (39-week SMA) my currently tracked ETFs are positioned.

This report covers the HV ETF Master List from Thursday’s StatSheet and includes 322 High Volume ETFs, defined as those with an average daily volume of more than $5 million, of which currently 280 (last week 236) are hovering in bullish territory. The yellow line separates those ETFs that are positioned above their trend line (%M/A) from those that have dropped below it.

Take a look:

The HV ETF Master Cutline Report

In case you are not familiar with some of the terminology used in the reports, please read the Glossary of Terms.

If you missed the original post about the Cutline approach, you can read it here.

ETF Tracker Newsletter For April 5, 2019

Ulli ETF Tracker Contact

ETF Tracker StatSheet

https://theetfbully.com/2019/04/weekly-statsheet-for-the-etf-tracker-newsletter-updated-through-04-04-2019/

ENDING THE WEEK ON A BULLISH NOTE

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

The much-anticipated March payroll report turned out better than hoped for with the BLS reporting that the US added 196k in payrolls in March, which was a tad higher than the 177k expected. This has analysts now proclaiming that February’s dismal gain of 20k, which was upwardly revised to 33k, was an outlier and that we have “normalized.”

While the headline print was all that the computer algos cared about, there was some weakness under the hood especially in manufacturing, shopping and a lower than expected average hourly earnings number. If you care to, you can read the details here.

Zero Hedge quipped:

So where was the Growth? Here are the three key sectors:

  1. Professional technical services: +34K, mostly computer systems design (+11.5K)
  2. Healthcare: +61K
  3. Food Services: +27K

 In other words, Americans are eating themselves into obesity, at which point they need constant medical supervision. The good news: at least the American food epidemic will provide waiter/bartender and medical jobs for a long time to come.

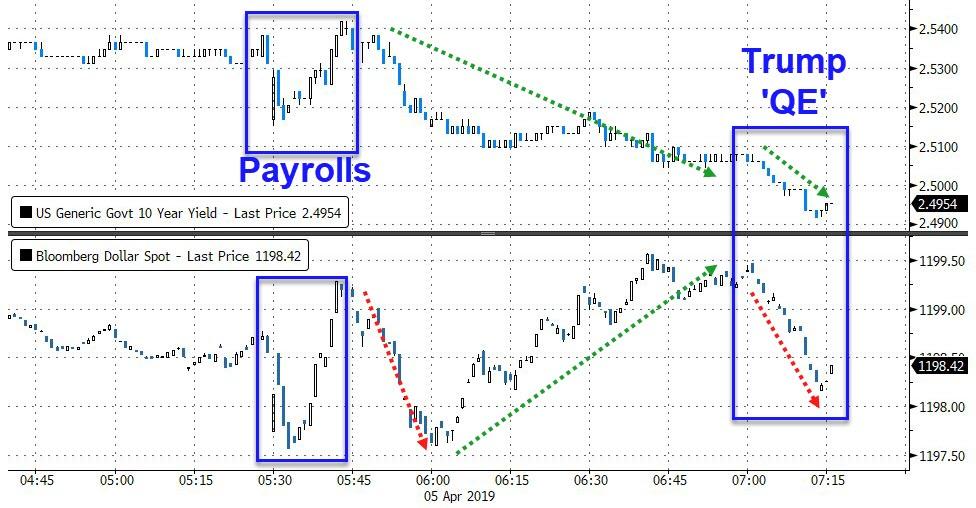
While there was no long-term effect on equities, Trump temporarily caused a bit of confusion when he slammed the Central Bank by commenting:

“I personally think the Fed should drop rates, I think they really slowed us down, there’s no inflation, in terms of quantitative tightening, it should really be quantitative easing…you would see a rocket ship. Despite that, we’re doing very well.”

Hmm, this sounds just about the opposite from his tweet on 9/29/2011:

“The Fed’s reckless policies of low interest and flooding the market with dollars needs to be stopped or we will face record inflation.”

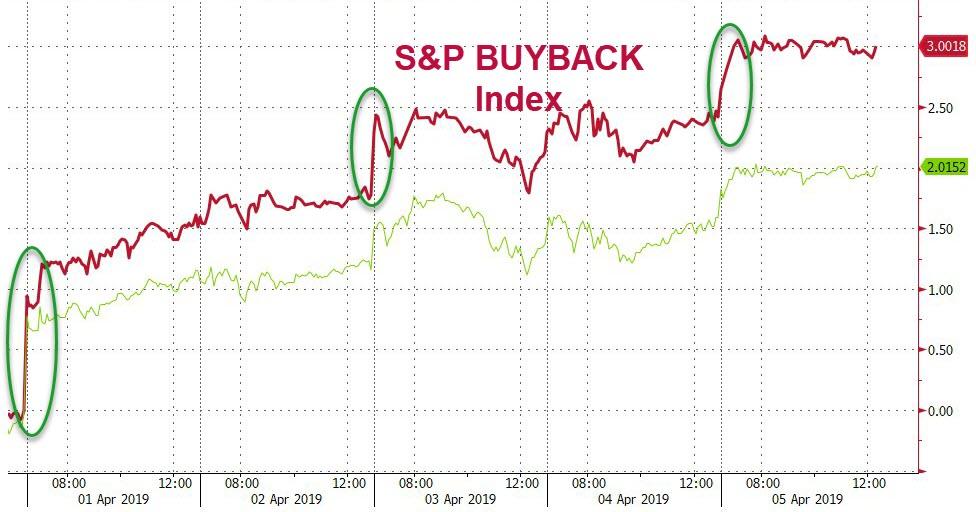
Be that as it may, the markets took it in stride with equities inching up and the S&P 500 closing at its high of the session. The biggest short squeeze in 2 weeks, along with Buybacks, added to bullish sentiment.

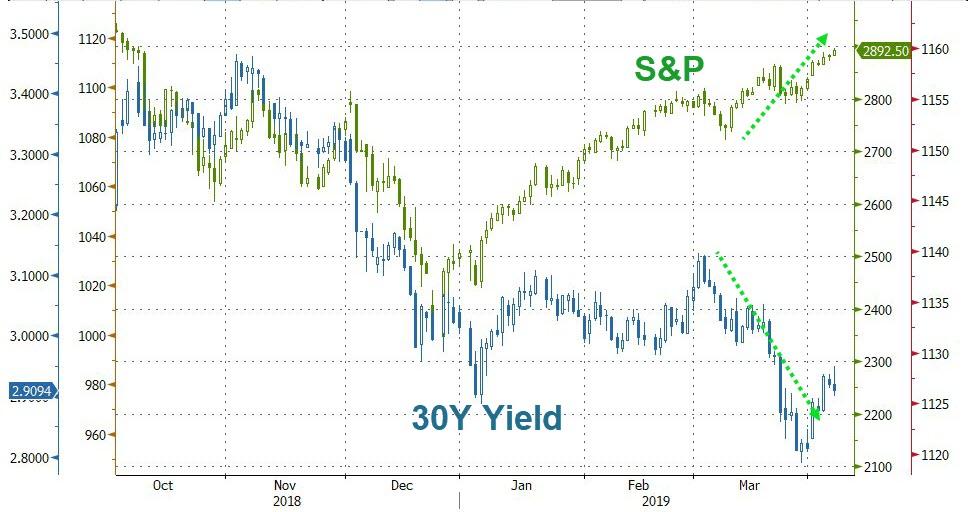
Still, the jaws of reality between stocks and bond yields paint a different picture and are widening every day. Sooner or later there will be an adjustment to bring this out of sync oddity back to normal.

The spread is currently some 500 S&P points, which means that a 20% drop of the index is required to normalize this relationship. To me, it’s not a question of “if” this happens but “when.”

Read More