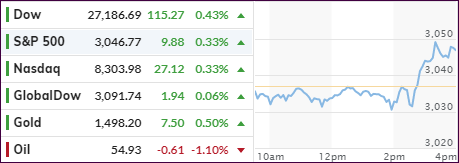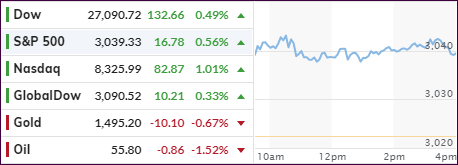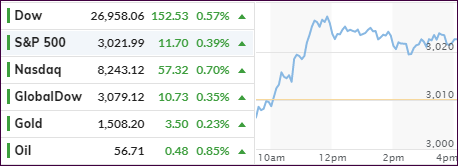
[Chart courtesy of MarketWatch.com]
- Moving the markets
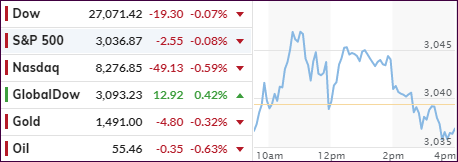
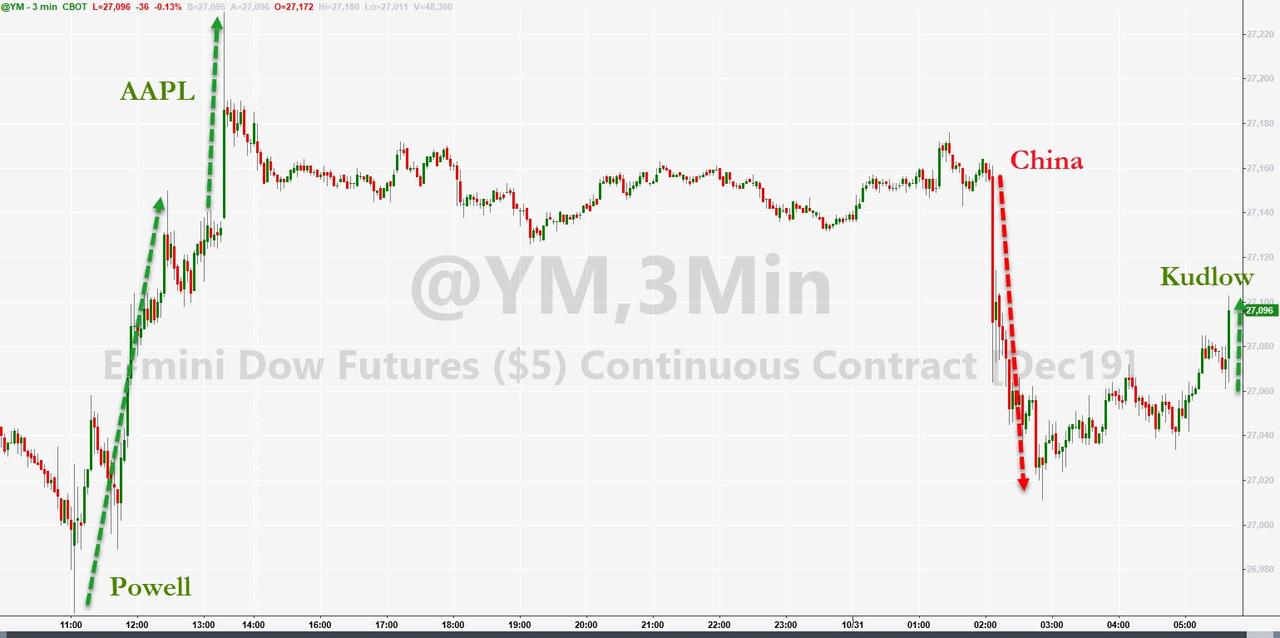
Despite the Fed’s market pleasing efforts yesterday, it appears that the US-China trade talks, or rather the lack thereof, have enough power left to affect market direction. Such was the case this morning when a report said that “Chinese officials have doubts about the prospects for a long-term trade deal with the US.”
Attempting to dampen the subsequent fall of equities, Trump came out and announced that a “transitional deal” would be still signed soon, although the warring parties need to pick a new site for this event, as the previous host, Chile, canceled the mid-November summit.
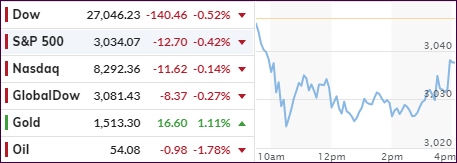
Just the fact that the Dow was down a “shocking” 240 points this morning caused all kinds of action by the administration, as economic advisor Kudlow came out and attempted to jawbone the markets higher with goodies like “US-China talks going smoothly.” It did have a momentary positive effect, as this chart shows.
Then the blame game continued with Trump seething that “China’s not our problem, The Fed is.” You almost have to laugh at the silly notion that it seems no longer acceptable to have a minor correction, let alone a normal downturn as part of the business cycle. But that’s the world we live in, and we must deal with it.
In the end, the month of October, also known as the bull market killer, turned out better than expected, although it started out on a negative note with a 2-day sell-off. That was short-lived, and we seesawed higher with the S&P 500 closing the month with a respectable +1.9% gain.
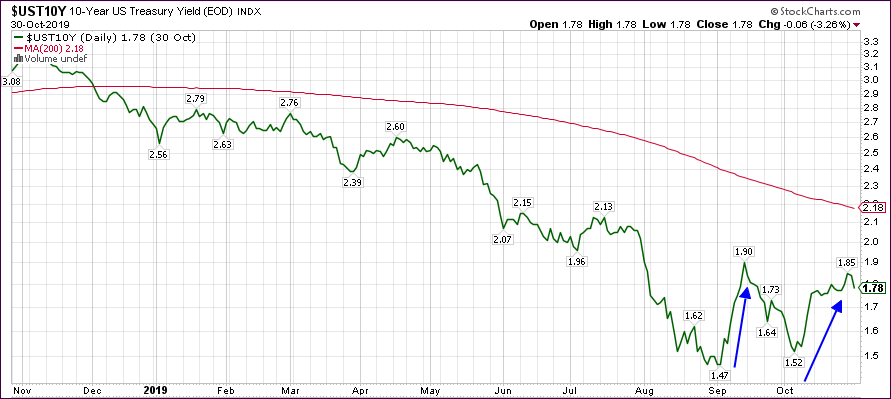
It’s low volatility cousin, SPLV, did not fare as well and got blindsided by bond yields, which rose despite the Fed’s easing efforts. Just like in September, this chart shows the rebound in the 10-year yield (blue arrows), which affected SPLV negatively due to its interest rate component. Even though, SPLV gave back -0.58% this month, it remains ahead of the S&P 500 in YTD ‘Buy’ cycle performance.
Read More