ETF Tracker StatSheet
You can view the latest version here.
AN EARLY RALLY BITES THE DUST—AGAIN
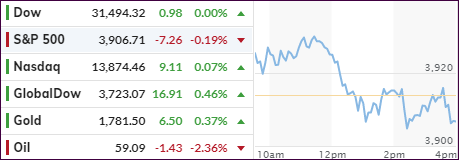
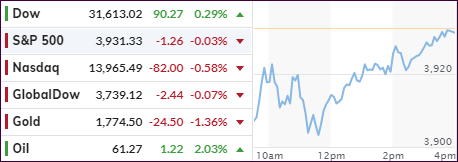
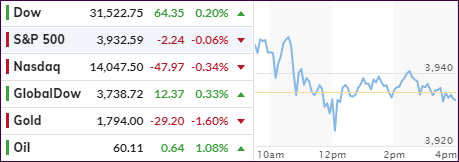
[Chart courtesy of MarketWatch.com]
- Moving the markets
Today resembled just how the week went for the major indexes. Early rallies lost steam, and this session was no exception, with the indexes ending the day at their respective unchanged lines. Overall, the pullback was modest with the S&P 500 surrendering -0.71% since last Friday.
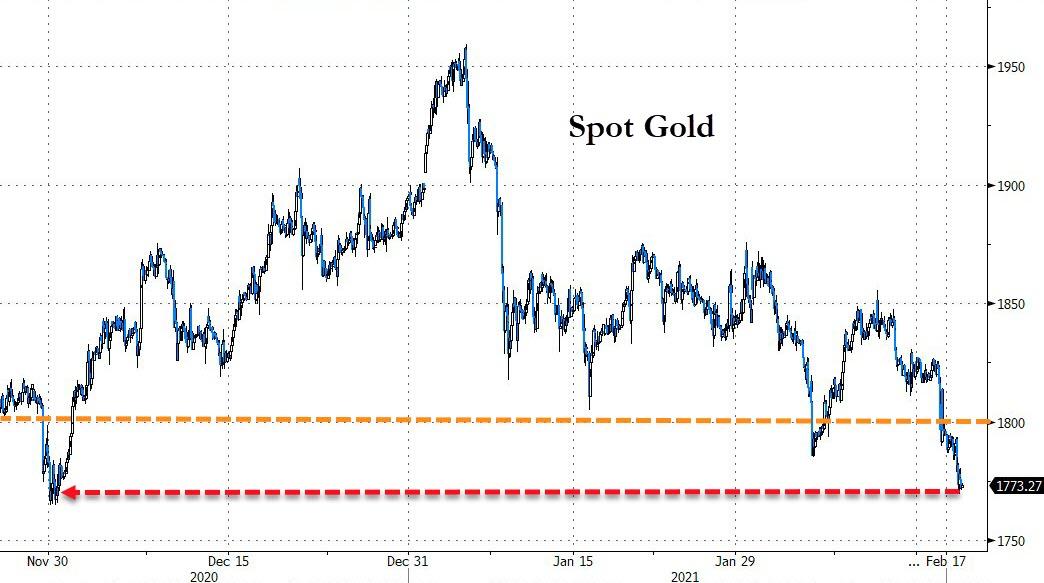
A mix of rising interest rates (higher inflation), and some profit taking in the tech sector, dampened early enthusiasm and turned this session into a non-event. Bucking the pullback were SmallCaps (IWO), which catapulted higher by +2.08%, with MidCaps (IWP) joining in by rising +0.71%. Even Gold (GLD) withstood higher bond yields and added +0.42%.
CNBC chimed in like this:
The strength among economically sensitive stocks came after Treasury Secretary Janet Yellen told CNBC Thursday after the bell that more stimulus is necessary even as some economic data suggested a rebound is already underway. She added a $1.9 trillion stimulus deal could help the U.S. get back to full employment in a year.
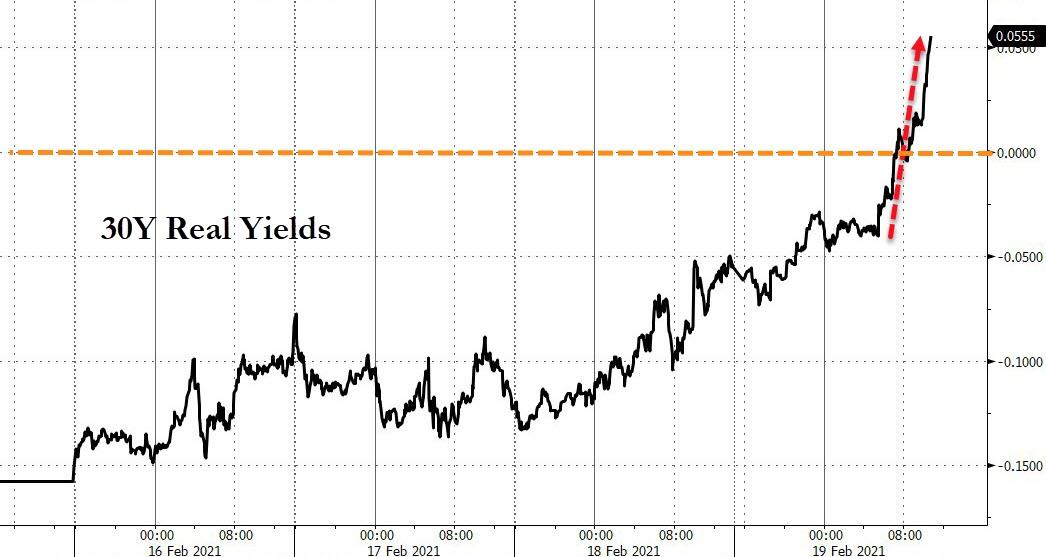
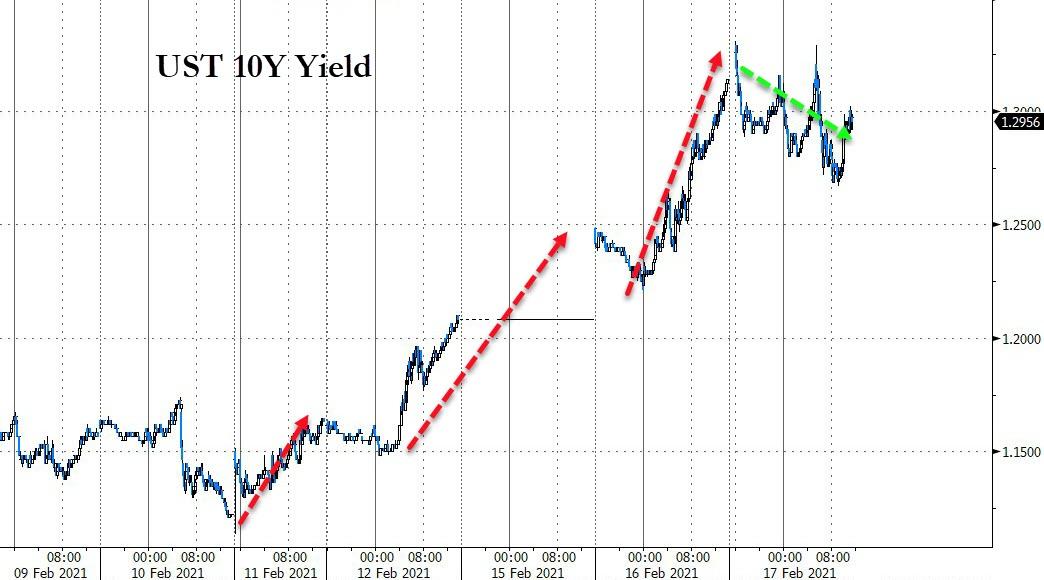
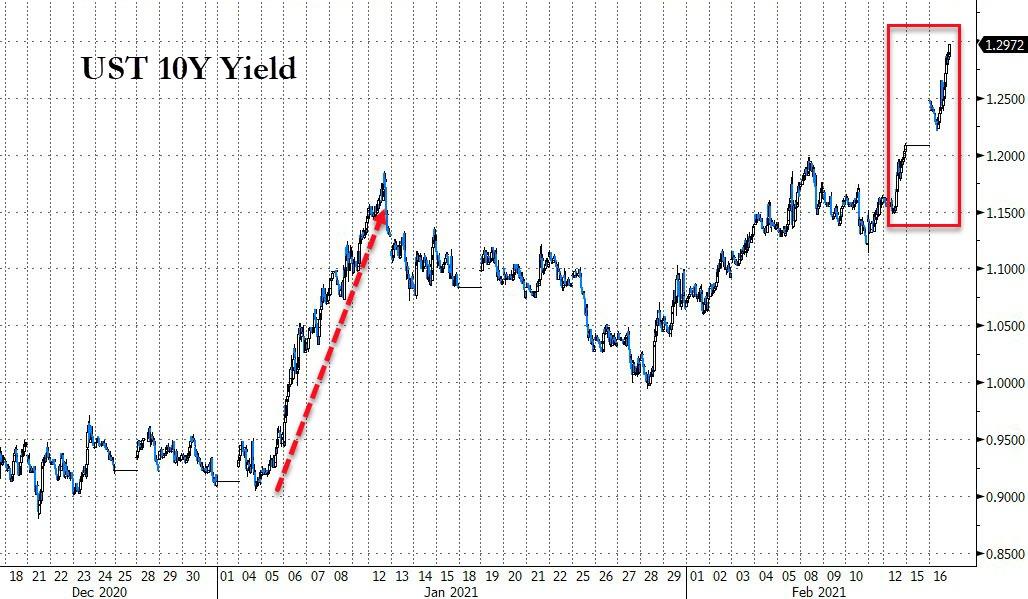
The direction of bond yields will be the key component affecting the stock market trend. The 10-year Treasury yield rose to the highest in almost a year, and today added another 5 basis points to 1.34%. Some analysts think that if the 1.50% level is breached, this equity bull run will be in serious jeopardy.
One look at this chart shows what happened to the S&P 500 last time yields rocketed higher. This graph (ZH/Bloomberg) demonstrates that 30-year yields have surged the most since March 2020.
For sure, we will see an increase in volatility next week, as options expirations are on deck, an event that can spook markets and create uncertainty about future direction. Of course, should that happen, rest assured that the powers to be (Fed) will step in to placate the nervous nellies to restore calm, order, and bullishness.
And that sums up the kind of environment we are in.
Read More