[Chart courtesy of MarketWatch.com]
- Moving the markets
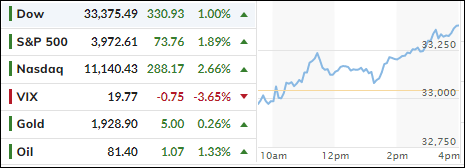
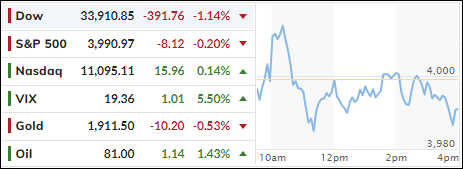
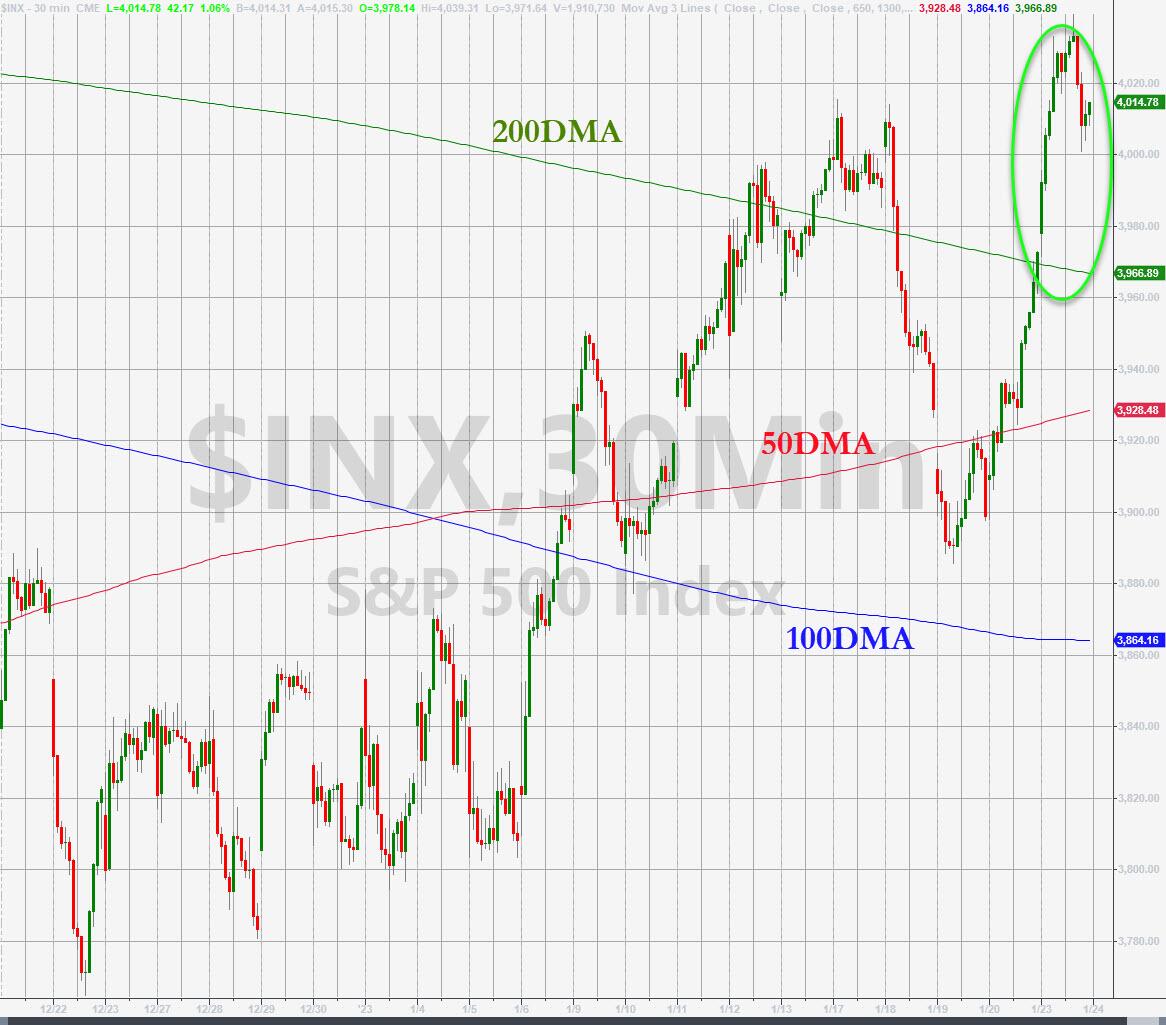
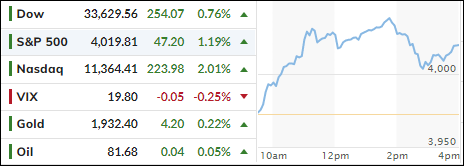
An early Ramp-A-Thon lost some momentum during mid-session, but the pullback was contained and still enabled the major indexes to close solidly in the green.
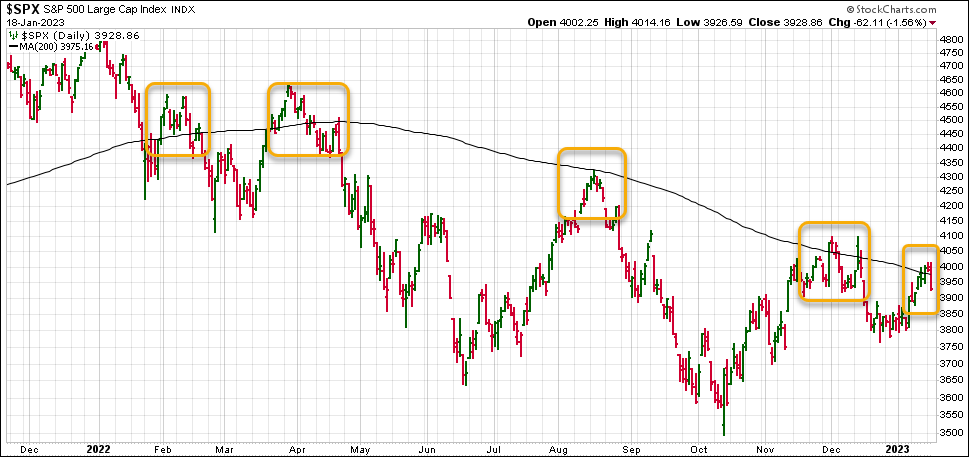
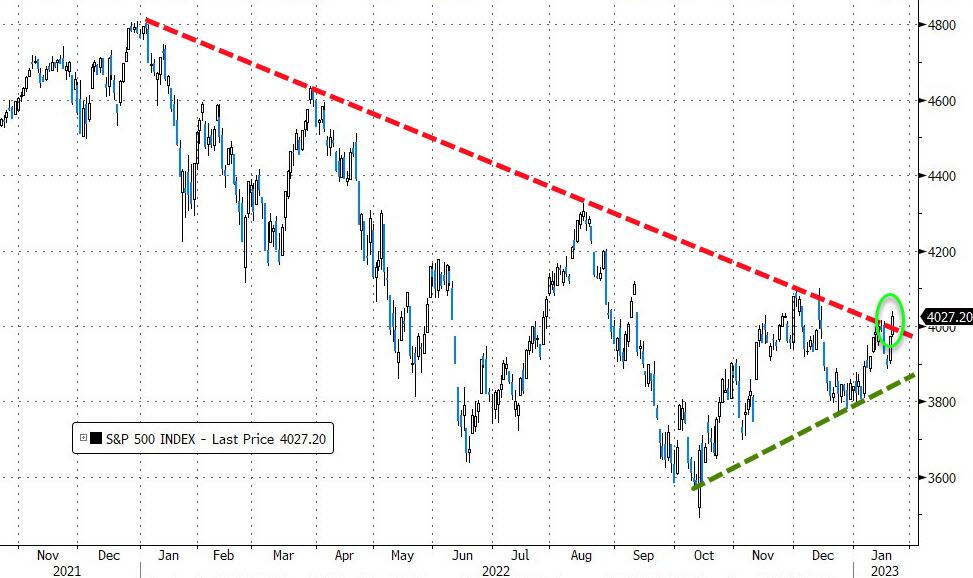
While the S&P 500 managed to finally break above its 200-day M/A, it was not yet able to hold the move above its longer-term downtrend line, which had been a insurmountable resistance point throughout 2022.
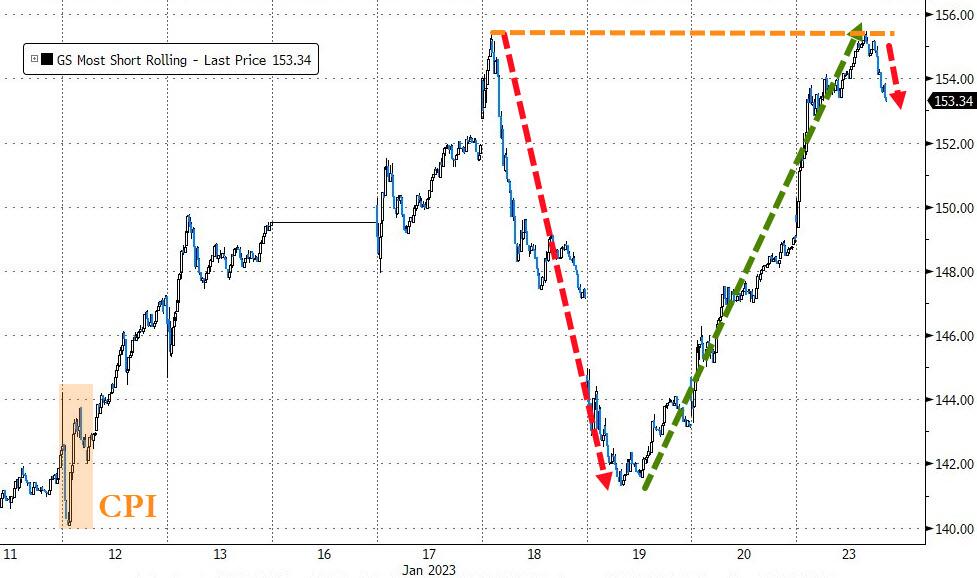
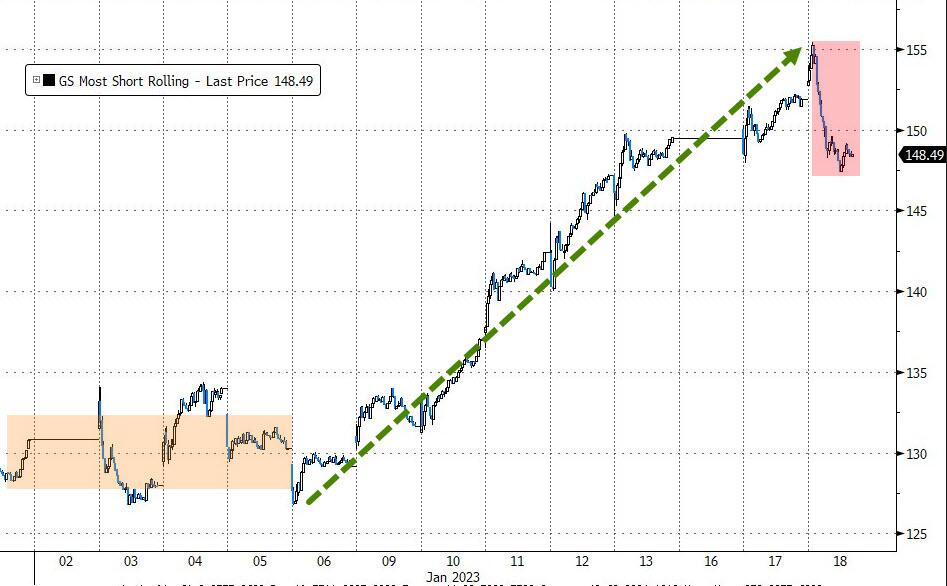
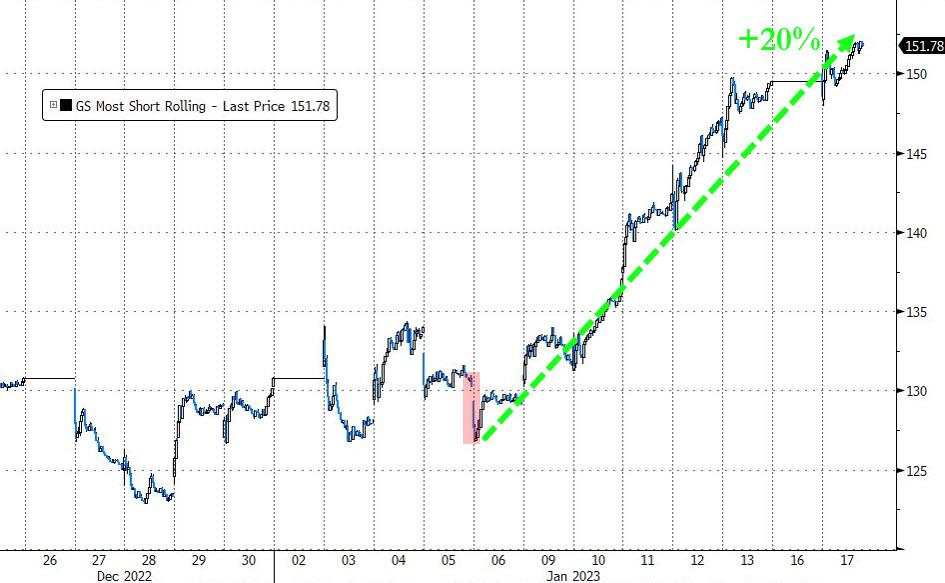
Supporting today’s follow through from Friday was the continuation of the short squeeze, without which there would have not been enough upward momentum. That brings up the question whether this session simply represented the reloading of the shorts, as ZeroHedge described it.
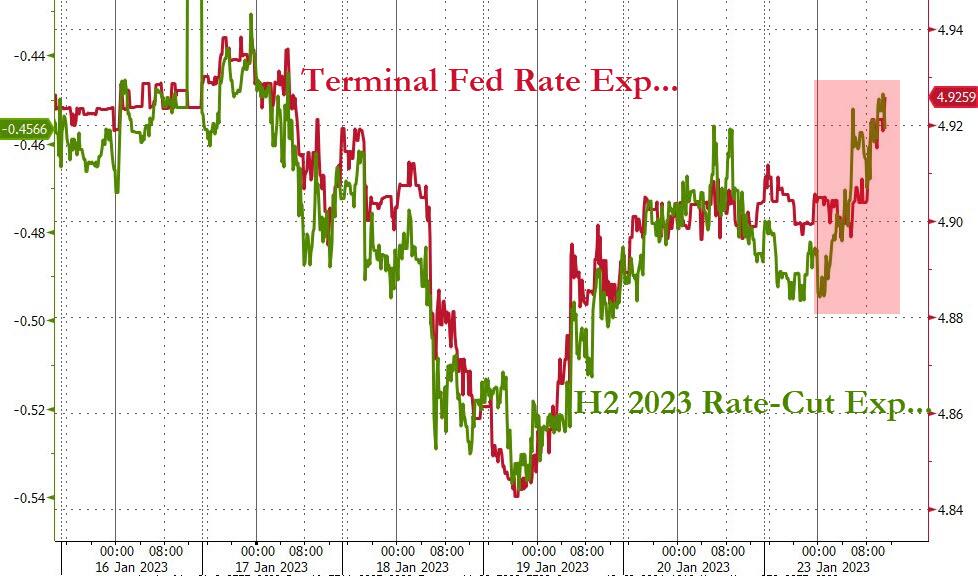
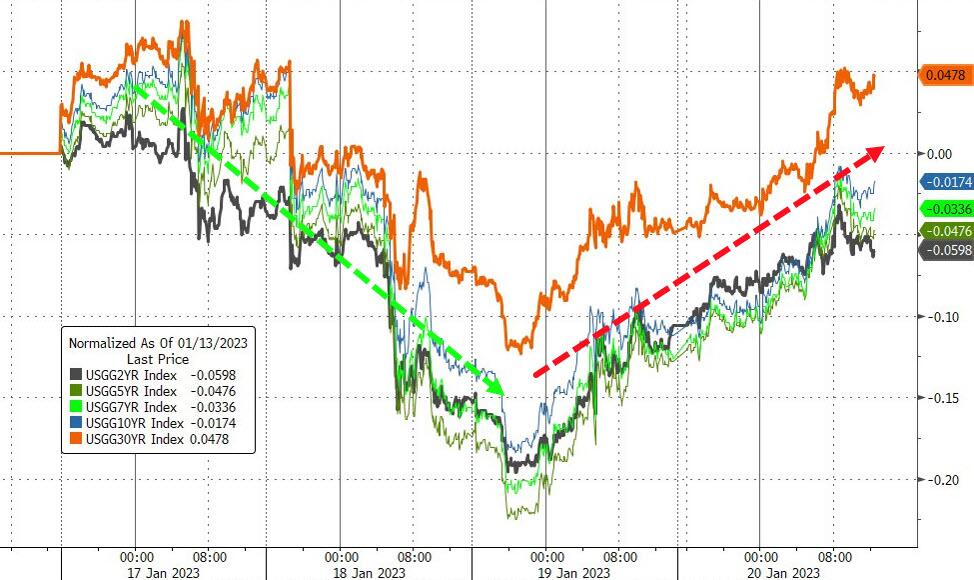
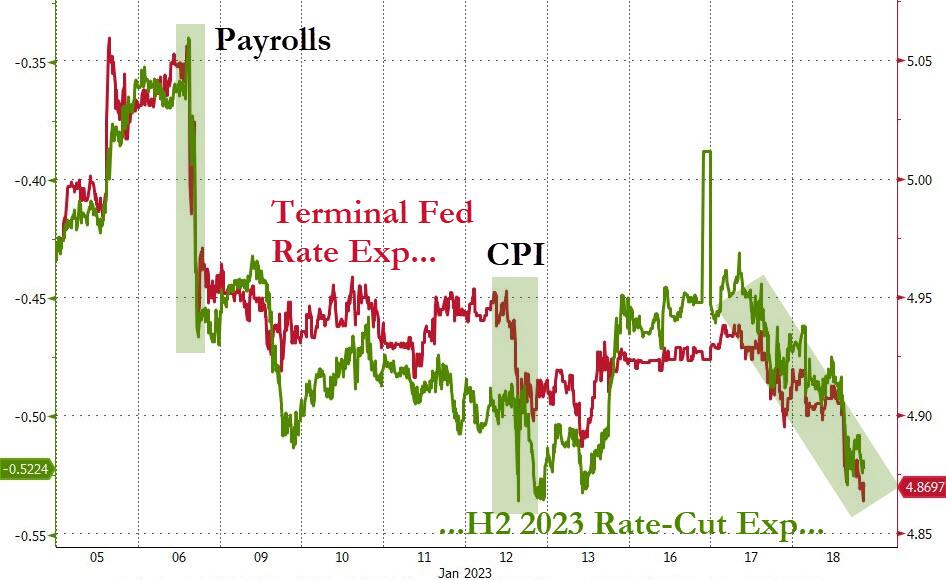
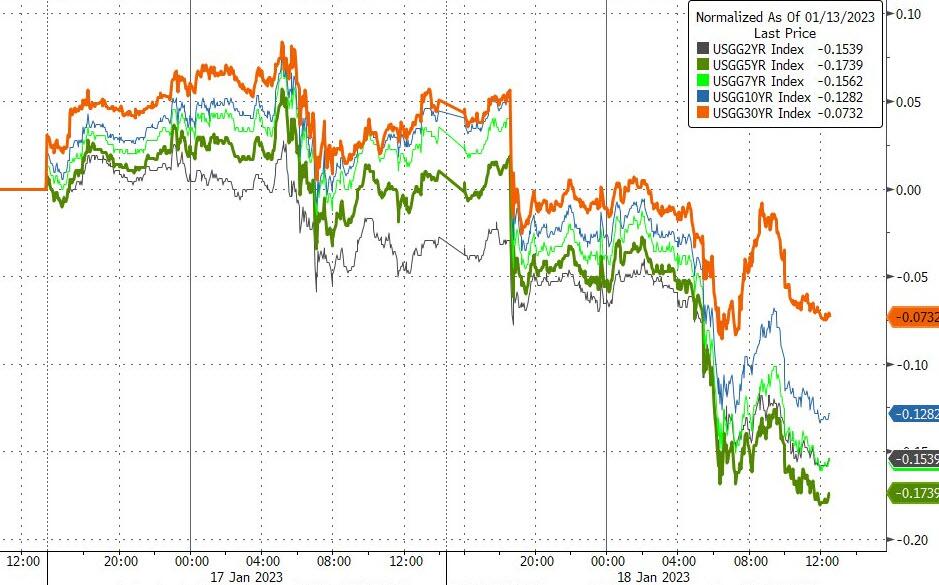
Traders still contemplated a potential slowdown in rate hikes, thereby stubbornly taking the opposite view of what the Fed and its mouthpieces have been jawboning about for months now, namely “higher rates for a longer duration.” Of course, there is always a possibility of only a +0.25% hike when the Fed meets early February.
Earnings will be closely watched this week, as some big names like Microsoft, IBM, Tesla, Visa and Mastercard will be presenting their report cards. As always, future guidance will be at the center of attention for most analysts.
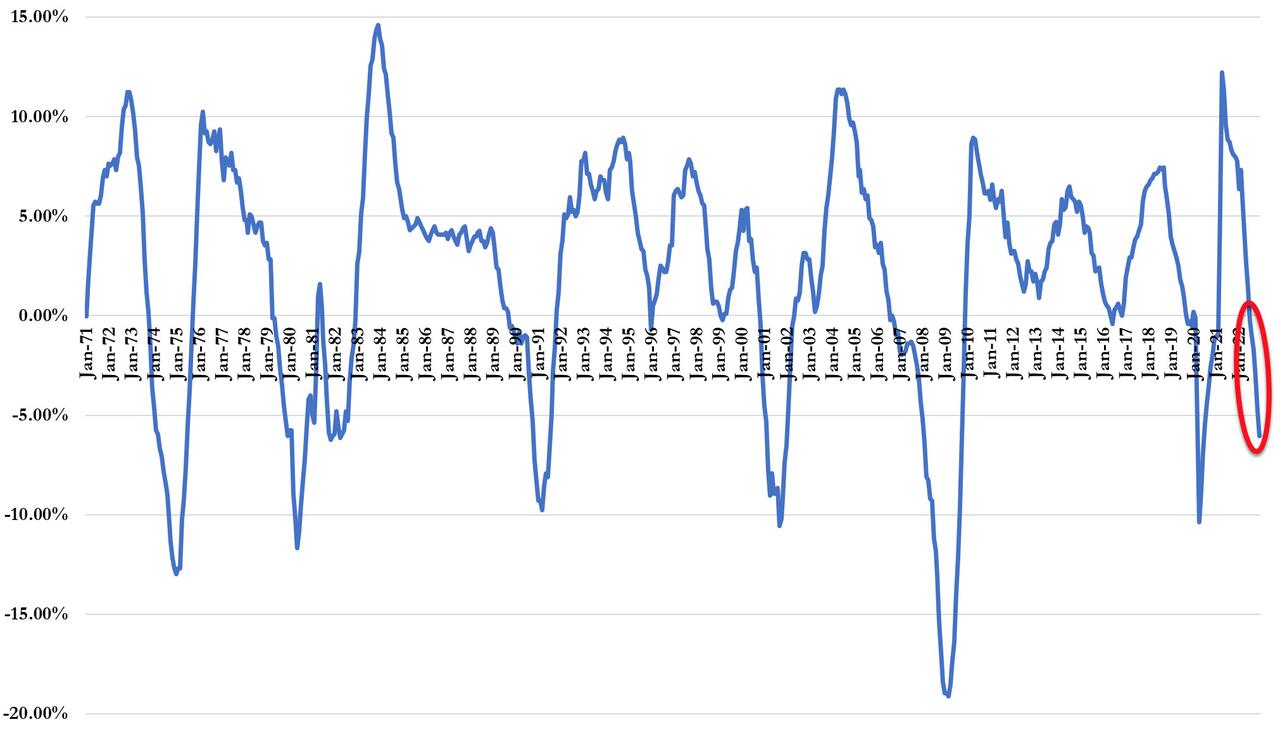
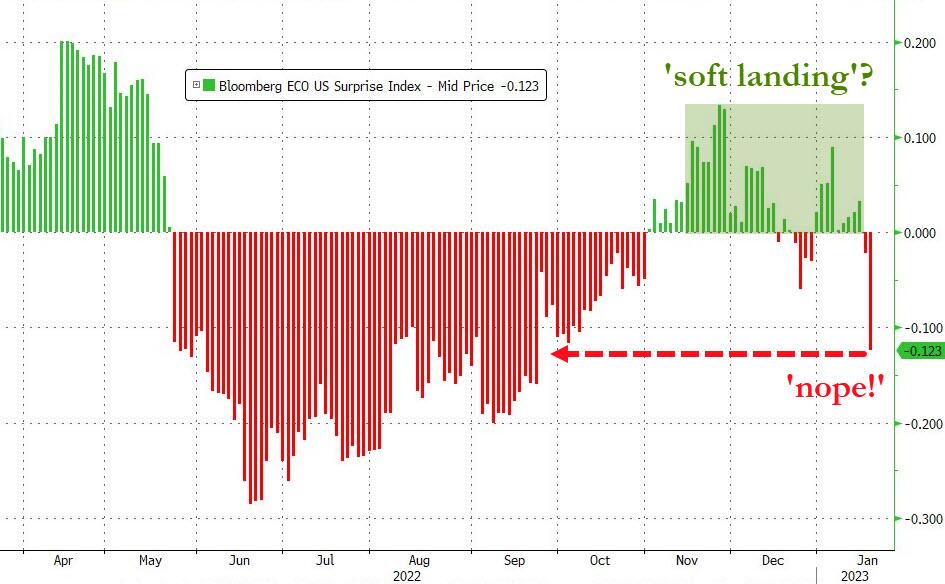
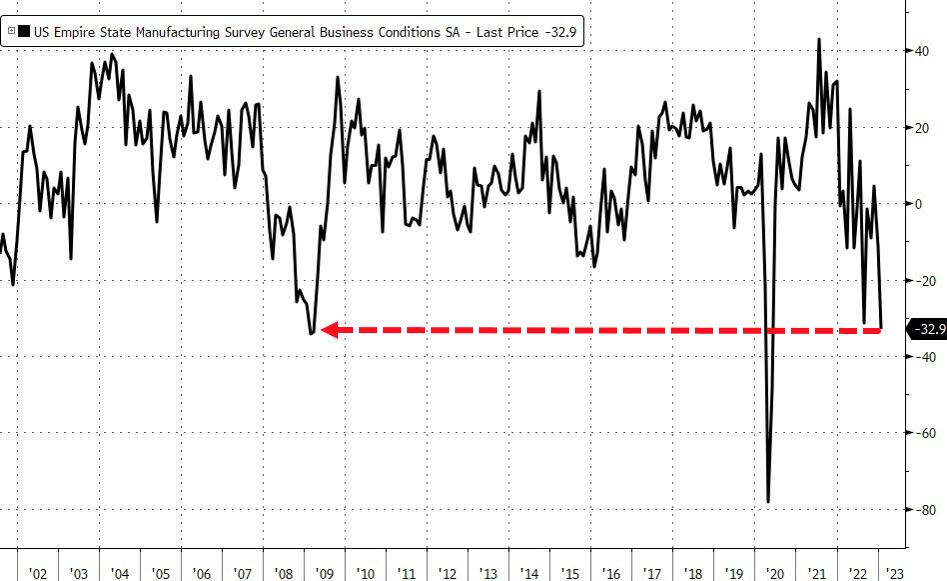
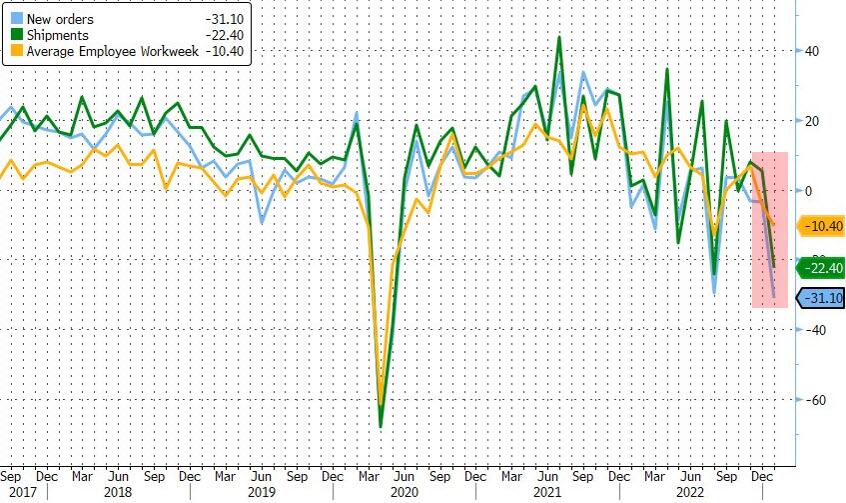
Much overlooked are figures like the Leading Indicator (LEI), which clearly shows that the “soft landing” theme may not work out as had been anticipated. Stocks ramped anyway and even rate-trajectory expectations drifted higher (more hawkish), which makes me wonder how much more firepower is left in the bullish scenario.
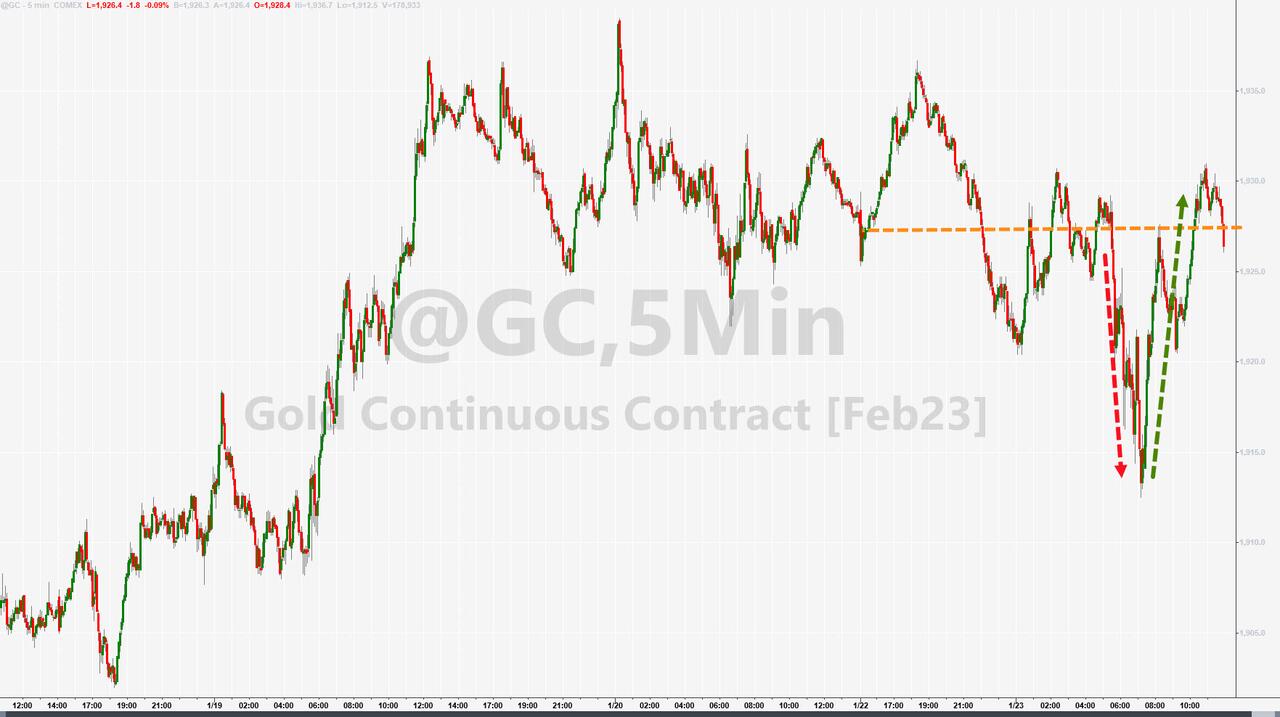
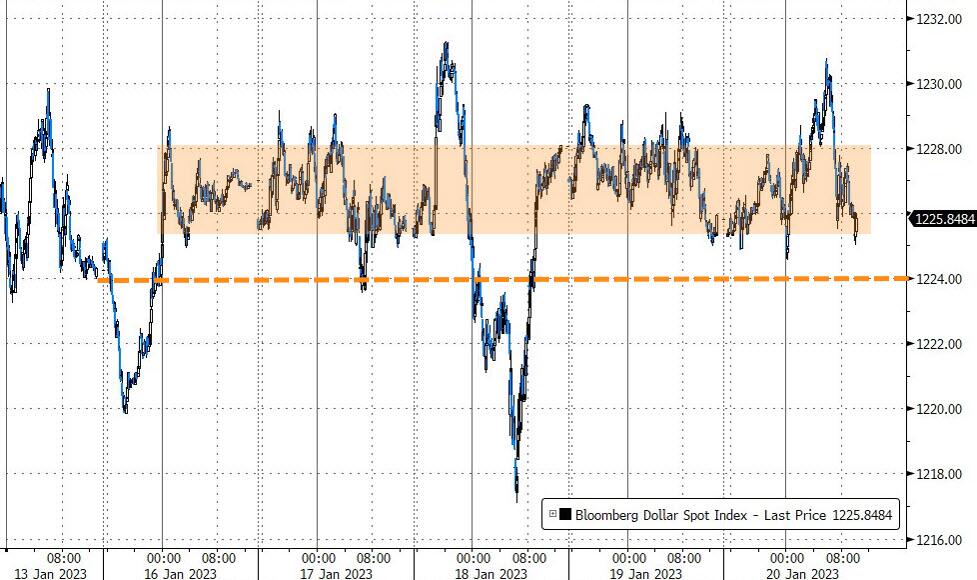
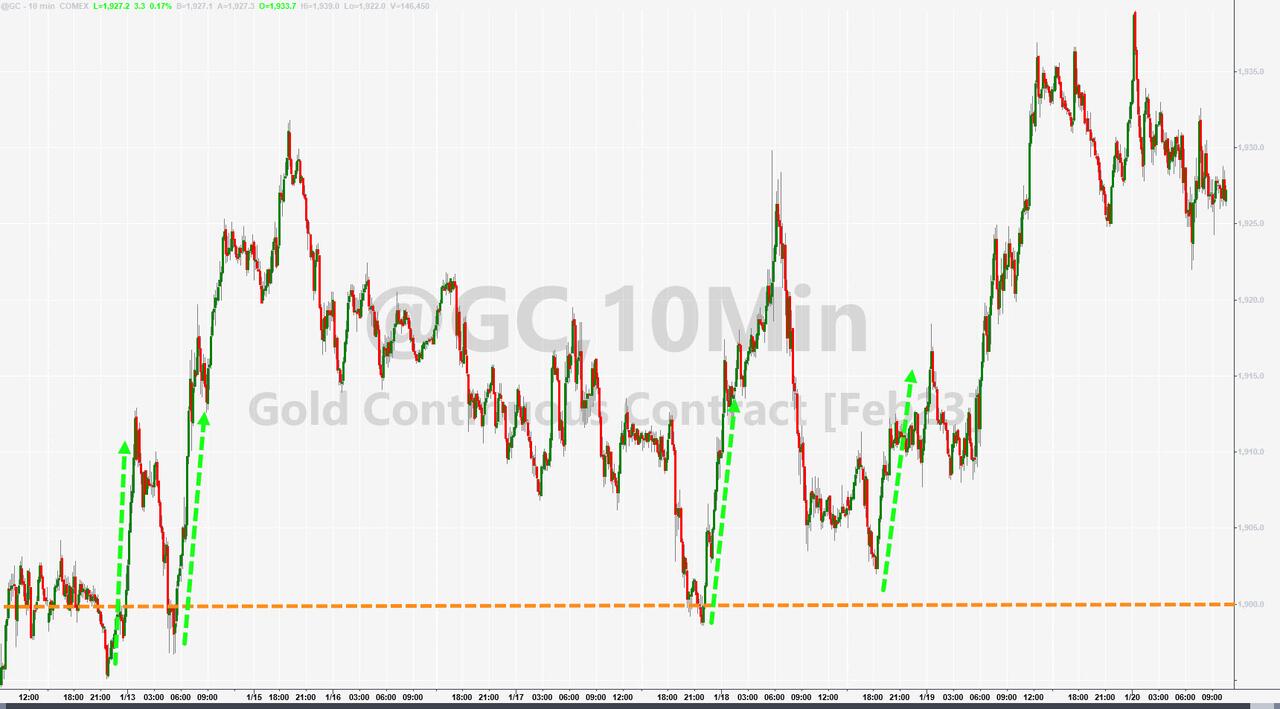
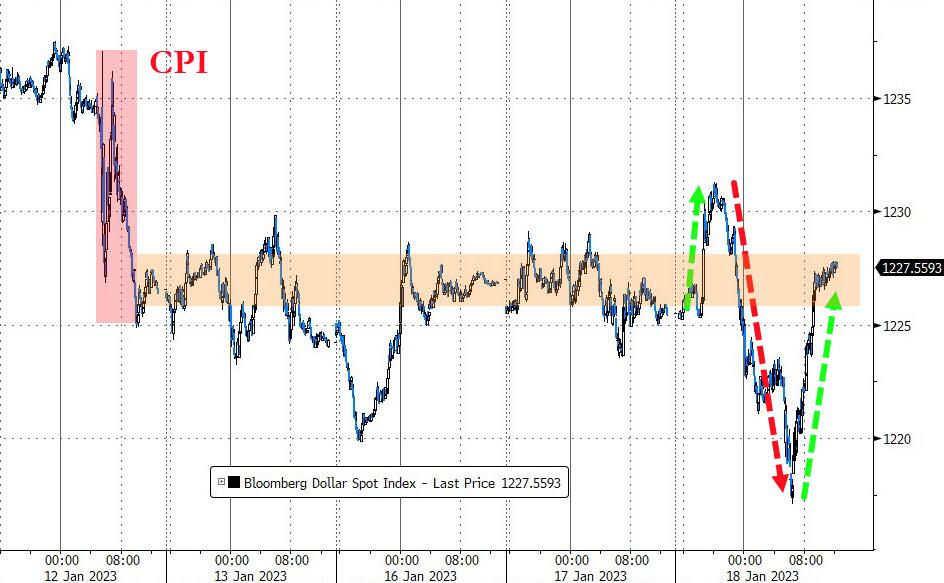
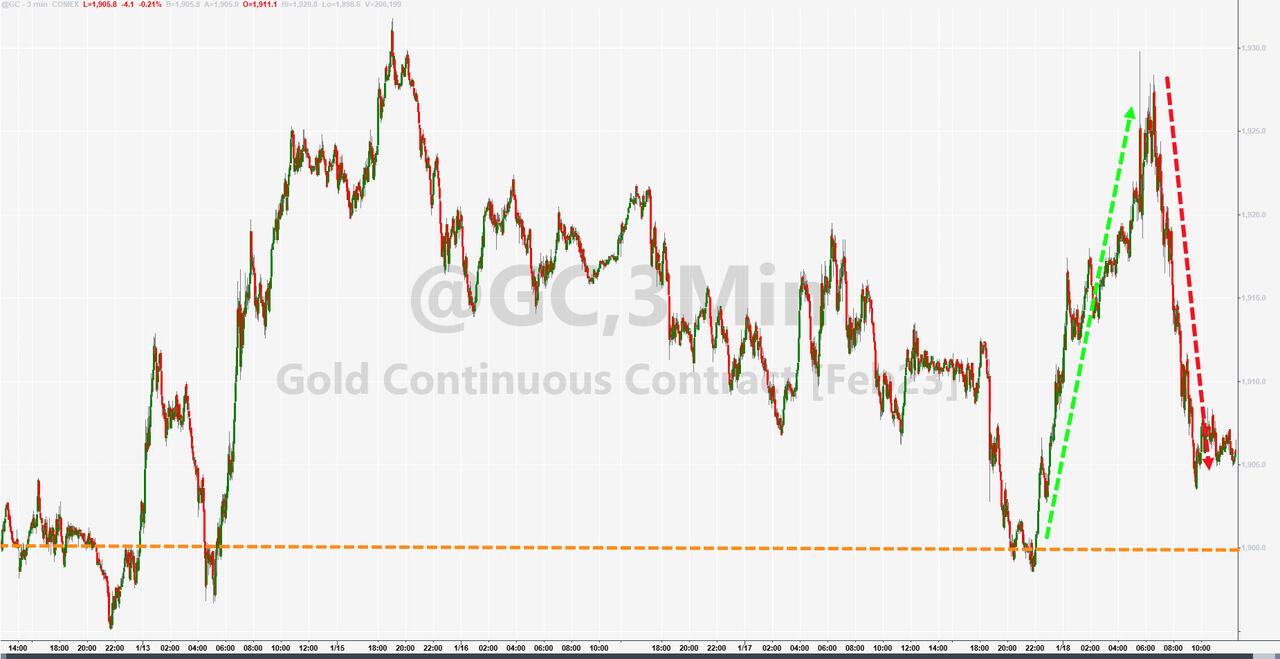
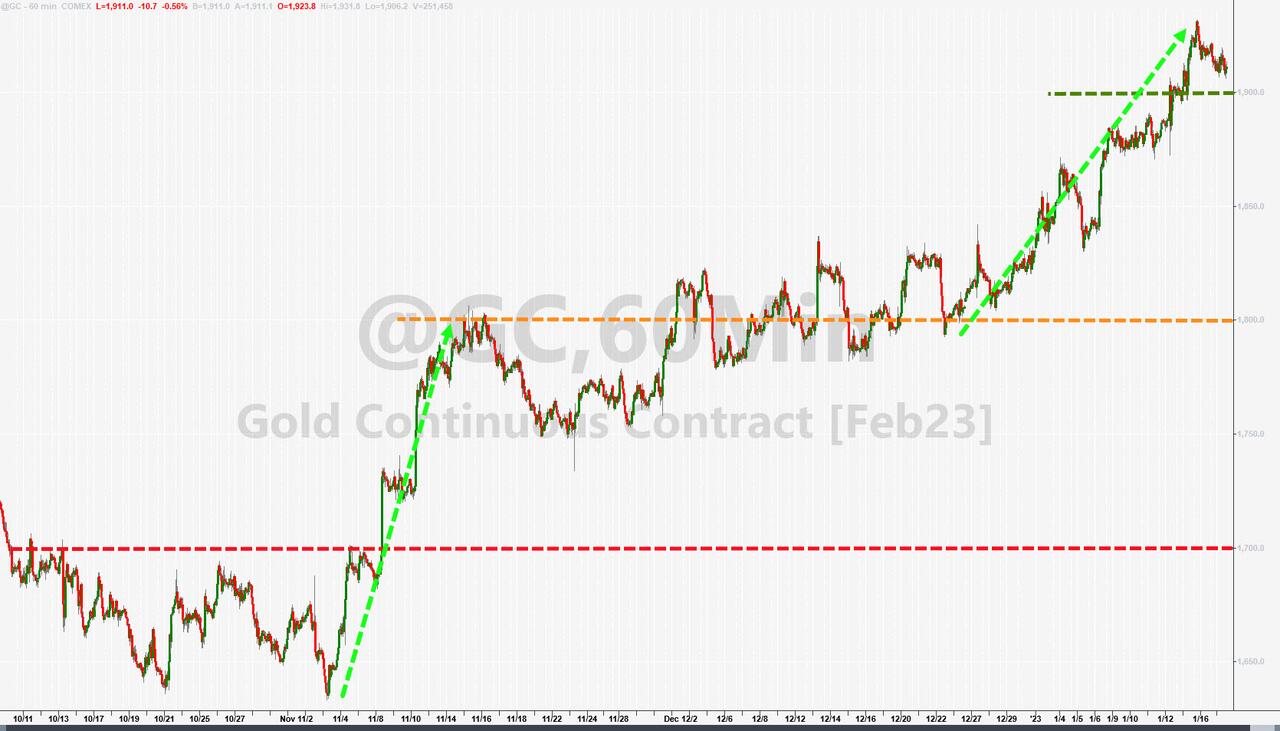
The US Dollar dropped and popped, went sideways, and closed just about unchanged. Gold pumped and dumped and managed to eke out a small gain.
Read More