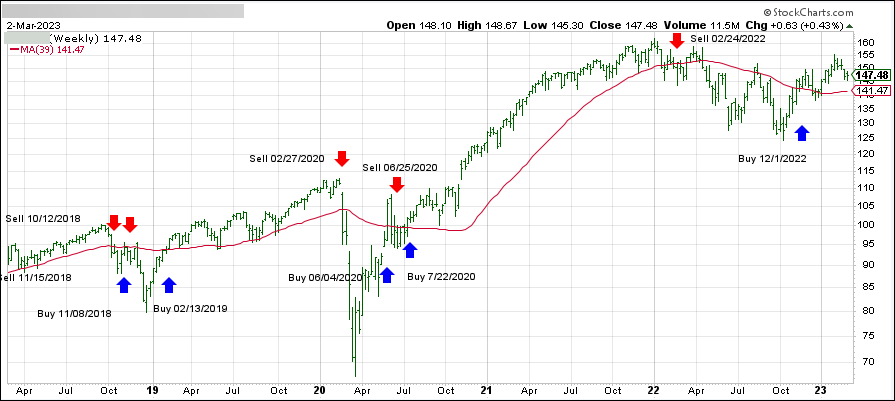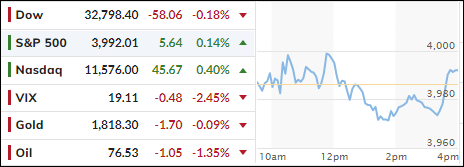
[Chart courtesy of MarketWatch.com]
- Moving the markets
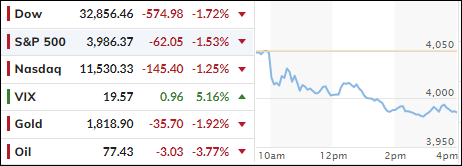
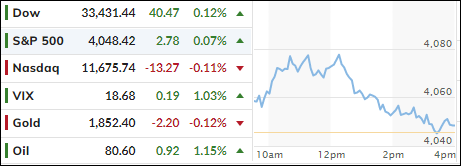
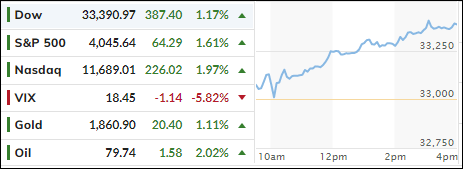
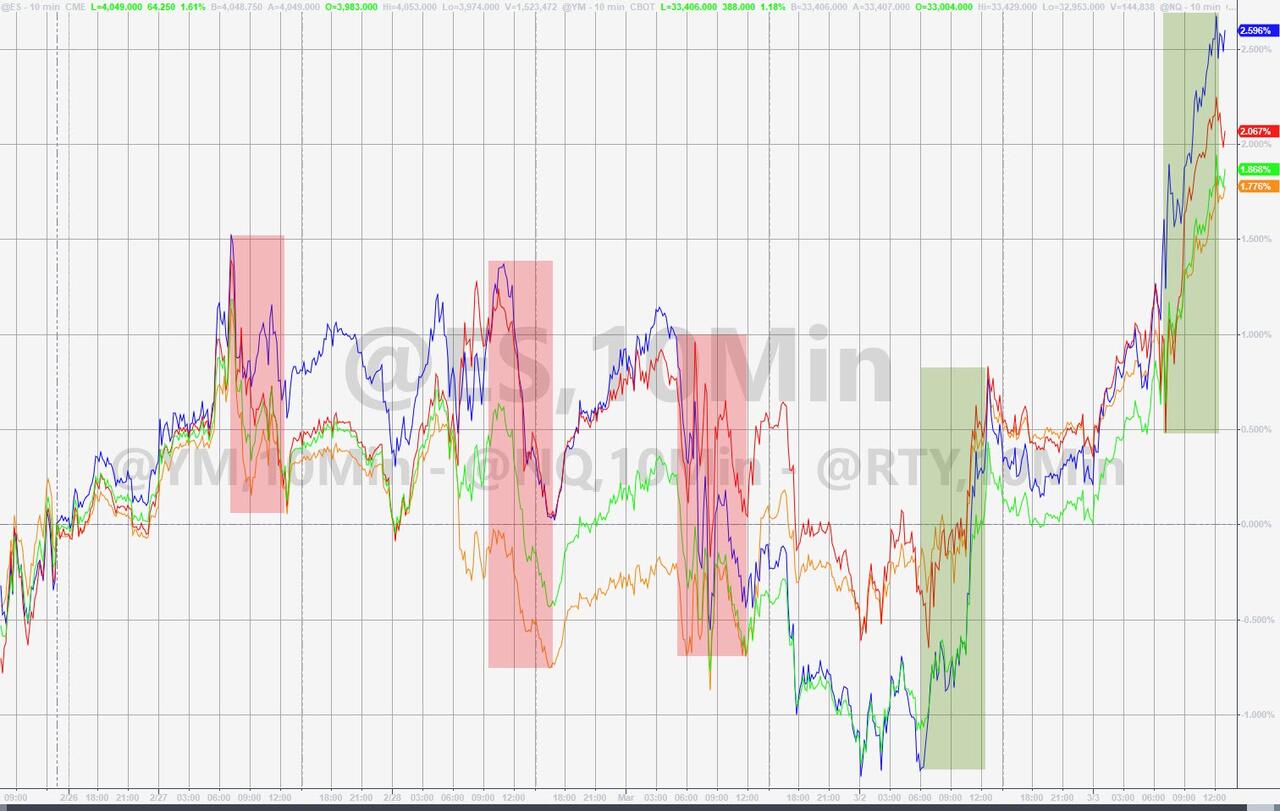
Despite a last hour attempt to prevent another session in the red, after yesterday’s slam, the major indexes managed to climb back to their respective unchanged lines, as dip buyers were conspicuously absent. However, a late Market on Close (MOC) program propelled stocks off their lows.
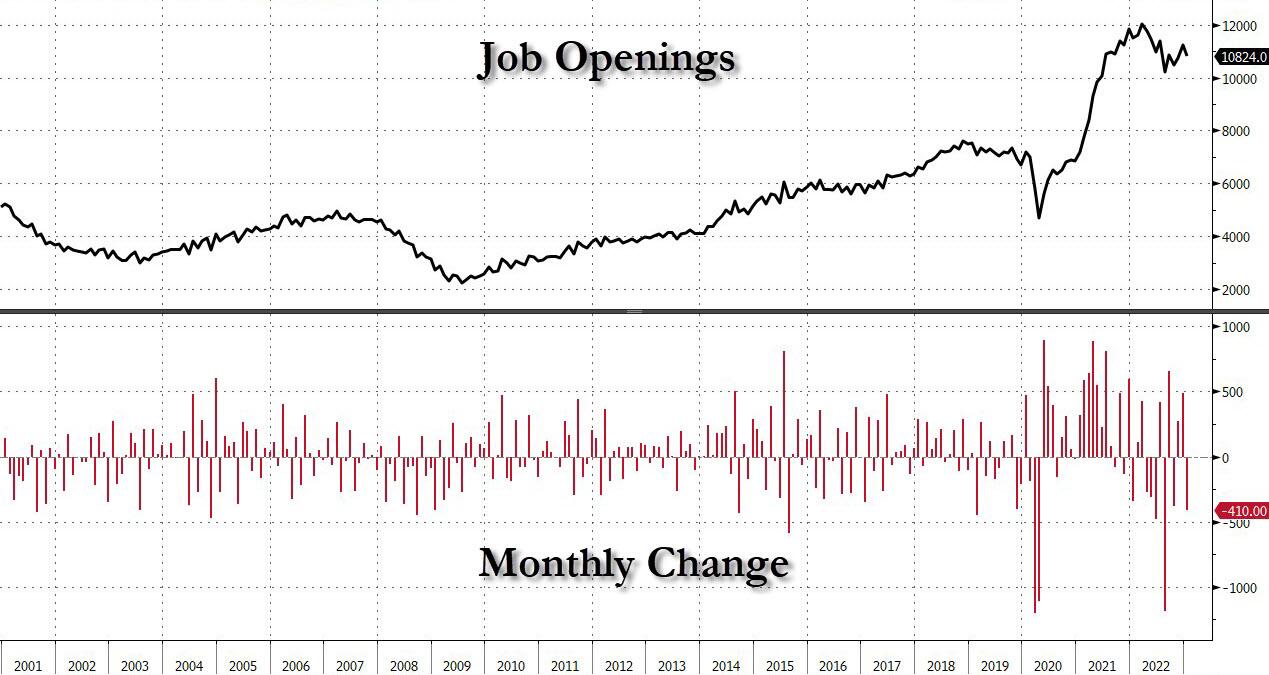
Economic data points were solid due to persistently strong job openings beating expectations, despite a plunging number of quits. As ZeroHedge pointed out, this was the fifth consecutive beat of expectations, which was disappointing for the ever-present dovish “pause or pivot crowd.”
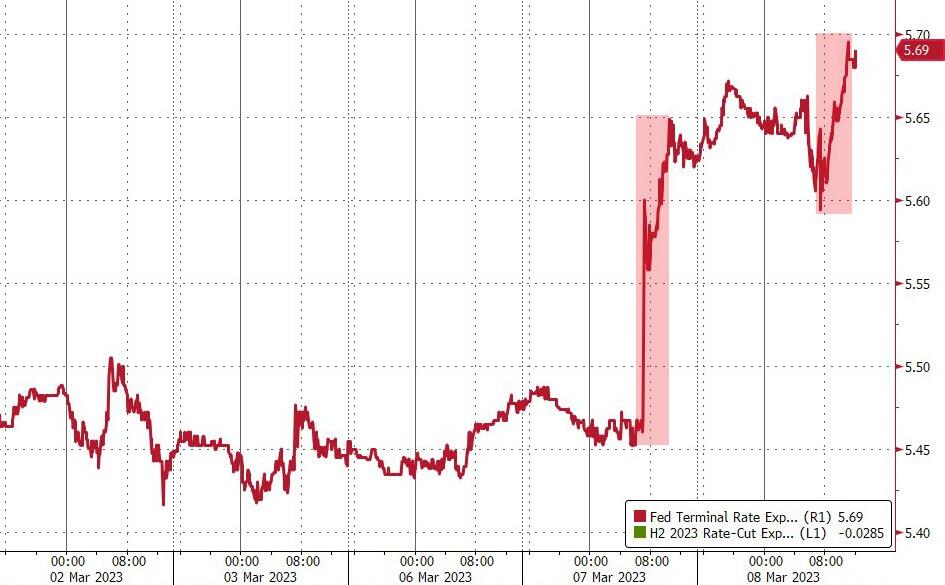
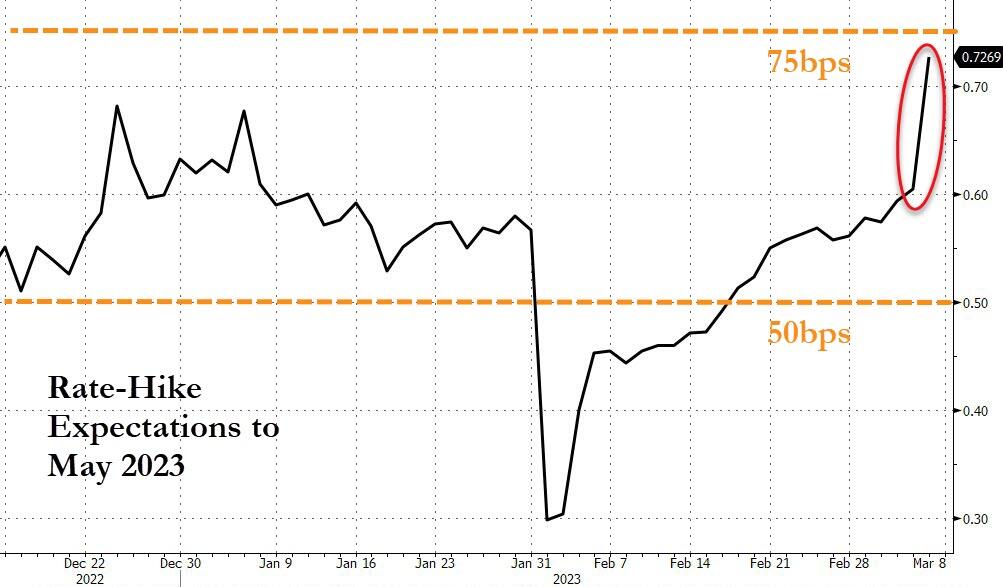
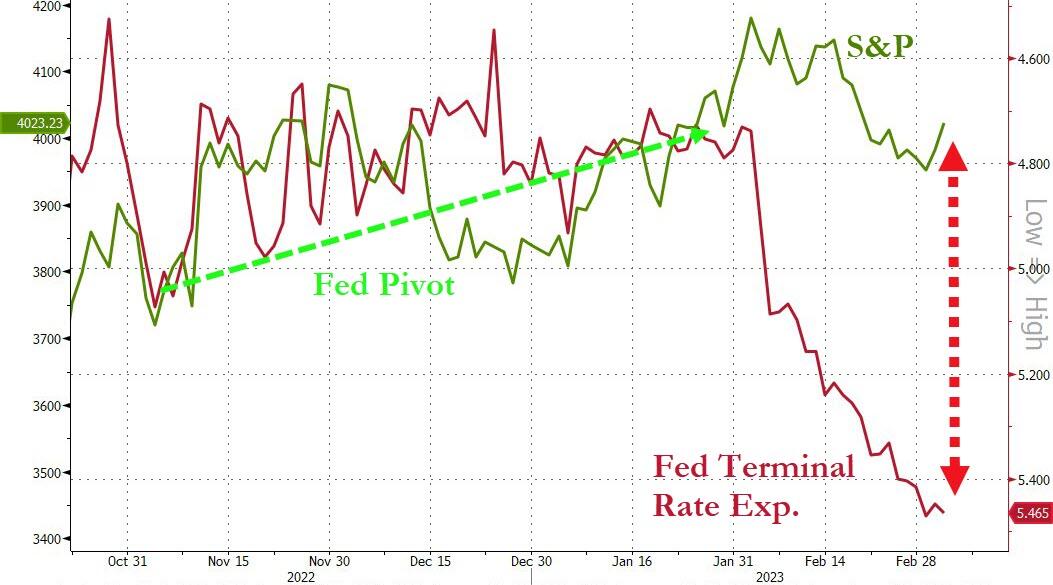
February’s ADP private payroll report confirmed that the economy stands on firm ground, at least for the time being. That sent rate hike expectations surging towards the 5.70% marker, while the odds of A 50bps hike in March sprinted to 70%.
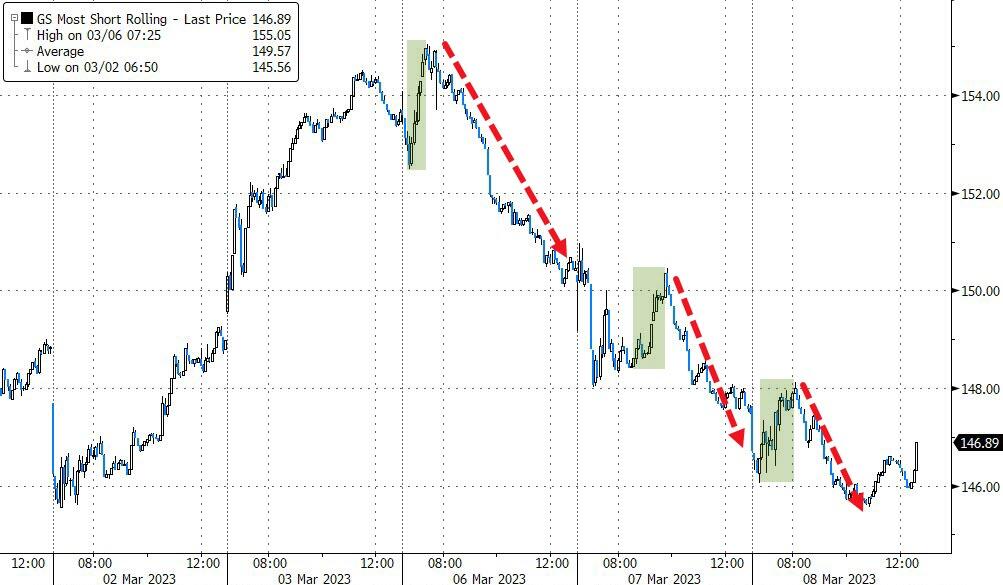
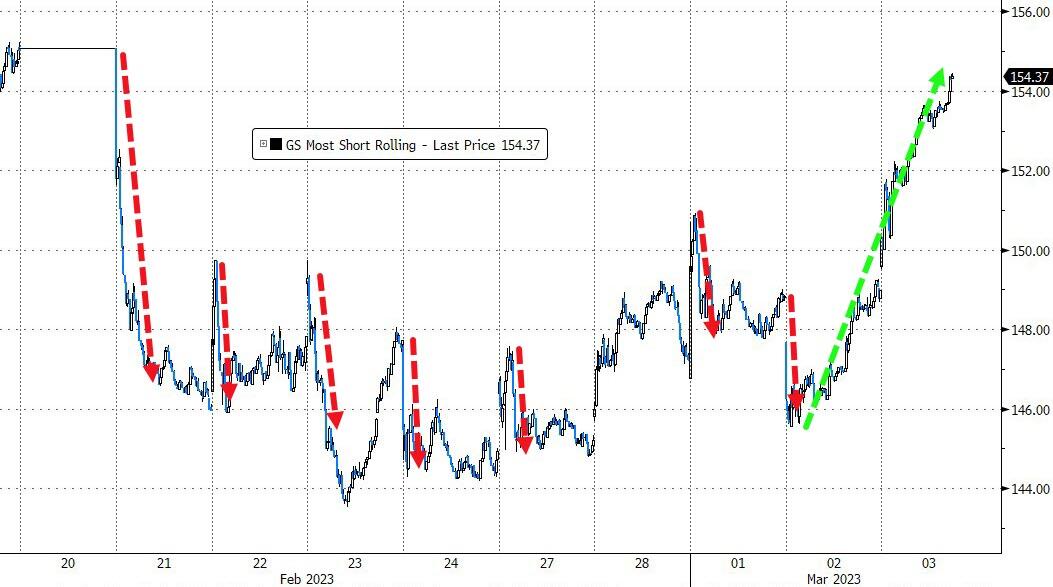
In the absence of a short squeeze, the “most shorted stocks” limped lower for the third consecutive day thereby aiding bearish momentum.
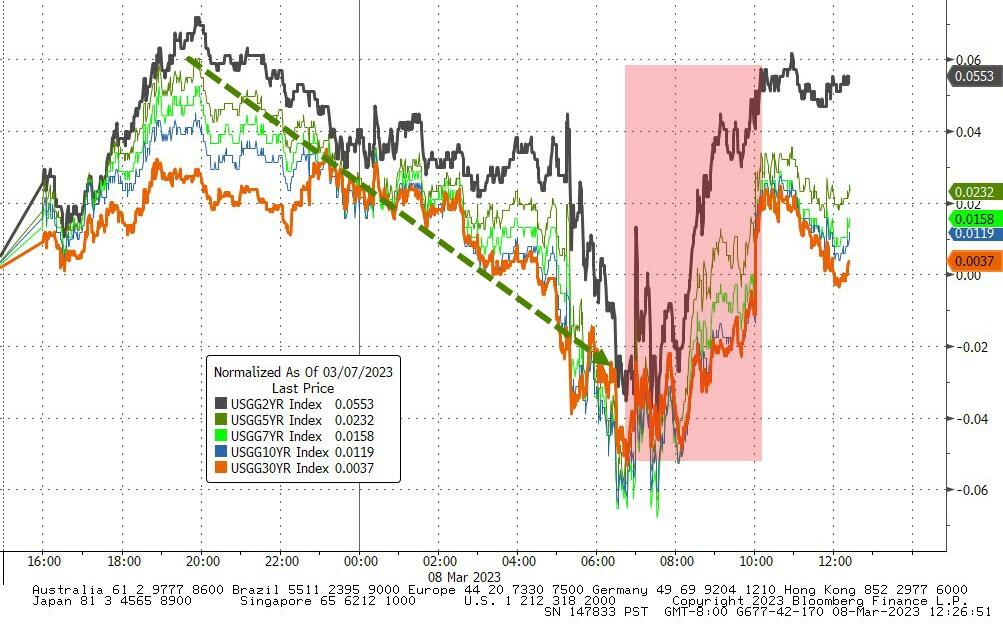
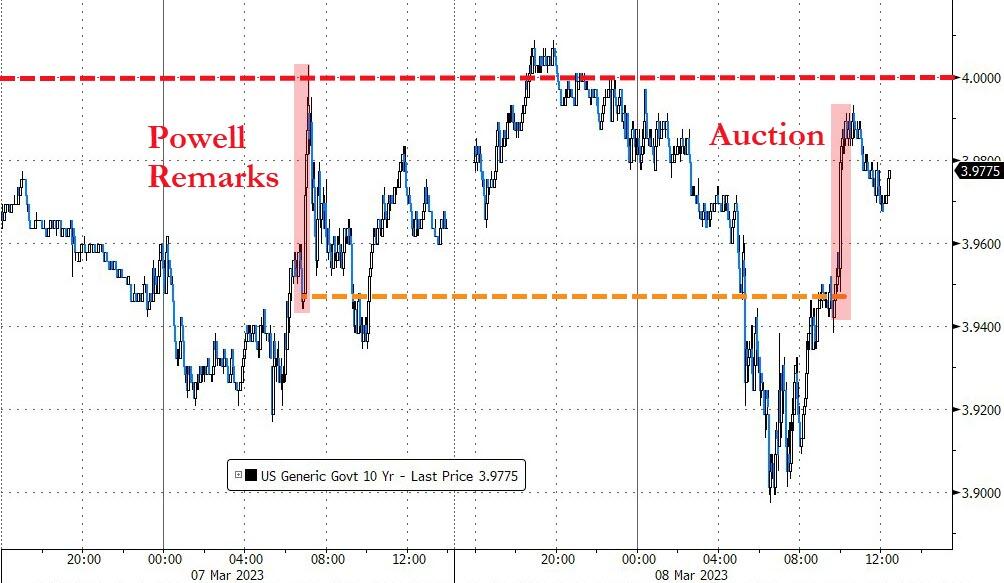
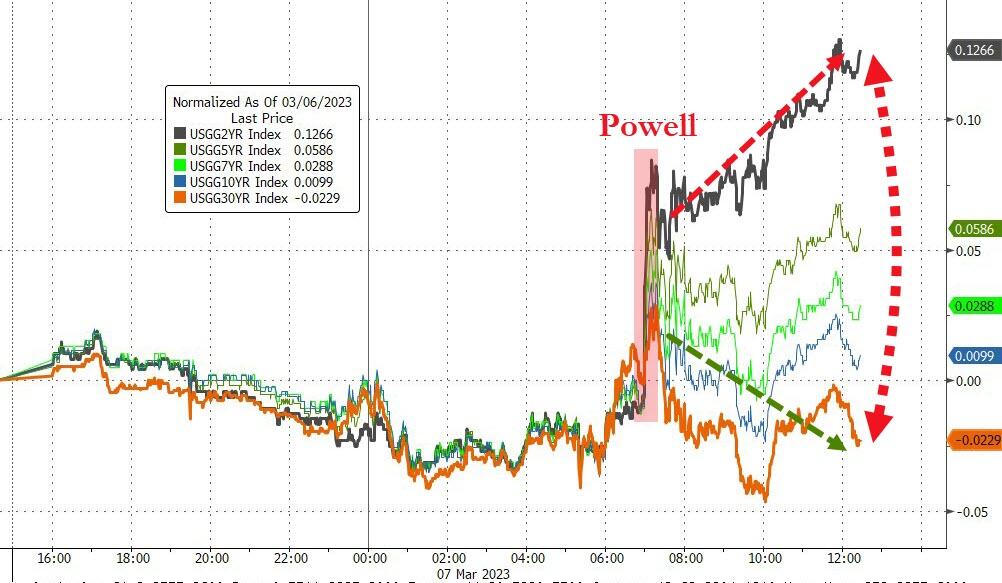
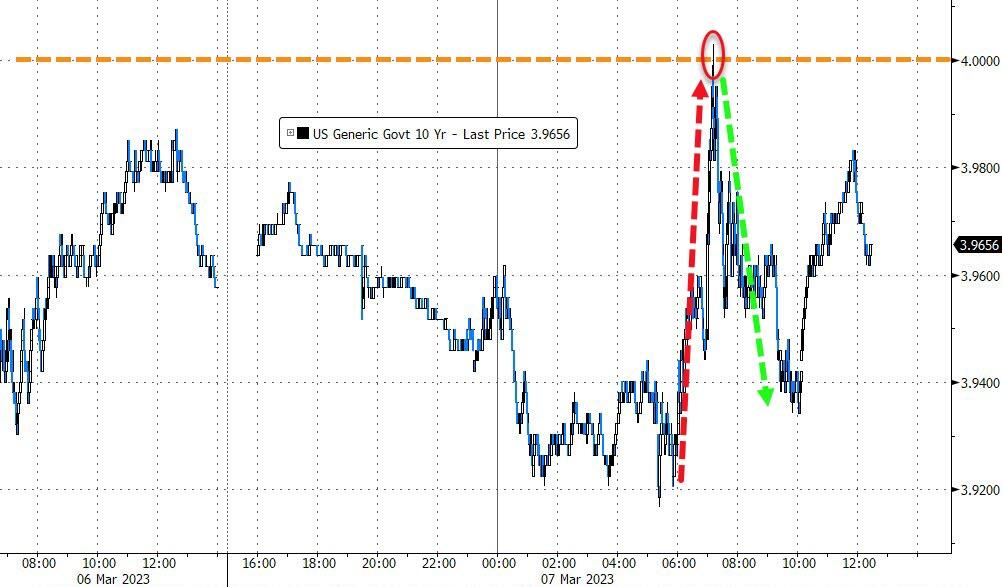
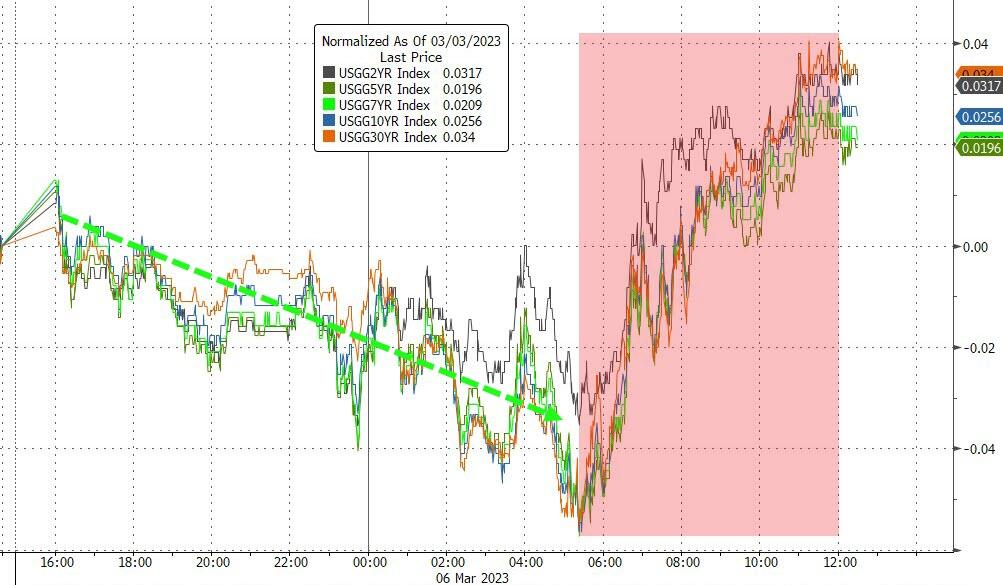
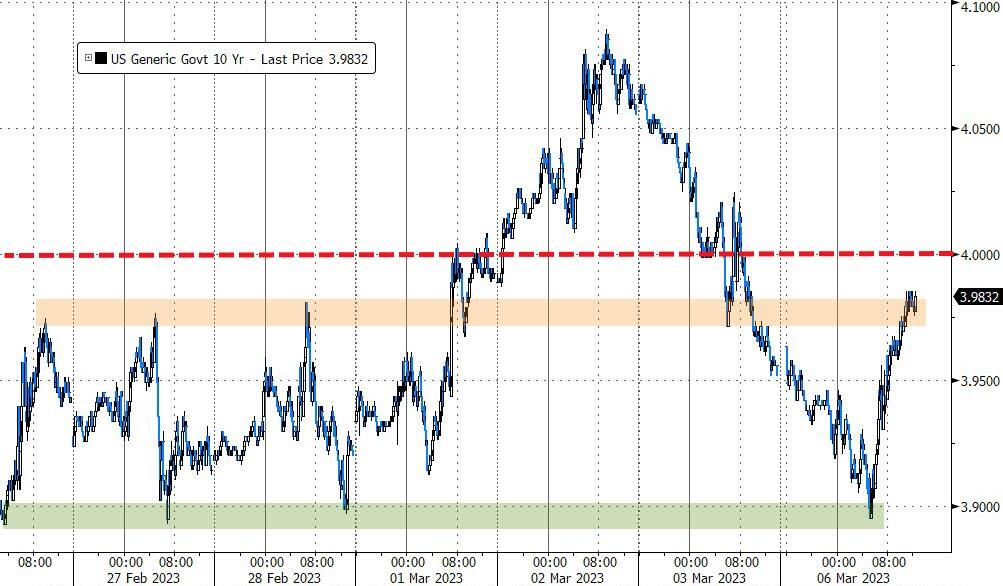
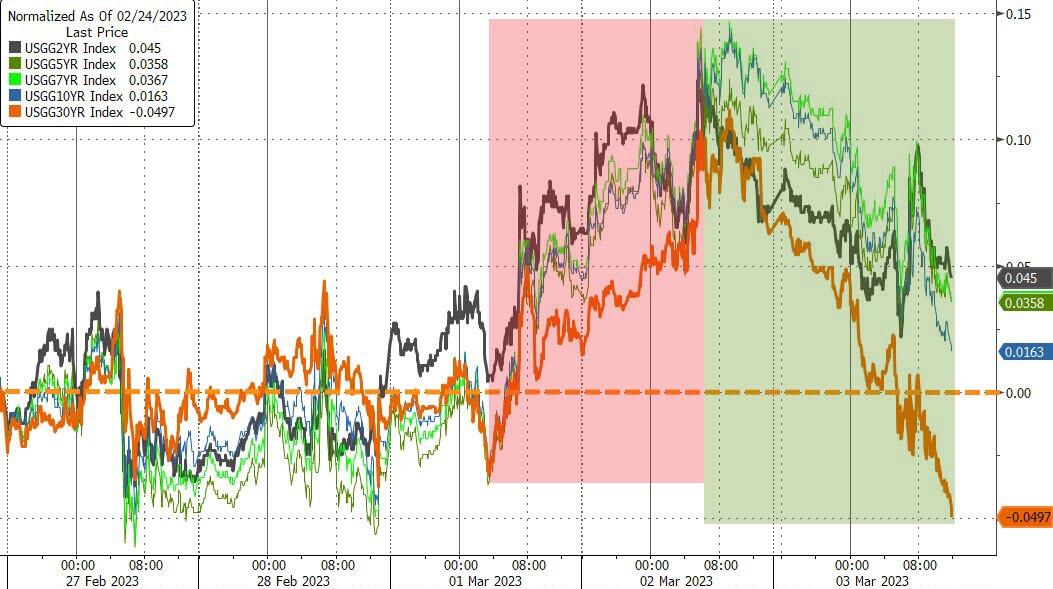
Bond yields dipped early on but headed higher late in the session, with the 10-year breaching its 4% level to the upside, but again it was not able to close above it.
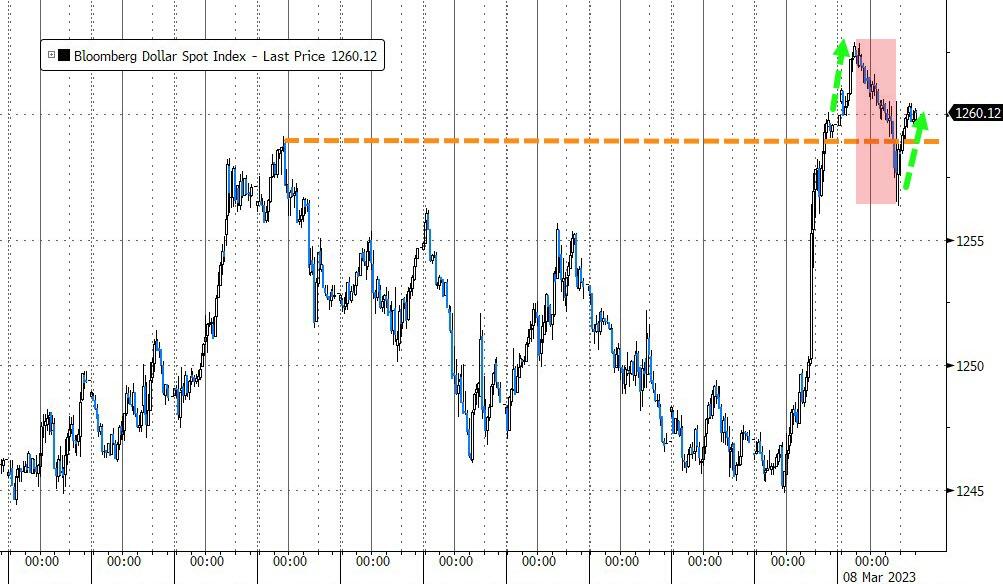
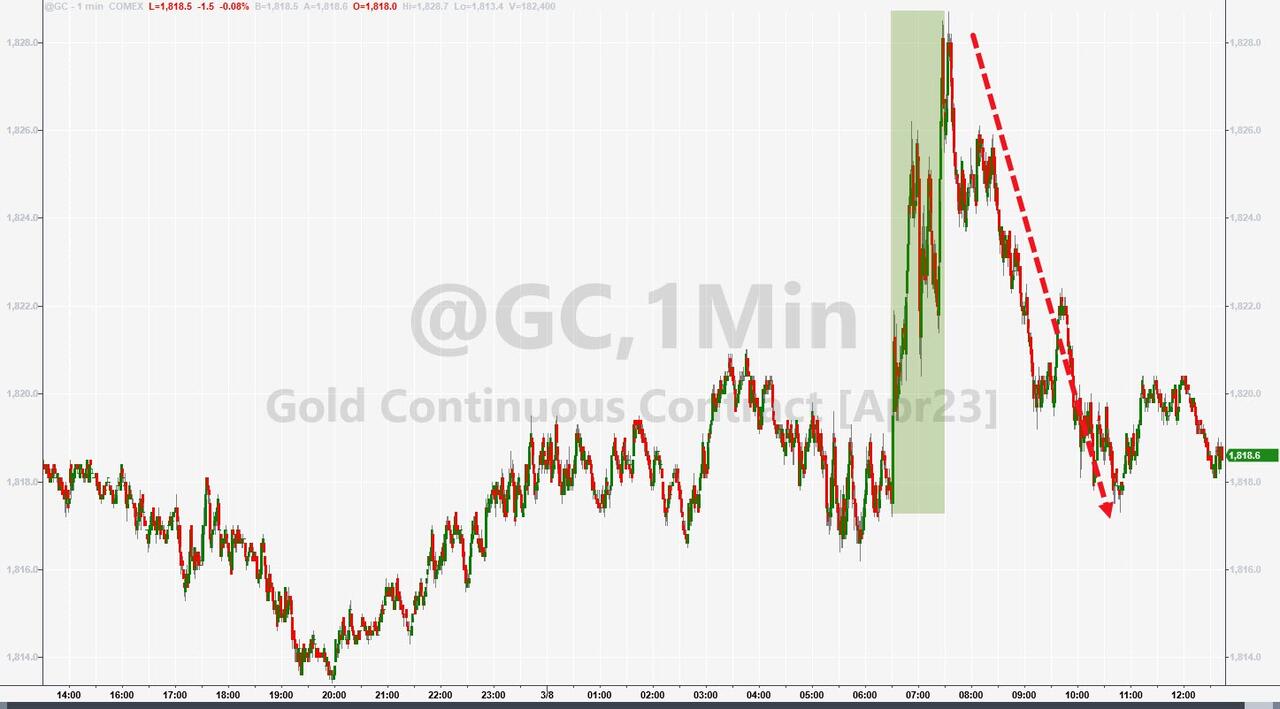
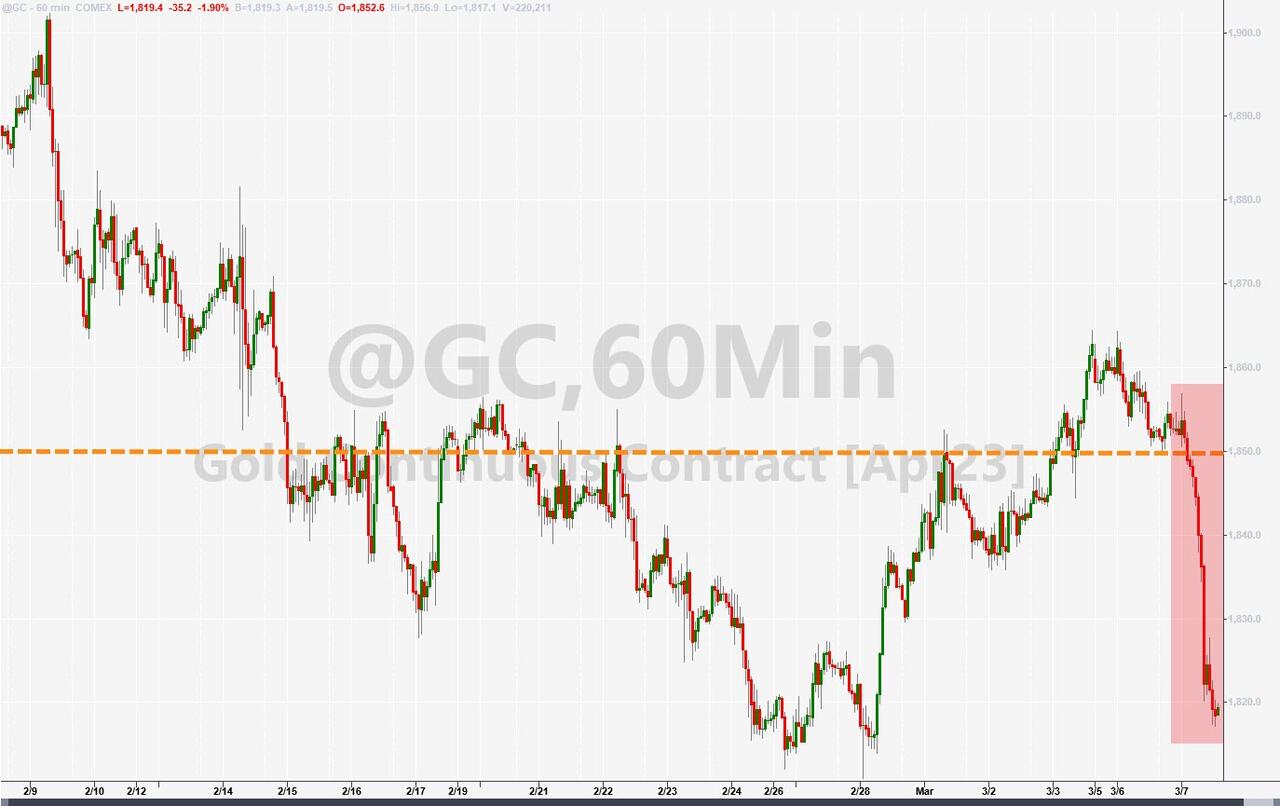
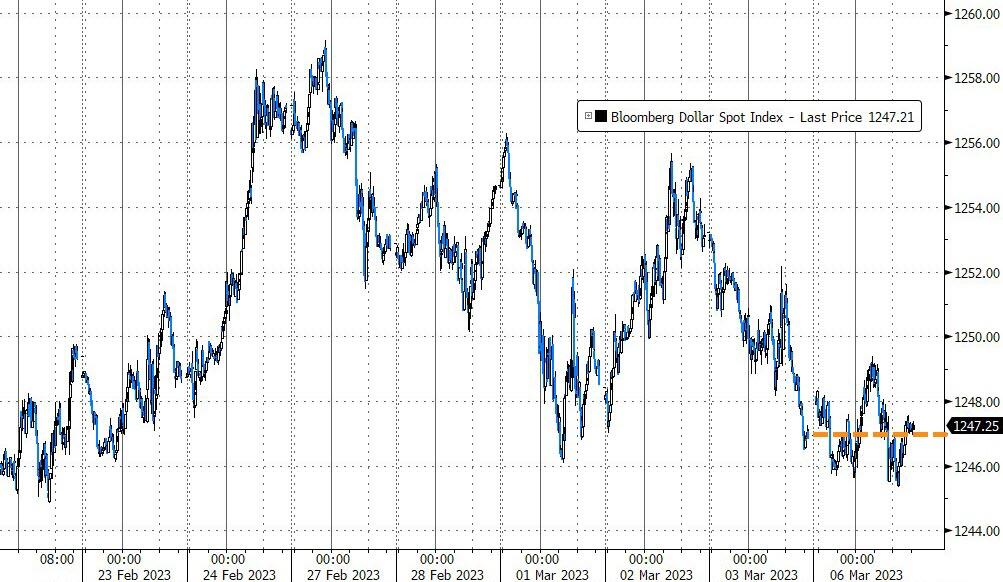
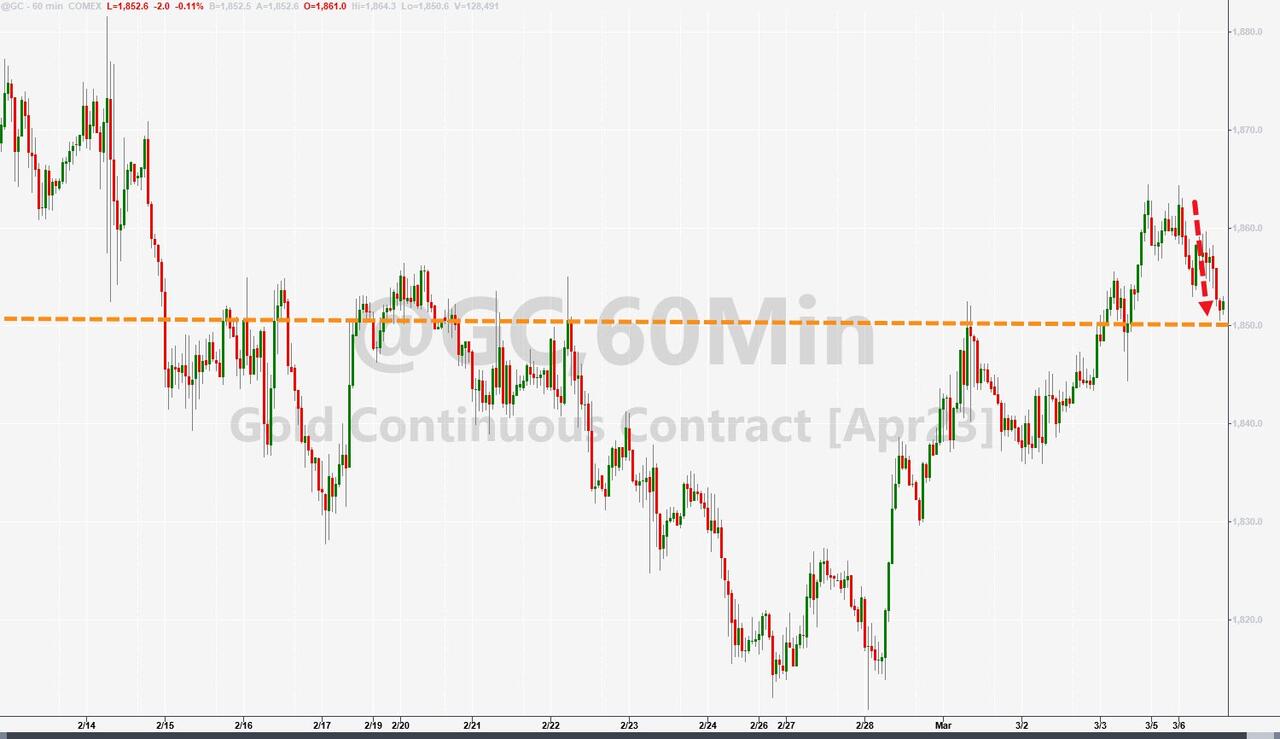
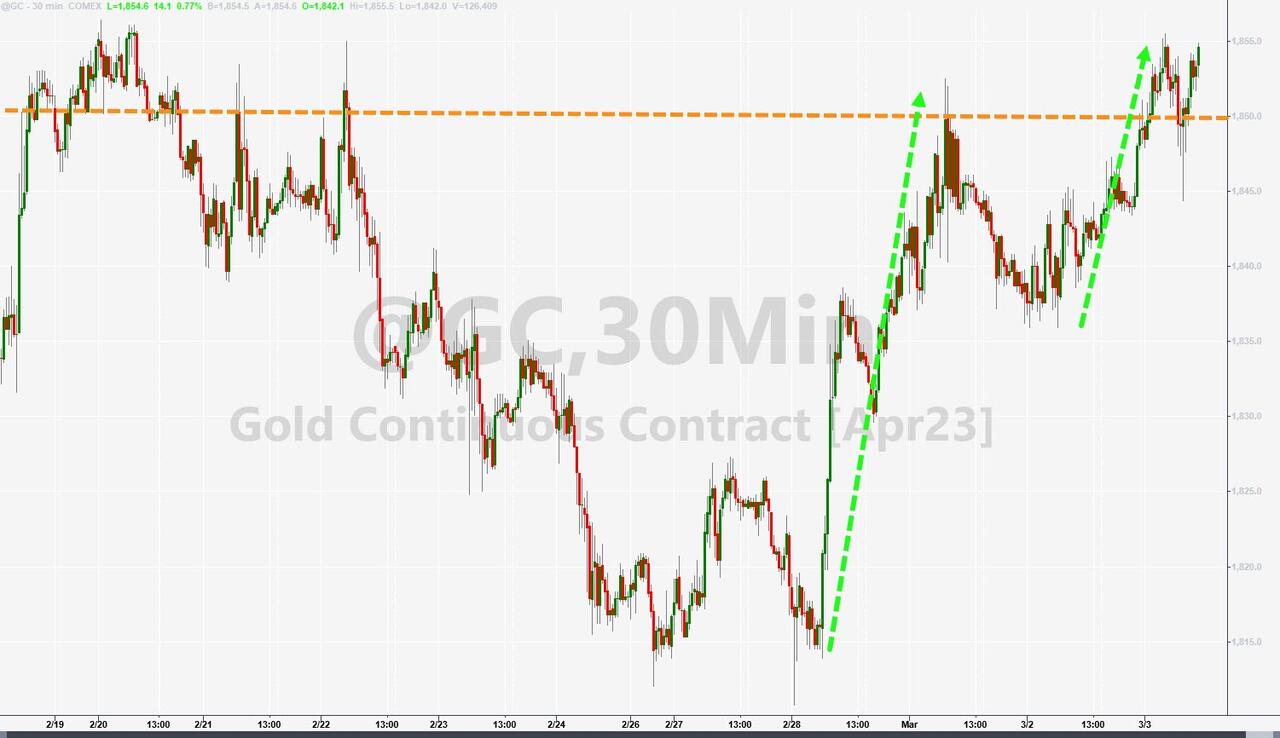
The US Dollar bobbed and weaved and closed unchanged, as did Gold, with the precious metal surrendering its early gains.
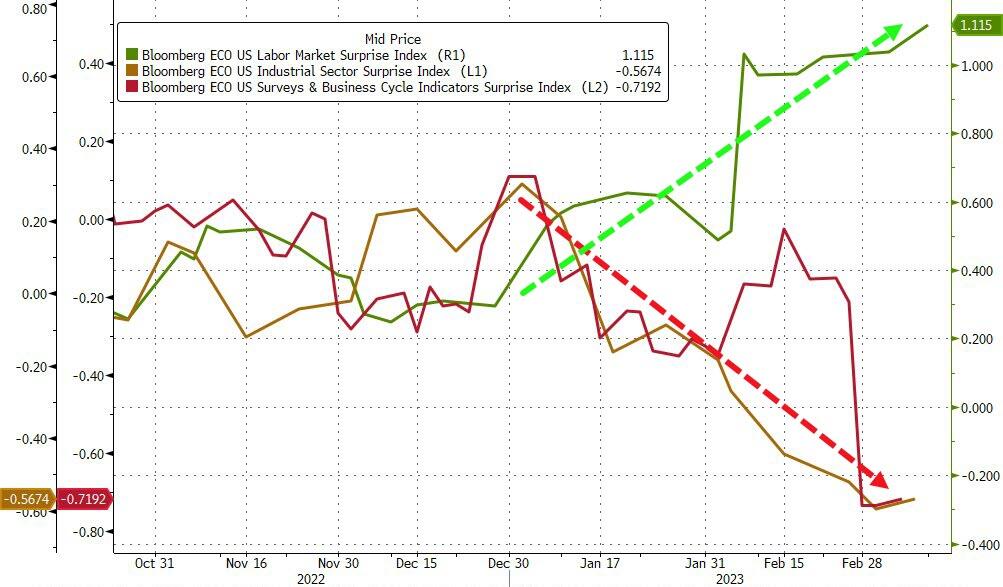
While Industrial and Survey data have been plunging, the Labor Market has shown surprising strength, which makes me wonder if some of these numbers are out of whack?
Will that alligator snout snap shut one of these sessions?
Hmm…
Read More