No Load Fund/ETF Tracker updated through 10/21/2010

Ulli Uncategorized Contact

My latest No Load Fund/ETF Tracker has been posted at:

http://www.successful-investment.com/newsletter-archive.php

Selloffs and rallies were the name of the game, but the major indexes closed up slightly.

Our Trend Tracking Index (TTI) for domestic funds/ETFs moved above its trend line (red) by +6.52% (last week +6.62%) and remains in bullish mode.

The international index has broken above its long-term trend line by +7.21% (last week +7.56%). A new Buy signal was triggered effective 9/7/10. If you decided to participate, be sure to use my recommended sell stop discipline.

[Click on charts to enlarge]

For more details, and the latest market commentary, as well as the updated No Load Fund/ETF Tracker StatSheet, please see the above link.

Good Rebounding Effort

Ulli Uncategorized Contact


Whenever you witness a sharp selloff, such as we’ve seen on Tuesday, the question pops up as to whether this will be the beginning of a trend reversal or simply a shock reaction to a certain event.

Judging by yesterday’s rebound, it appears to be the latter, as the major indexes found some footing and almost wiped out the previous day’s losses.

Just as a combination of events provoked Tuesday’s downturn, a different combination caused Wednesday’s rebound. Some of the contributors to the upswing were strong earnings, a falling dollar and rising commodity prices.

The Fed’s Beige Book report still stuck to its mantra of “modest growth.” I suppose that as long as any words are uttered that contain “growth,” the market will take that as a positive and rally on, no matter whether it seems to the rest of us that way or not.

The dollar took a big dive and fell 1.6% against the euro, while gold and crude oil rallied. The futures are pointing to a stronger opening as am writing this in Germany at 2 am PST.

Shocking The Markets

Ulli Uncategorized Contact


A variety of news events combined forces yesterday to pull the major indexes off their lofty levels.

In the mortgage fiasco arena, Bank of America was sued by a consortium of investment firms and the New York Fed to force the bank to buy back mortgage backed securities worth some $47 billion.

This will be just the beginning in an effort to ascertain whether proper due diligence was applied when packaging these securities. Allegations have surfaced that a large percentage of mortgages in those pools should have never been included due to lack of “quality.”
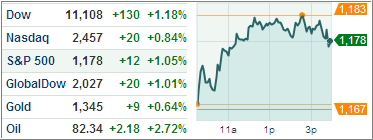
Next, China applied some shock and awe on global markets by announcing that it had raised interest rates. That took the starch out of any remaining upward momentum as the dollar rallied, gold and oil dropped, stocks headed south and bonds rallied higher.

China’s interest hike should not have come as a surprise as their real estate market is in a gigantic bubble, with the economy growing too fast and inflation pressures continuing. Higher rates are now a concern to global economies as Chinese economic growth may now be less as had been anticipated, which in turn will affect global demand for raw materials, construction and equipment.

The good news about the day was that the major averages closed off the lows by a decent margin. Futures indicate that the opening on Wednesday may be to the upside. Time will tell if yesterday was only a one-day correction or if this spells the end of the current uptrend.

The chart above is courtesy of MarketWatch. Please note that the readings for gold, oil and the Global Dow are incorrect due to me accessing this chart at a delayed time from Europe.

Rising On Expectations

Ulli Uncategorized Contact


Heavyweights Apple and IBM beat Street estimates yesterday, but it wasn’t good enough to appease the investing community. Subsequently, shares sank in afterhours trading, although the market had risen prior because of high expectations.

To see how nutty market reaction can be, you only need to look at how Citigroup was cheered, even though their real earnings were dismal but artificially propped up due to reduction of its loan-loss-reserves.

In regards to the overall market, the major indexes managed to look beyond chip and oil service stocks and moved higher into the close. Lending a little support was a jump in the Homebuilders Housing Index; however, it’s far from being in the range that would be considered optimistic.

Crude oil and gold rose, interest rates were lower, and the dollar eased against major currencies. On the agenda today, will be more earnings along with reports on housing starts and building permits.

As I am writing this in Germany at 3 am PST, the futures are slightly negative for the Dow and S&P; 500, but sharply lower by about 1% for the Nasdaq.

Daredevil Central Bankers

Ulli Uncategorized Contact

Have bankers’ attitudes changed? MarketWatch seems to think so as featured in “Get ready for daredevil central bankers:”

We have come to expect our central bankers and policy experts to be gray, predictable and eager to take away the punch bowl once the party gets going.

So when they showed up at the Boston Fed conference on monetary policy in sandals talking about bungee jumping, you know that something profoundly different is happening.

For decades, Fed officials and economists have been saying that monetary policy could be governed by a few rules. Plug in a few numbers and you get a good sense about where interest rates should be.

But the Fed already has lowered short-term interest rates to zero and the economy looks like it is sliding back into a ditch.

The grim outlook is causing central bankers to shed their typical conservatism in favor of a new daredevil, “try-anything” approach — asset purchases, giving the blessing to higher rates of inflation for the short-term at least. These were some of the ideas discussed in earnest.

We are about to watch our central bankers wing it like kids at the X Games. One wonders how this is going to go over on Wall Street.

Fed Chairman Ben Bernanke made headlines at the conference by giving another speech preparing the markets for a resumption of the central bank’s purchases of bonds with new money. The goal is to try to bring down long-term interest rates and get liquidity flowing in the economy.

There was plenty of skepticism at the conference about whether it will work. Certainty was in short supply during the two days of talks. Read more on the reaction to Bernanke’s remarks.

Greg Mankiw, a Harvard professor and former top economist for President George W. Bush, summed it up nicely by saying at the start of the conference that macro-economics is in “a state of disarray.”

Any economist that says he or she definitely knows the answer to the current economic ills should be avoided, he added.

Any economist that says he or she knows the answer to the current economic ills should be avoided, one economist suggests.

Only a few years ago, macro-economists were patting themselves on the back, saying that they had achieved an era of “Great Moderation” and that wild swings in economic activity were a thing of the past. This has been replaced by humility and the Great Recession.

With Fed officials casting about for ideas, previously unthinkable ideas were floated. Most jarring to the casual observer is the notion that the Fed accept a higher inflation rate for some period of time.

Other ideas that were mentioned include the possibility of taxing bank reserves or even paper currency; having the Fed target the yield on the 10-year note; or having the Treasury Department issue only bills and no bonds. There also was some wishful thinking that Congress could declare a payroll-tax holiday.

Other economists appealed for calm. Drastically altering policy as a result of the crisis “seems to me to be lacking in logic,” said Bennett McCallum, an economics professor at Carnegie Mellon University.

That’s one ugly forecast

Earlier this year, Bernanke and other Fed officials talked about the economy in terms of a relay race. The economy was growing at a moderate pace fueled by government spending and a buildup in inventories. At some point, there would be a handoff to consumer and business spending. But the economy is no longer running; it seems to crawling around the track.

Fed officials will release an updated economic forecast in mid-November, but their early previews are quite pessimistic.

Bernanke talked about growth picking up in 2011, but only to about a 2.5% annualized rate, which is not enough to make much of a dent in the 9.6% unemployment rate.

Low inflation should also persist, leaving the economy one shock away from deflation.

The Fed cut rates to zero in December 2009. Given this forecast, it is no longer unthinkable to think zero rates could last up to four years.

Just the fact that further quantitative easing is being considered confirms that the economy has simply run out of steam and is in crawl mode, which it accelerated into just about after the expiration of the various stimulus programs.

I have repeatedly mentioned throughout the year that there never was a recovery to begin with, but only a stimulus induced “mirage” of an economic rebound.

Central bankers are shifting now into Evel-Knievel-mode willing to try anything to keep this economy from sliding further. Using untried and unproven means as a last resort to right the sinking ship smells of desperation and may have unknown and unintended consequences.

Eventually, Wall Street will get the idea that smoke and mirrors are not a sound basis for a euphoric, extended rally; when that moment occurs, you better have your exit strategy in place as market direction can change in a hurry.

Out For The Day

Ulli Uncategorized Contact

Some family obligations in Hamburg, Germany, along with a few unexpected visitors, will be filling up my Sunday; so there will be no post today. The regular update of this blog will resume early on Monday.