Major Market ETFs Slide On Services Data; JJG Surges, EWP Sinks

Ulli Market Commentary Contact

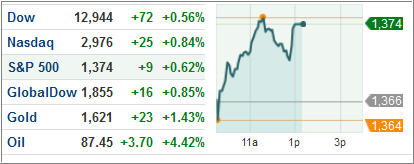
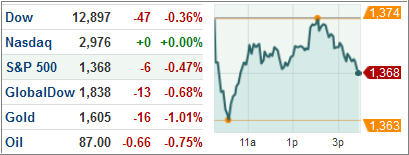
[Chart courtesy of MarketWatch.com]

The Major Market ETFs ended mostly lower Thursday as weak US services data combined with a coordinated interest rate cut by the European Central Bank and the People’s Bank of China subdued investors’ risk appetite.

Yields on US Treasuries dropped as investors rushed to buy safe-haven assets amid indications that the global recovery is faltering.

The Dow Jones Industrial Average (DJIA) slipped 0.4 percent, after sinking as much as 92 points during the today’s session. All but seven components within the 30-component index closed lower after the Institute for Supply Management’s non-manufacturing index dropped to 52.1 in June from 53.7 in May, the least since Jan. 2010 and still in the expansionary region.

Read More

07-05-2012

Ulli Newsletter Archives Contact

The ETF/No Load Fund Tracker—Monthly Review—June 30, 2012

Month End Rally Lift US Stocks; European Union Inches Closer To “More” Union

US stocks rallied the last business day of June with the S&P 500 locking in 2.5 percent on the day to post its biggest single session gain since December after European leaders agreed on a series of short-term measures to ease the region’s ongoing debt crisis.

However, I have to caution you that not much real headway has been made, and any progress can only be counted once paymaster Germany clearly agrees to what has become much news headline propaganda.

EU politicians consented hope to form a single banking regulator to supervise the region’s banks and approved the use of the lifeboat funds to recapitalize stricken banks directly, a move aimed to lessen the debt burden of Spain and cap the spiraling borrowing costs of Madrid and Rome.

Markets got a further boost on the news that the European Investment Bank will receive €120 billion to be used for enhancing the bank’s lending capacity to businesses in an effort to create jobs. Where exactly the funds will be coming from has not been established, and the widely touted ESM mechanism has not been ratified by all countries (and is stuck in German courts for review).

US recovery remains questionable as economic indicators fluctuated for the month with some displaying downright bearish tendencies. As a result, the Federal Reserve revised the real GDP growth for 2012 downwards to range from 1.9 percent to 2.4 percent against the previously projected range of 2.4 percent to 2.9 percent. The unemployment rate was revised upwards and is expected to range between 8.0 and 8.2 percent from the previously forecasted 7.8 – 8.0 percent.

None of this so far has discouraged the markets from heading towards the highs made early in the year based on the faulty assumption that the Fed will always be there to bail out Wall Street. In my opinion, a major concerted stimulus effort by the various central banks is a distinct possibility, but ONLY after the markets have tanked, and 401ks have turned into 201ks, and not while the major indexes are flirting with the highs of the year.
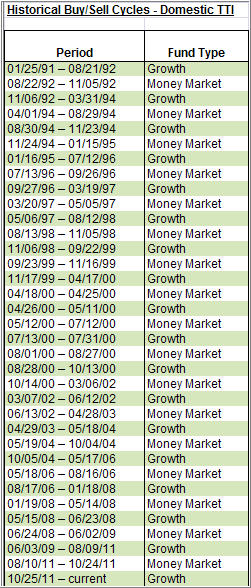
After our International Sell signal on 5/15/12, that arena has sank deeper into bear market territory but recovered somewhat towards the end of the month. Domestically, our Trend Tracking Index (TTI) remains on the bullish side of the trend line, as the chart below shows:
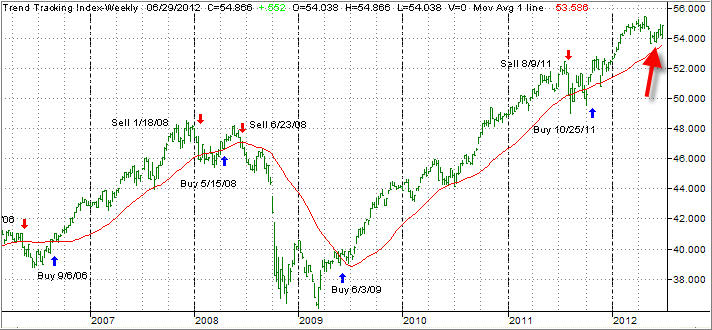
Market weakness early in the month (big red arrow) pulled this indicator within 1% of generating a ‘Sell,’ but continued hope about a resolution for the European debt crisis, kept support alive, and we remain in ‘Buy’ mode.

During the volatile times we got stopped out of the VTI position, but are still holding on to DVY, which has been a steady influence for those accounts exposed to it. The European debacle will end up badly, I am sure, but that does not make it an imminent event.

The timing is the great unknown, and I would have expected the end of the road to be reached much sooner than it appears. Nevertheless, my preferences in these uncertain times is to be predominantly exposed to those bond ETFs, which are the main stay of the ETF Model Portfolio #2 (BND, TIP, BSV).

My reasoning is that if the situation in Europe worsens, which it will, the flight to safety will be on and that will bode well for US bond related issues. Things can unravel in a hurry, as the global slowdown continues, and US equities will not decouple from the rest of the world as we are all tied at the hip—economically speaking.

Even for our bond positions, I have sell stops in place to be executed should unexpected market turmoil occur. It’s important to be prepared for all eventualities, as best as I can evaluate them.

7 ETF Model Portfolios You Can Use – Updated through 7/3/2012

Ulli Model ETF Portfolios Contact

Up, up and away was the theme, as the S&P 500 added some 4% since last week’s model portfolio report. Of course, from a fundamental point of view nothing has changed but misplaced euphoria about an alleged solution coming out of the EU summit. That was supported by quarter ending window dressing while short covering provided the ammunition for this rally.

As I have said before, nothing of substance, other than revving up the propaganda news machine, gave hope to the idea that Europe might solve its debt woes. Again, with all the news coming out, there is only one party that can make a difference and that is paymaster Germany. So, watch out for any announcements of substance.

Given that, I believe that this current rally will hit a brick wall possibly triggered by a poor jobs report on Friday.

In the meantime, here’s the latest model portfolio update:

Read More

Equities Rally As Auto Sales, Factory Orders Robust In June; GDXJ Shines, VIXY Tumbles

Ulli Market Commentary Contact

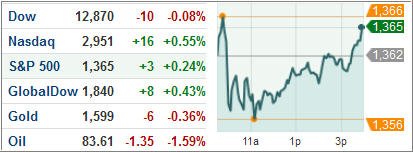
[Chart courtesy of MarketWatch.com]

Strong factory orders and an increase in auto sales for May pushed US stocks higher Tuesday after closing mixed Monday as investors breathed easy on concerns that the economy is faltering.

Of course, as has been the case lately, bad economic news is simply ignored while decent reports provide the fuel for a rally. Go figure. Stocks of commodities and energy firms rallied as prices of materials and commodities surged for the day.

US Treasuries sank risk sentiment improved following a government report that showed US factory orders rose for the first time in three months in May. The number came in at 0.7 percent against a consensus estimate of 0.1 percent.

Read More

Dow Slips As Manufacturing Disappoints; Worst NYSE Volume In Over A Decade

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

The S&P 500 and NASDAQ ended shrugged off early weakness to close modestly higher, while the Dow Industrials closed slightly lower Monday after ISM data showed US manufacturing shrank unexpectedly in June for the first time since July 2009.

Volume was the worst on the NYSE in a decade and, even when compared to other July 1st Holiday weeks, it was the lowest on record, which does not show much conviction.

The yields on benchmark 10-year and 30-year US Treasuries dropped the most in nearly a month after the Institute of Supply Management said its PMI index slipped to 49.7 in June from 53.5 in May, indicating a slowdown in manufacturing activities.

Read More

ETFs/Mutual Funds On The Cutline – Updated Through 6/29/2012

Ulli ETFs on the Cutline Contact

Below are the latest ETF Cutline reports, which show how far above or below their respective long-term trend lines (39 week SMA) my currently tracked ETFs/MFs are positioned.

The first report covers the ETF Master List from Thursday’s StatSheet and includes 398 ETFs, of which currently 249 (last week 202) of them are hovering in bullish territory.

The second report includes only High Volume ETFs. To clarify, High Volume (HV) ETFs are defined as those with an average daily volume of $10 million or higher.

These ETFs are generated from my selected list of some 93 that I use in my advisor practice. It cuts out the “noise,” which simply means it eliminates those ETFs that I would never buy because of their volume limitations. 37 ETFs (last week 34) have managed to remain in bullish territory after the recent market volatility.

The third report covers Mutual Funds on the Cutline. There are currently 632 (last week 494) above the line and 229 below it out of the 861 that I follow.

Take a look:

1. ETF Master Cutline Report

2. ETF High Volume Cutline Report

3. MF Cutline Report

In case you are not familiar with some of the terminology used in the reports, please read the Glossary of Terms.