ETF/No Load Fund Tracker Newsletter For April 25, 2014

Ulli ETF Tracker Contact

ETF/No Load Fund Tracker StatSheet

————————————————————-

THE LINK TO OUR CURRENT ETF/MUTUAL FUND STATSHEET IS:

https://theetfbully.com/2014/04/weekly-statsheet-for-the-etfno-load-fund-tracker-newsletter-updated-through-04242014/

————————————————————

Market Commentary

Friday, April 25, 2014

POSITIVE CORPORATE EARNINGS, INTERNATIONAL TENSIONS LEAVE MARKETS MIXED FOR THE WEEK
Fri pic

[Chart courtesy of MarketWatch.com]

1. Moving The Markets

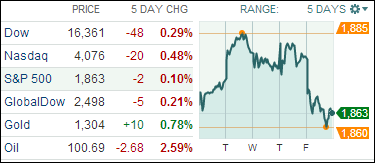
Stocks were little changed on the week, as the Ukrainian-Russian conflict came back into focus lover the past few days, ending a six-day winning streak.  After the slight pullback in early April, the S&P 500 is up about 1% on the year and just 1% below record highs as markets continue to receive support from some improving economic data points and better-than-expected earnings reports.

The major indexes ended the week lower as the above 5-day chart shows.

We saw a mix of positive and negative reports on the economic front this week. Durable goods orders rose strongly, up 2.6% in March from February.  This was better than expected and the strongest increase in four months. US consumer confidence rose in the period ended April 20th to its second-strongest level since January 2008. However, new home sales fell sharply, down 14.5% in March from February to the slowest pace since last July, and the number of US initial jobless claims rose by 24,000 to a seasonally adjusted 329,000.

It will be an extremely full upcoming week for economic data and the busiest for first-quarter earnings season.  Highlights include the initial reading of first-quarter gross domestic product (GDP) and an interest rate decision by the Federal Reserve (including potential further tapering of bond purchases).  If corporate earnings trends continue to top analyst estimates, as they have over the past two weeks, markets should react positively and continue trending upwards.

Our 10 ETFs in the Spotlight offered a mixed picture with 2 of them making new highs today while 8 of them are remaining in the green YTD.
Read More

Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 04/24/2014

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, April 24, 2014

Table of Content082312

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: BUY — since 10/25/2011

TTI

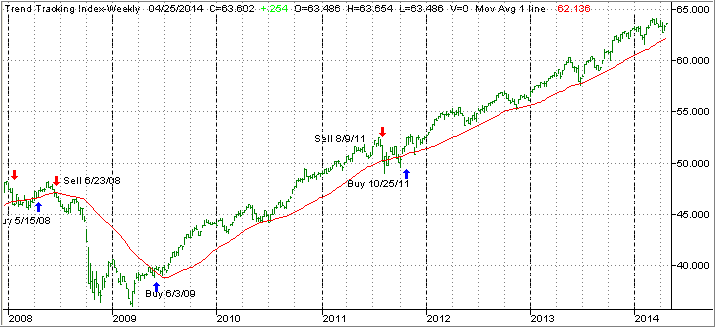
Our main directional indicator, the Domestic Trend Tracking Index (TTI), broke through its long-term trend line generating a Sell for this area effective 8/9/2011. Over the recent past, we’ve seen the TTI hovering slightly below and above this dividing line between bullish and bearish territory. The clear break to the upside occurred on 10/24/11 and, effective 10/25/11, a new Buy signal for domestic equities went into effect.

As of today, our TTI (green line in above chart) is positioned above its long term trend line (red) by +2.37%.

To avoid a potential whip-saw, a Sell signal to move out of all domestic equity positions will be generated once we have clearly pierced the red line to the downside. Be sure to tune in for the latest updates.

Read More

Equities Pitter Patter Higher, But Remain Timid Over Russia & Ukraine

Ulli Market Commentary Contact

Thur pic

[Chart courtesy of MarketWatch.com]

1. Moving The Markets

U.S. stocks inched higher as Apple’s (AAPL) strong earnings report proved to be not enough to ease fears over an escalating tension between Russia and Ukraine. The major indexes inched higher as the chart above shows.

Notable gainers today were Aetna (AET), who reported its first quarter EPS results of $1.98, beating the consensus estimate of $1.52; Caterpillar Inc (CAT) whose shares rose 1.8% to $105.28 after the company reported better-than-expected earnings and raised its full-year profit outlook; and Zimmer Holdings Inc (ZMH) who announced that it has agreed to buy Biomet Inc (LVBHAB) in a deal valued at about $13.35 billion to broaden its portfolio of products that treat bone and joint-related disorders. Zimmer’s stock surged 11.5% to $101.97.

The struggles in Ukraine continue to impact markets here in the U.S. Much of the volatility today was reportedly driven by comments from Russian Defense Minister Sergei Shoigu, who said Russia started military drills near the border with Ukraine. It was also reported that Ukrainian forces killed up to five pro-Moscow rebels as they closed in on the separatists’ military stronghold in the east. All those geopolitical concerns warrant instability and higher commodity prices; both of those are things Wall Street hates.

Our 10 ETFs in the Spotlight were mixed as 9 of them are remaining on the plus side YTD.

Read More

Stocks Pull Back, But Corporate Earnings Continue To Deliver

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving The Markets

The stock market pulled back today after a solid six consecutive days of gains. The S&P 500 dropped 0.24%, the Dow finished down 0.07% and the Nasdaq led the pack dropping 0.83% on the day.

Apple (AAPL) captured headlines today after reporting that it sold 43.7 million iPhones in Q1, which was much larger than the 38 million predicted by Wall Street analysts. The company also approved a roughly 8% increase in its quarterly dividend to $3.29 per share while it also approved another $30 billion in share buybacks and authorized a 7-for-1 stock split. Shares gained 7% in after hours trading after having lost 6.95% during the regular trading day.

Corporate Q1 earnings announcements remain at the forefront of investor gaze. Today, Delta Air Lines (DAL) reported its first quarter results. The company announced an EPS of $0.33, beating the consensus estimate of $0.29. Manpower (MAN) reported its first quarter results. The company announced an EPS of $0.86, beating the consensus estimate of $0.68. Other notable earnings announcements for Q1 that topped analyst expectations came from Thermo Fisher Scientific (TMO), General Dynamics (GD), Procter & Gamble (PG), Boeing (BA), Facebook (FB) and Qualcomm (QCOM)

In commodities, Gold gained 0.30%, trading at $1,285 an ounce and Oil dropped 0.24%, trading at $101.51 a barrel.

Our 10 ETFs in the Spotlight zigzagged with the indexes with 9 of them remaining on the plus side YTD.

Read More

Keep Those Corporate Earnings Reports Coming!!

Ulli Market Commentary Contact

Tue pic

[Chart courtesy of MarketWatch.com]

1. Moving The Markets

U.S. stock markets continued their rally today, driven largely by positive corporate news and earnings announcements. The major indexes all gained as the chart above shows. The health-care sector led the eight of ten S&P 500 sectors that finished higher on the day. Driving health-care gains was the news from the pharmaceutical space that British drug giant GlaxoSmithKline (GSK) will sell its cancer-products business to Novartis AG (NVS) for $14.5 billion. At the same time, Novartis AG said separately that it will sell its animal health division to Eli Lilly (LLY) for $5.4 billion. Shares of Glaxo and Novartis gained 5% and 1.2% respectively, while Eli Lilly shares gained 1.5%

Netflix (NFLX) was back in the news today as it announced that it will raise prices in the near future on its streaming services, but for new customers only. Existing subscribers will hold on to the current monthly rate. The news from Netflix that really grabbed investors’ attention though was their reporting net profit of 86 cents per share during the first quarter, which topped both internal and Wall Street forecasts. The company also reached 48 million subscribers, which was much faster growth than anticipated.

Align Technology (ALGN), Apple (AAPL), Biogen Idec (BIIB) and Facebook (FB) are among companies due to report quarterly earnings Wednesday. Let’s keep the good corporate earnings news rolling in! Also, economic data scheduled for Wednesday will include new-home sales for March and the Mortgage Bankers’ Association’s weekly mortgage applications index.

Our 10 ETFs in the Spotlight headed higher with 1 of them making a new high today while 9 remain on the plus side YTD.

Read More

Corporate Earnings Continue To Impress Investors

Ulli Market Review Contact

Mon pic

[Chart courtesy of MarketWatch.com]

1. Moving The Markets

Another big week of corporate earnings announcements is underway and markets reacted well to positive earnings announcements from companies such as Haliburton (HAL), Netflix (NFLX) and Hasbro (HAS). The S&P 500 gained 0.4% ending the day exactly where we started on April 1st. The continued climb of the markets over the past week is refreshing, needless to say, after a volatile start to the month, when a sell-off in high-flying technology and biotechnology stocks pushed the overall market lower.

Close to a third of the companies in the S&P 500 are scheduled to report Q1 earnings this week, which will give us a better picture on the state of the economy moving forward. McDonald’s (MCD), Delta Air Lines (DEL) and Apple (AAPL) are among the 159 companies in the S&P 500 that are scheduled to report. Together, the companies represent about a third of the value of the index. Of the 87 companies in the S&P 500 that had reported results through Monday morning, 62.1 percent have topped earnings expectations, according to Thomson Reuters data.

Nokia (NOK) said on Monday it expects the sale of its handset business to Microsoft (MSFT) to be finalized on April 25, as it had received all the required regulatory approvals. The closure of the 5.4 billion euro ($7.5 billion) deal, which was agreed in September, had been delayed due to pending approvals, but earlier this month the companies won a crucial nod from Chinese regulators.

Our 10 ETFs in the Spotlight gained with 2 of them making new highs today while 9 are in the green YTD.

Read More