ETF/No Load Fund Tracker Newsletter For April 10, 2015

Ulli ETF Tracker Contact

ETF/No Load Fund Tracker StatSheet

————————————————————-

THE LINK TO OUR CURRENT ETF/MUTUAL FUND STATSHEET IS:

https://theetfbully.com/2015/04/weekly-statsheet-for-the-etfno-load-fund-tracker-newsletter-updated-through-04092015/

————————————————————

Market Commentary

Friday, April 10, 2015

STOCKS END THE WEEK ON A SOLID NOTE; BLACKSTONE DEAL GOES THROUGH
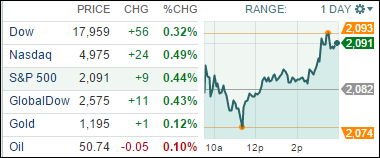
Fri pic

[Chart courtesy of MarketWatch.com]
  1. Moving the Markets

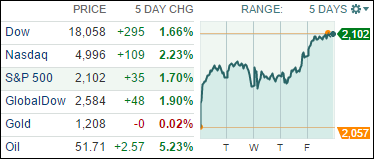
Stocks rose for a third straight day Friday as the Dow rallied nearly 100 points and jumped back above the 18,000 level to close out with a weekly gain. The entire buzz today was about the General Electric deal.

As you may remember from earlier this week, there was speculation that Blackstone Group (BX) and Wells Fargo (WFC) were going to make an offer on a substantial real estate portfolio of General Electric (GE). Well, today General Electric announced it is selling the bulk of its GE Capital Banking business in its latest attempt to “simplify” its manufacturing business and concentrate on the best-performing segments.

The $23 billion deal, covering both GE Capital Banking and Real Estate, marks the largest real estate transaction since the 2007 recession. Separately, Blackstone Property Partners agreed to a $2 billion, all-cash acquisition of Excel Trust (EXL), a San Diego-based real estate investment trust that primarily targets shopping centers and grocery store-anchored investments.

In corporate earnings, the outlook for 2015 remains bleak, as Q1 earnings for the S&P 500 index are still expected to come in 4.7% lower and forecast Q2 earnings are expected to be 2.1% lower, according to Bloomberg.

For the week, we saw few major economic reports. The most impactful update was the March unemployment report, which was actually released on last Friday. U.S. economic data has seemed to weaken in recent months; however, economists expect the slowdown to allegedly prove temporary, as economic growth is expected to come in between 2.5% to 3% for the year, a stronger pace than most developed economies around the world.

All of our 10 ETFs in the Spotlight gained with healthcare (XLV) taking the lead today with +0.86%, while the financials (IYF) ended unchanged. 2 of the 10 made new highs for the year as you can see section 2.
Read More

Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 04/09/2015

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, April 9, 2015

TOC021915

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: BUY — since 10/22/2014

TTI

Our main directional indicator, the Domestic Trend Tracking Index (TTI), broke through its long-term trend line generating a “Sell” for this arena effective 10/14/2014, which was followed by a violent break back above the line on 10/22/14 generating a new “Buy.” It was a classic whipsaw signal, and you can read more on my blog as to the events as they were unfolding.

As of today, our TTI (green line in above chart) is positioned above its long term trend line (red) by +3.30% keeping us in the market with our established positions.

Read More

Indexes Make Late Day Swing To Close Positive

Ulli Market Commentary Contact

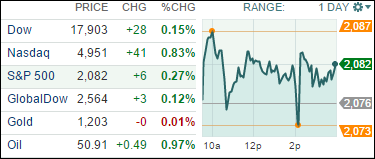
Thur pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Gains were led mostly by energy stocks as oil prices rebounded slightly after Wednesday’s steep decline. U.S. benchmark crude rose 0.7% to $50.84 a barrel after plunging 6% the previous day on a larger-than-expected inventory build-up.

In tech, shares of Altera (ALTR) rose and Intel (INTC) fell on reports that Intel has ended talks to buy the semiconductor company. In auto news, we heard today that General Motors (GM) is halting production of the Chevy Volt extended-range electric car, because they need to clear out an unsold backlog. Volt sales the first quarter this year are just less than half what they were a year earlier.

The sale of these electric toys, of course, relates directly to the price of gas. With gas prices low so far this year, there has been a large financial disincentive to buy alternative-power vehicles.

And finally, a fun bit of buzz on the street today is that private equity firm Blackstone Group and Wells Fargo are close to a deal buy a real-estate portfolio valued at a whopping $30 billion from General Electric (GE). This has not been confirmed as of yet, but if the transaction did go through, it would be one of the largest real estate deals since pre-financial crisis of 2007.

7 of our 10 ETFs in the Spotlight inched higher while 3 of them dropped. Leading the charge to the upside was Healthcare (XLV) with +0.75%, while SPLV ruled the downside with a slight loss of -0.24%.

Read More

Stocks Respond Well To Fed Minutes; Shell To Buy BG

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Stocks ended up higher after the release of minutes from the Fed’s meeting in March showed policymakers were divided on the timing of the first interest rate hike. The report remained consistent, however, with Fed policymakers’ forecasts that indicate the first hike in rates since 2006 is unlikely to take place before September.

Energy stocks and the oil were in focus today as oil prices slid on a build-up in U.S. inventories and a $70 billion oil merger was announced. U.S. benchmark crude fell 6% to close at $50.42 a barrel in New York after the Energy Information Administration reported a larger-than-expected increase in oil stockpiles last week. Chevron (CVX) dropped 1.7% and ExxonMobil (XOM) fell 2%.

In one of the largest corporate deals of the year, Royal Dutch Shell (RDS.A) agreed to buy Britain’s BG Group (BRGYY) for $70 billion in cash and stock. It is set to be one of the largest corporate deals of the year.

And earnings season began today with Alcoa (AA) reporting after the closing bell. Earnings beat estimates, but revenue was a shortfall. Wall Street analysts remain bearish on Q1 earnings and expect profits for S&P 500 companies to contract 2.8%.

8 of our 10 ETFs in the Spotlight manage to close up in this non-directional day. Consumer Discretionaries (XLY) was the winner with a gain of +0.94%, which was closely followed by Healthcare (XLV) with +0.84%. On the downside, DVY led with a modest loss of -0.19%.

Read More

Post Holiday Hype Fades On Tuesday

Ulli Market Commentary Contact

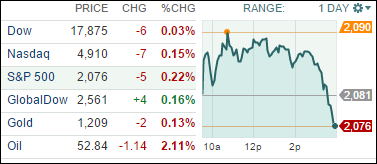
Tue pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Stocks withered early gains and fell sharply in the last hour of trading, as the major indexes closed lower, breaking a two-day bunny hop winning streak. April has always been a volatile month, as investors are typically on edge in advance of Q1 earnings season. First-quarter earnings season kicks off Wednesday as Alcoa (AA) will be the first to report.

Speaking of the earnings calendar, here’s a quick snapshot of 5 of the Top 10 largest companies earnings release dates. April 14 – Google (GOOG), Wells Fargo &Co (WFC) and Johnson & Johnson (JNJ); April 17 – General Electric (GE); April 22 – Facebook (FB).

Which sectors actually performed today? Health care and energy were the only sectors of the 10 S&P 500 sectors to hold onto gains, while utilities led the market lower as the sector dropped more than 1%.

In M&A news, shares of FedEx (FDX) rose 2.7% after announcing it was expanding into Europe in a $4.8 billion deal to buy Dutch rival TNT Express. The all-cash deal will allow the package delivery company to better compete overseas with United Parcel Service.

9 of our 10 ETFs in the Spotlight slipped and headed south with only healthcare (XLV) bucking the trend by closing up +0.24%.

Read More

Wall Street Bounces Back From Easter Holiday

Ulli Market Commentary Contact

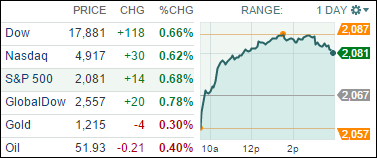
Mon pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Wall Street seemed to ignore the lackluster jobs report that was released Friday when the stock market was closed for Easter. Since bad news is good news these days, equities pushed sharply higher today amid a growing sense that the Fed will push back its first rate hike to sometime in Q3 or later. Gains were led by the energy and utilities sectors as oil prices jumped $2.55.

Tesla (TSLA) took investors for a ride today following news late Friday that the company’s vehicle shipments for Q1 were 5% better than expected. Investors still remain bearish on the stock for the most part due to the fact that it remains below its 200-day moving average.

Those bullish on USD currency may not be so happy today. The dollar fell a fourth day, which is the longest streak of depreciation in nine months. The beloved greenback slipped as a Fed measure of conditions in the labor market slumped.

In more positive economic news, small-business hiring is picking up and could account for most new jobs this year as large companies pull back amid global economic troubles. The NFIB says small businesses added an average 0.18 workers per firm in March, which is one of the best readings in the last decade. Also, small-business credit providers are opening wider. According to Biz2Credit, big banks approved 21.5% of small-business loan requests in February, a post-recession high.

All of our 10 ETFs in the Spotlight edged up with IOO being the front runner sporting a gain of +1.20%, while healthcare (XLV) was lagging the group with +0.15%.

Read More