Ending April On A Sour Note

Ulli Market Commentary Contact

Thur pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

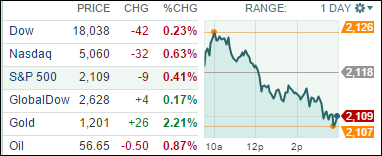
Stocks ended the month on a weak note as traders reacted to new information, ranging from a suddenly weakening dollar vs. the euro and strong incoming U.S. data that raised fresh fears about interest rate hikes.

We heard some solid economic data released today, including a better-than-expected reading on manufacturing in the Chicago region and a bigger-than-expected rise in employment costs, which could be signaling that the first-quarter soft patch may, in fact, be transitory, as the Federal Reserve suggested in its policy statement yesterday. Stocks fell for a second straight day after Wednesday’s news of anemic GDP growth of 0.2% in the first quarter, and the Fed’s announcement that showed policymakers are still grappling with when to begin raising interest rates but indicated they could hike rates at any meeting.

In earnings news, ExxonMobil (XOM) earnings fell 46% on lower oil prices and revenue. On the flipside, the company announced a 9.5% dividend increase. The stock fell 0.6%. Time Warner Cable (TWX) saw its largest increase in video subscribers in six years. But earnings missed Street expectations, and TWC dropped 1.5%.

Also in earnings, shares of LinkedIn (LNKD) plunged 27% in extended trading on a weak corporate earnings outlook. The leading online professional network said it expects adjusted per-share earnings of 28 cents on sales of $670 million to $675 million for the current quarter, which ends June 30.

As for the international realm, shares fell in Asia on Thursday following the U.S. economic news, and Japan also reported that its industrial output fell 0.3% in March from the month before and 1.2% from the previous year.

All of our 10 ETFs in the Spotlight again slipped and closed in the red. Leading the group to the downside was this year’s winner, healthcare (XLV), with a loss of 1.40%, while consumer staples (XLP) held up best by giving back only 0.33%.
Read More

A True “Hump Day” Of Ups And Downs

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

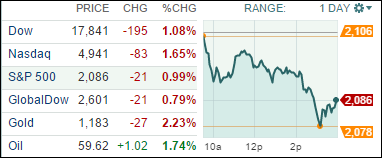
Stocks closed lower as investors digested weaker-than-expected economic growth and the latest statement from the Federal Reserve that indicated policymakers were still grappling with when to begin raising interest rates.

Continuing with Fed matters, The Federal Reserve gave a slight signal today that it could raise interest rates at any meeting, opening the door to the possibility of a mid-summer rate hike.

In M&A news, it was all about Salesforce.com (CRM) today. Shares of the company soared on a report that the cloud computing giant has hired sell-side advisors to field takeover inquiries. The stock gained 12% on the day to close at $74.65. Salesforce.com has a market value of nearly $50 billion, said S&P Capital IQ analyst Scott Kessler. Which would make it the largest ever takeover of a software company.

The only major earnings news was that of Fiat Chrysler Automobiles (FCAU). The company reported earnings per share of 52 cents compared with a loss of $1.55 per share for the same period a year ago. Those results accelerated way beyond analysts’ expectations of just 7 cents per share, however, the stock dropped 5.5% on the day.

All of our 10 ETFs in the Spotlight slumped and closed down. Holding up the best was IYF with a scant 0.10% loss, while SPLV gave back 1.00%.

Read More

Stocks Close Mostly Higher On Mixed Economic Data; Twitter Falters

Ulli Market Commentary Contact

Tue pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Stocks cut early losses and closed mostly higher as the Federal Reserve began a two-day policy meeting to discuss the economy and interest rates. The Nasdaq was the only major index that closed in the red, down 0.10%.

As you know, interest rates have been at the forefront of news headlines for the past year. However, it still seems that most economists believe there’s virtually no chance the Fed will hike rates Wednesday after stating last month that an April move was unlikely. But investors will be scouring the central bank’s post-meeting statement though for clues as to whether a June liftoff remains a possibility.

In earnings news, you may want to “tweet” this bit of info. Shares of the social media company Twitter (TWTR) plunged after it reported first-quarter revenue far below Wall Street estimates and issued a disappointing outlook for the current quarter and for the rest of the year. Twitter reported a loss of $162 million, or 25 cents a share, compared with a loss of $132 million, or 23 cents a share a year ago. Shares of Twitter fell as much as 20% and closed down 18% to $42.27.

In other economic news, stocks fell early in the trading session after it was reported that consumer confidence unexpectedly tumbled in April. We also saw disappointing job growth numbers and continued. We did hear some positive news though on the housing front. Home prices climbed at a faster pace in February than the previous month, driven by higher sales and a limited supply of available houses.

In a reversal from yesterday, 9 of our 10 ETFs in the Spotlight headed higher with DVY showing the best gain at 0.58%, while XLY ended up in the red with a loss of 0.35%.

Read More

Pulling Back From Record Highs

Ulli Market Commentary Contact

Mon pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

A pause sure was in order after last week’s push into record territory. The major indexes pulled back as the chart above shows.

The focus remains on earnings with the name of the game being to beat the already lowered expectations. After the closing bell, Apple managed to beat handsomely by posting an amazing 33% rise in earnings, which pushed the stock up by 1.82% in after-hours trading.

Things might heat up by mid-weak, as a preliminary reading on the first quarter GDP will be released on Wednesday, while the Fed will also deliver the latest policy statement after its two-day meeting.

Only 1 of our 10 ETFs in the Spotlight managed to buck the downward trend, namely IOO, which gained 0.39% on the day. Leading the downside was XLV, which gave back 1.81% as bio stocks in general were pulled off their lofty levels.

Read More

ETFs/Mutual Funds On The Cutline – Updated Through 04/24/2015

Ulli ETFs on the Cutline Contact

Below are the latest ETF Cutline reports, which show how far above or below their respective long-term trend lines (39 week SMA) my currently tracked ETFs/MFs are positioned.

The first report covers the ETF Master List from Thursday’s StatSheet and includes 410 ETFs, of which currently 331 (last week 309) are hovering in bullish territory.

The second report includes only High Volume ETFs. To clarify, High Volume (HV) ETFs are defined as those with an average daily volume of $10 million or higher.

These ETFs are generated from my selected list of some 97 that I use in my advisor practice. It cuts out the “noise,” which simply means it eliminates those ETFs that I would never buy because of their volume limitations. 60 ETFs (last week 53) have managed to remain in bullish territory after the recent market volatility.

The third report covers Mutual Funds on the Cutline. There are currently 589 (last week 492) above the line and 231 below it out of the 820 that I follow.

Take a look:

1. ETF Master Cutline Report

2. ETF High Volume Cutline Report

3. MF Cutline Report

In case you are not familiar with some of the terminology used in the reports, please read the Glossary of Terms.

If you missed the original post about the Cutline approach, you can read it here.

One Man’s Opinion: Can US Investors Shift To US Treasuries To De-Risk Portfolios?

Ulli Market Review Contact

92835431In the first quarter, US markets witnessed lots of worries such as a stronger dollar, weak oil prices and the timing of an interest-rate liftoff; but that seems to fade away as the economy enters into the second quarter, said Kate Nixon, CIO at Northern Trust Wealth Management.

The energy markets have stabilized along with the greenback and despite the dramatic decrease in earnings expectations, companies have managed to top the lower expectations bar. Fundamentally, macroeconomic factors have started to look okay as some of the issues witnessed in the first-quarter were transitory in nature, including the effect of weather. The economy is likely to add a few basis points as the weather turns brighter and sunnier, she noted.

As the markets hit record highs, it’d be difficult to eke out much from the indexes and investors need to focus on individual stocks. Asked to comment, Kate said the base case for Fed’s rate lift-off remains September and rate hikes would be in very small steps, taking a non-linear path. Monetary policy will stay very accommodative, which will provide tailwind to risky assets, she observed.

Read More