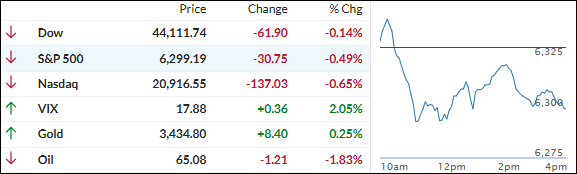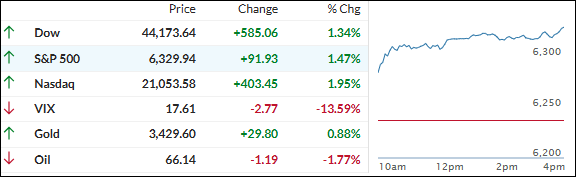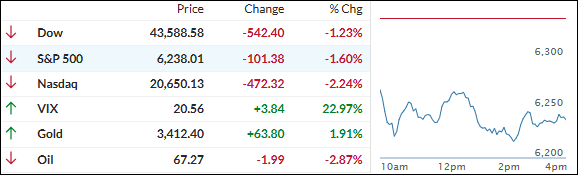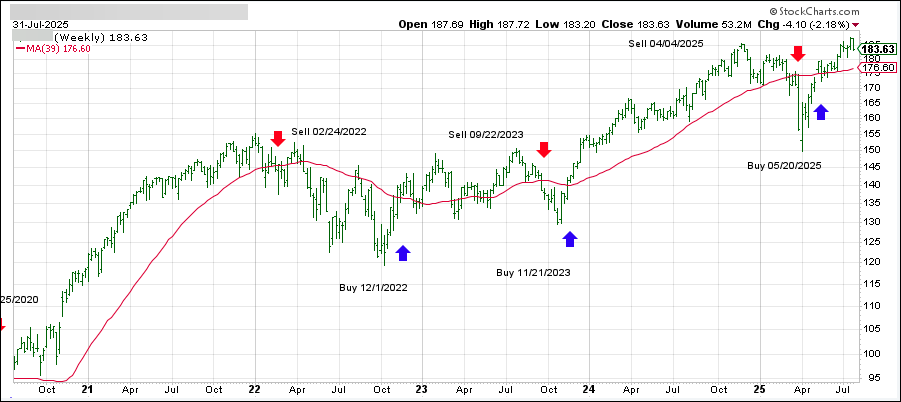
[Chart courtesy of MarketWatch.com]
- Moving the market
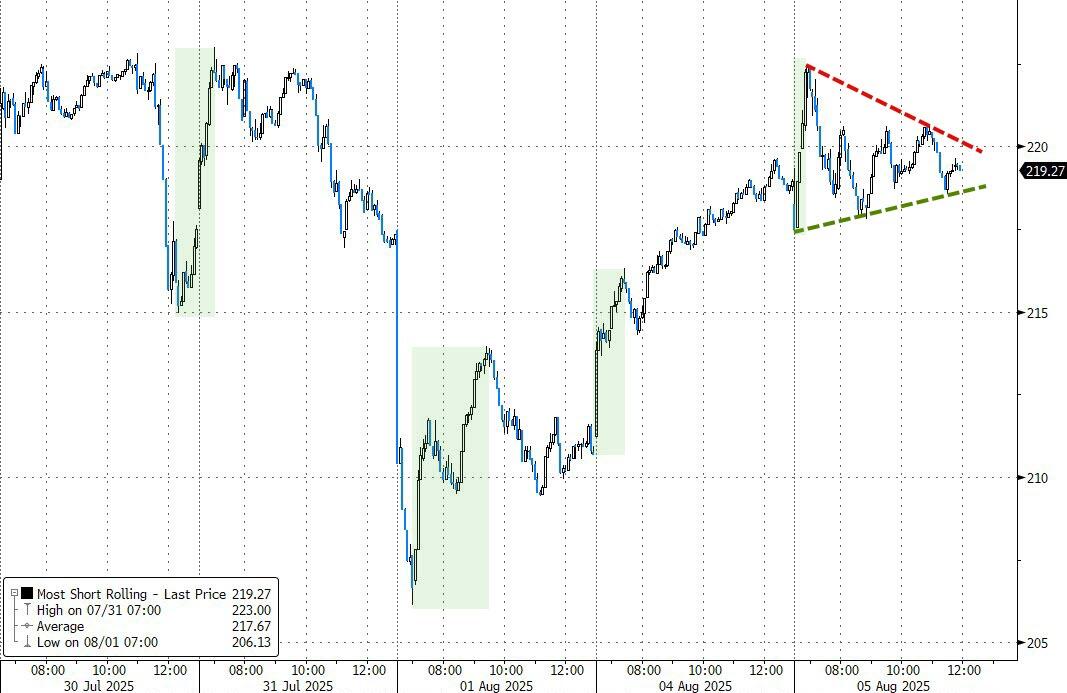
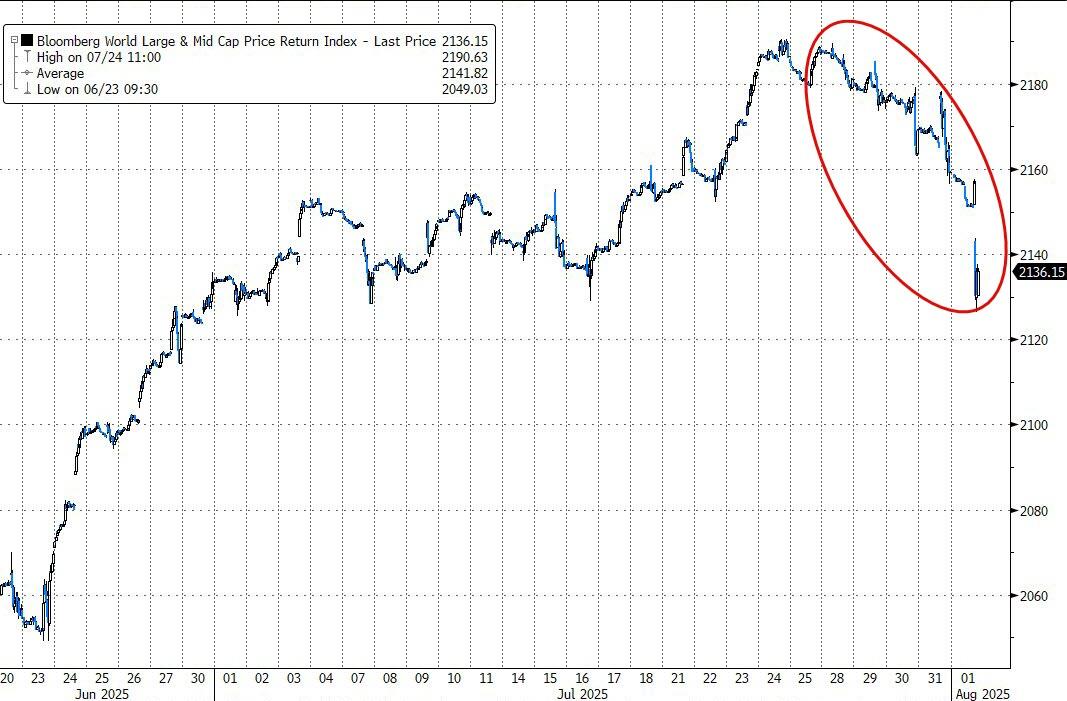
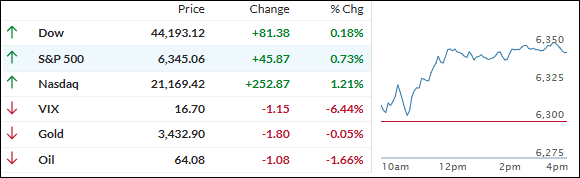
The S&P 500 started the day on a high note, as traders sifted through a new round of earnings after Wall Street’s rough patch yesterday.
Apple was the big story, jumping 3% after news broke that it’s boosting its investment in U.S. manufacturing by another $100 billion, bringing its total stateside spending to a whopping $600 billion over the next four years.
There were other bright spots, too—McDonald’s rose 2% after serving up strong second-quarter numbers and notching its fastest same-store sales growth in nearly two years.
But it wasn’t all sunshine: Snap’s stock plummeted 20% after a minor revenue miss, and Advanced Micro Devices took a 5% hit after falling shy of earnings estimates.
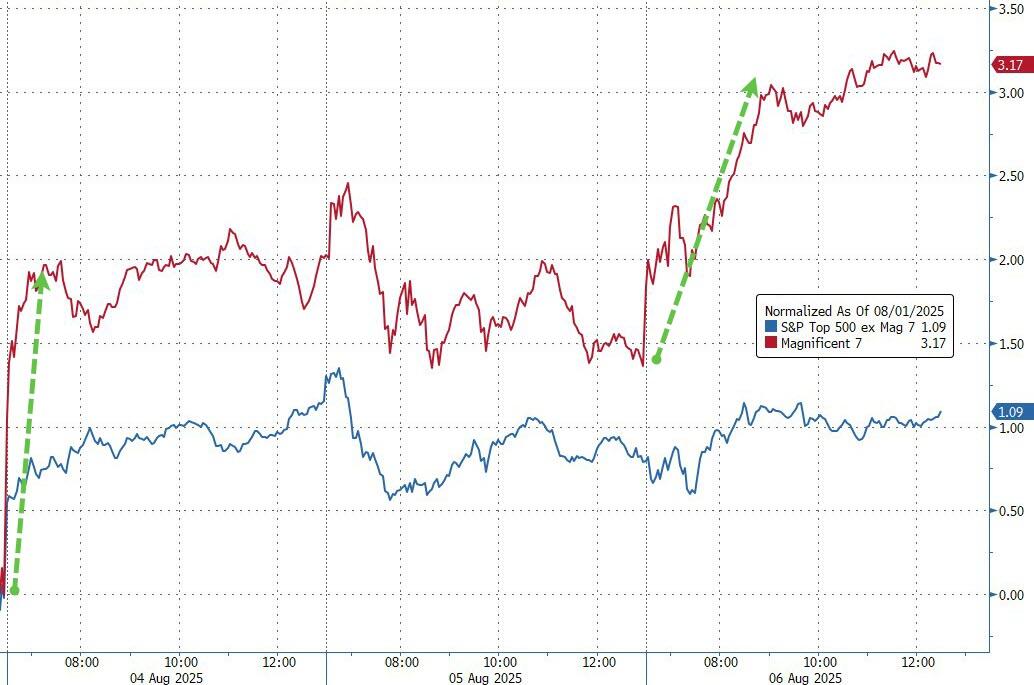
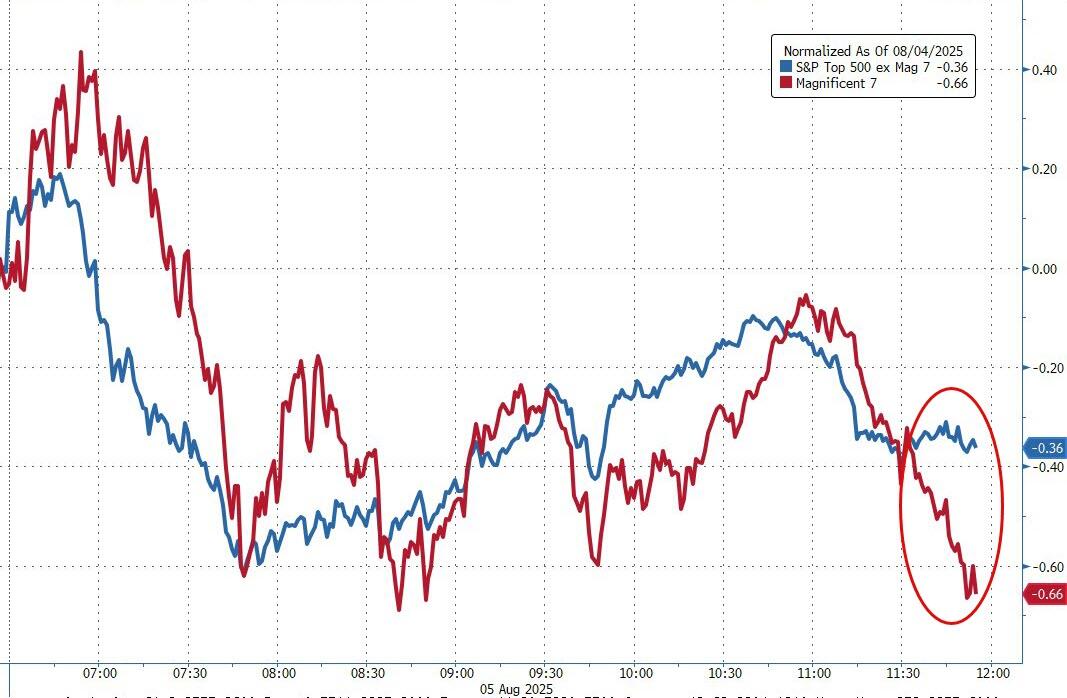
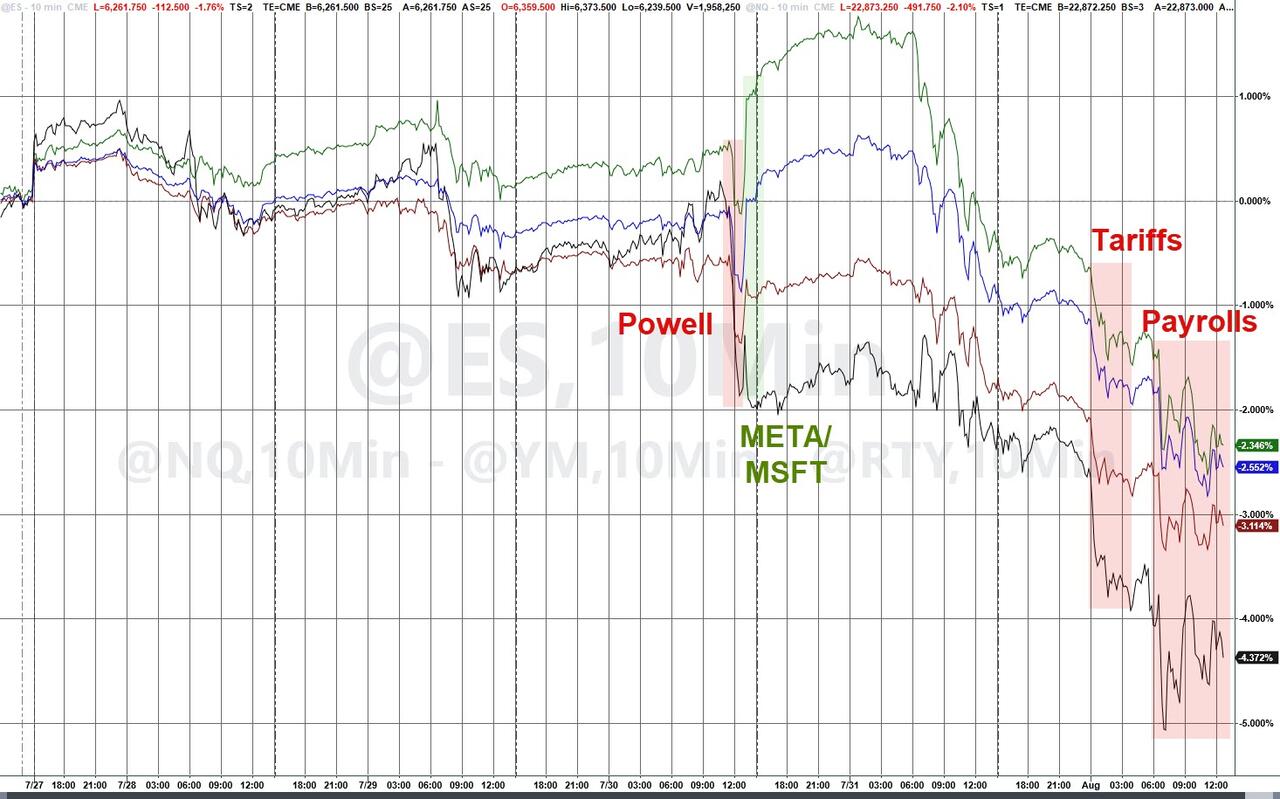
By the closing bell, the Nasdaq came out on top, outperforming the other major indexes, while Small Caps ended in the red. That meant the Mag 7 stocks easily eclipsed the rest of the S&P 500 for today’s session.
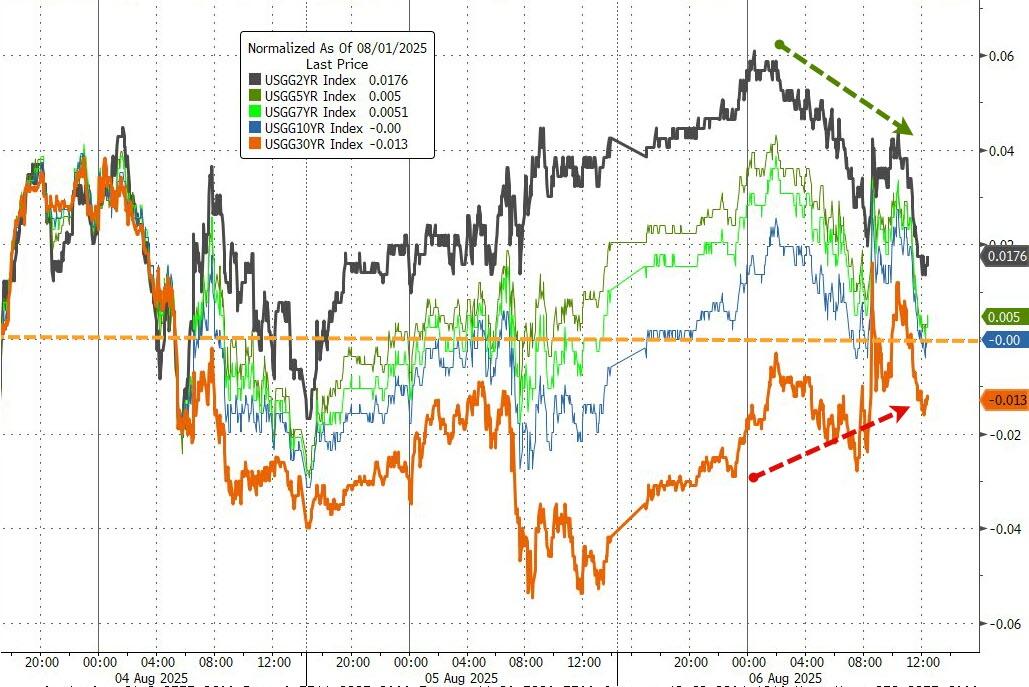
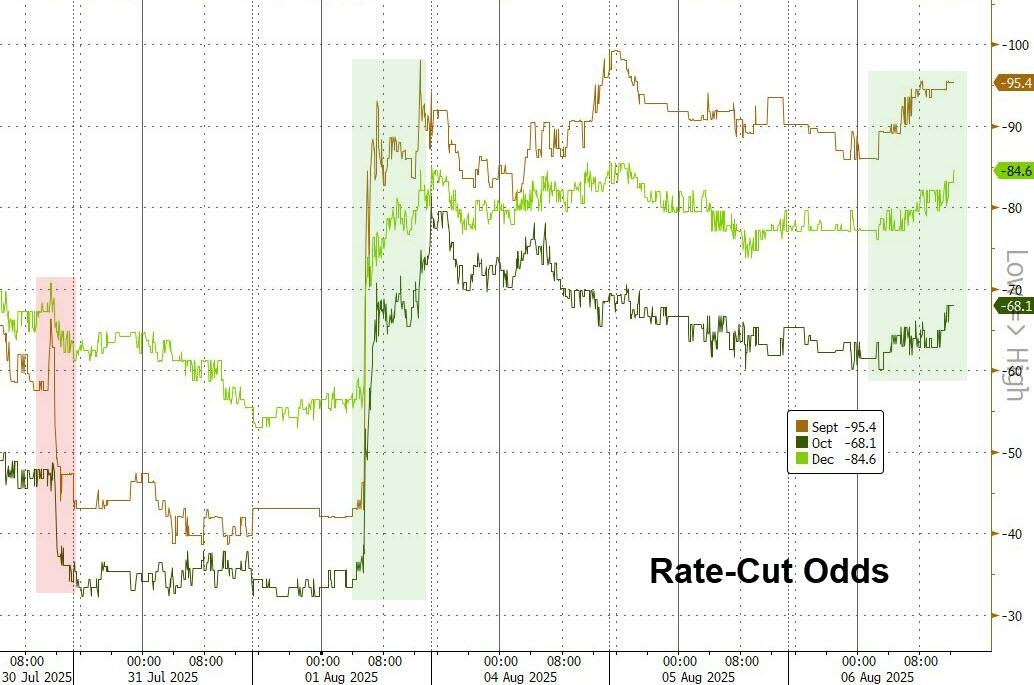
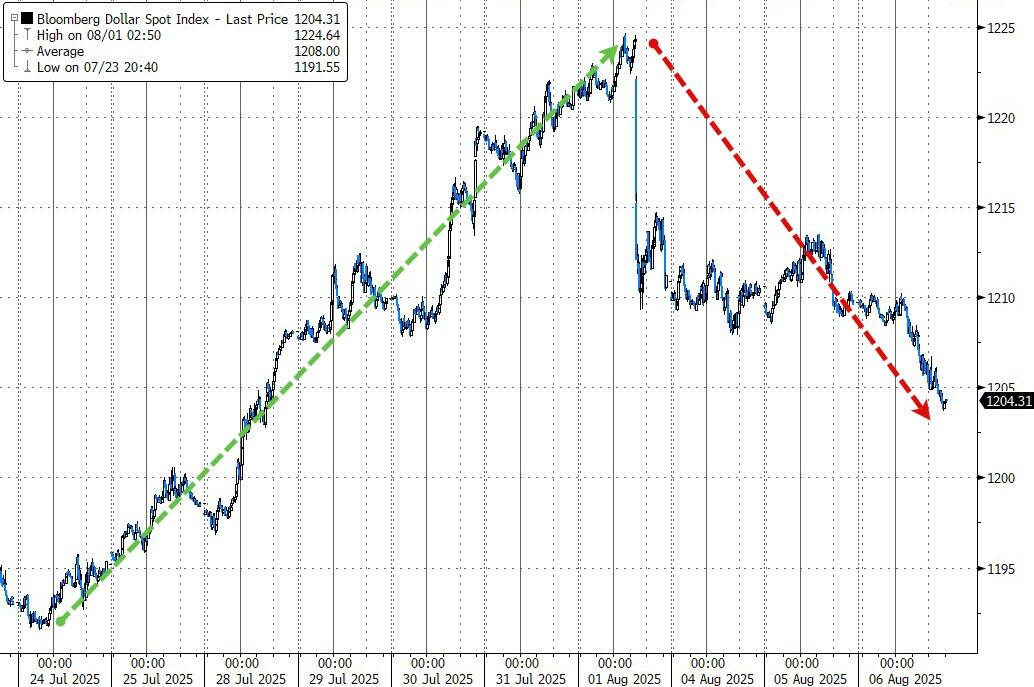
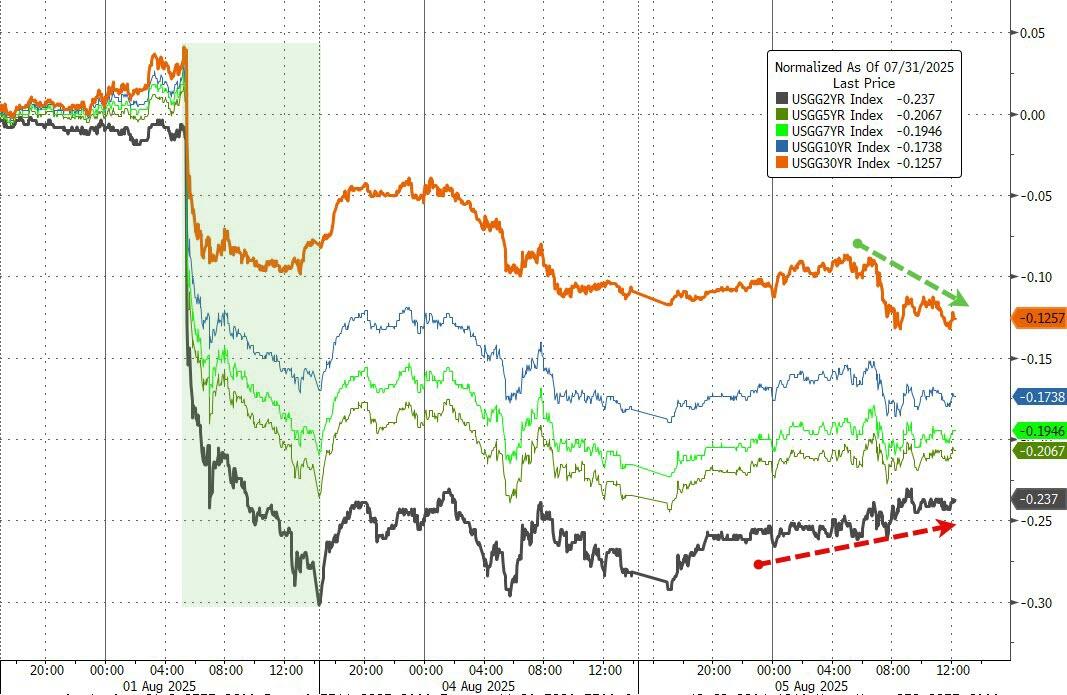
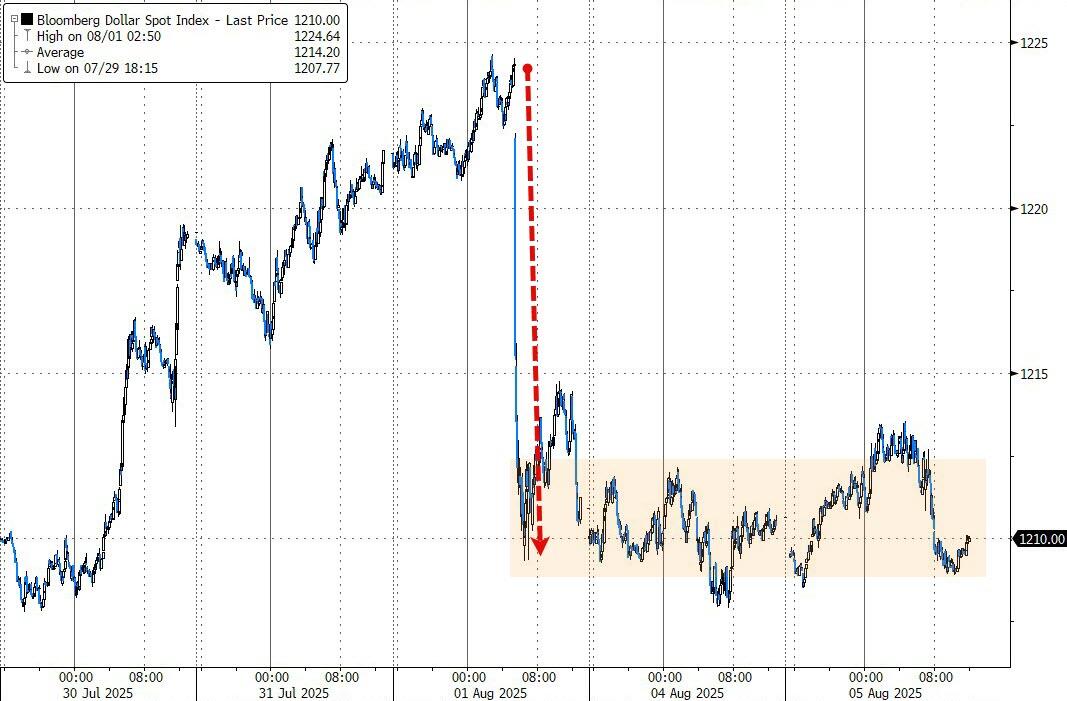
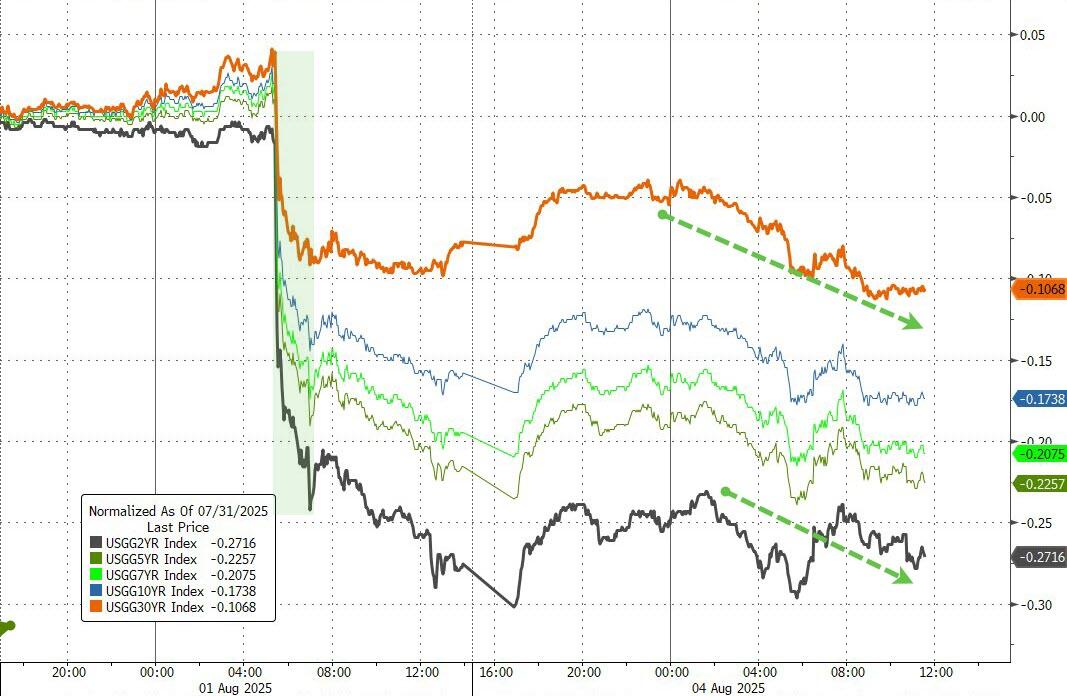
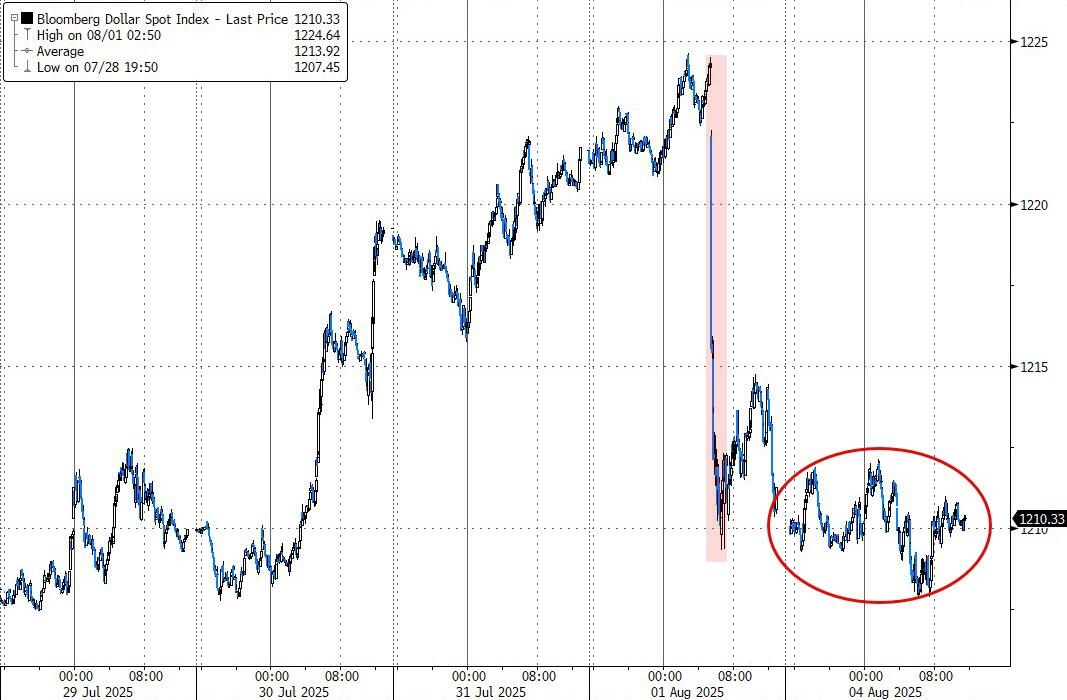
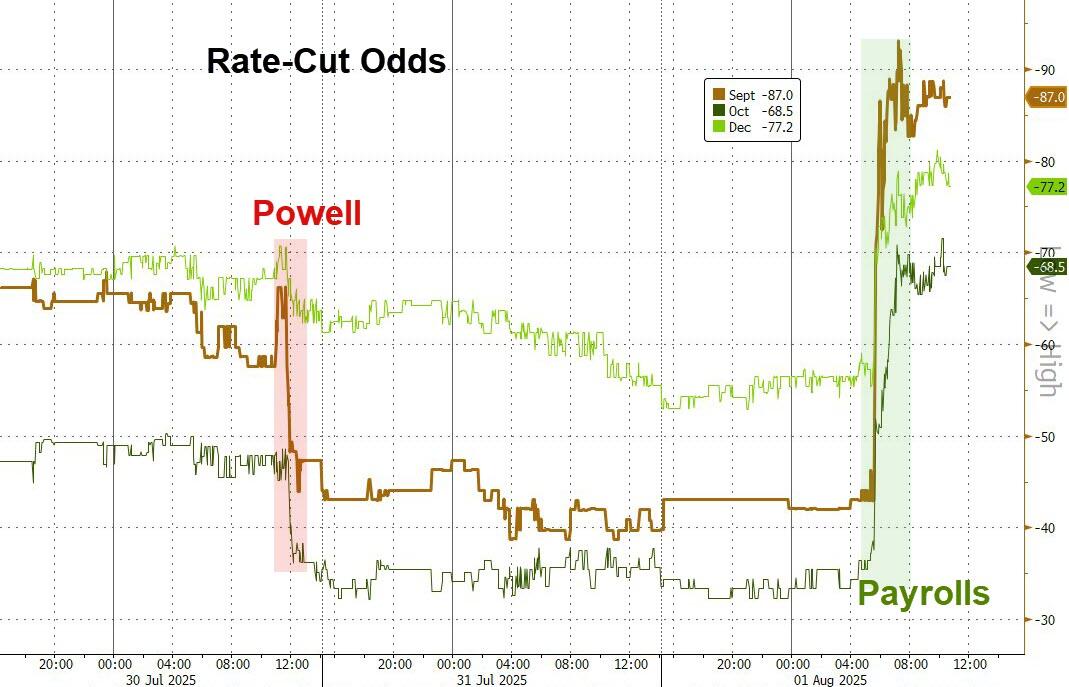
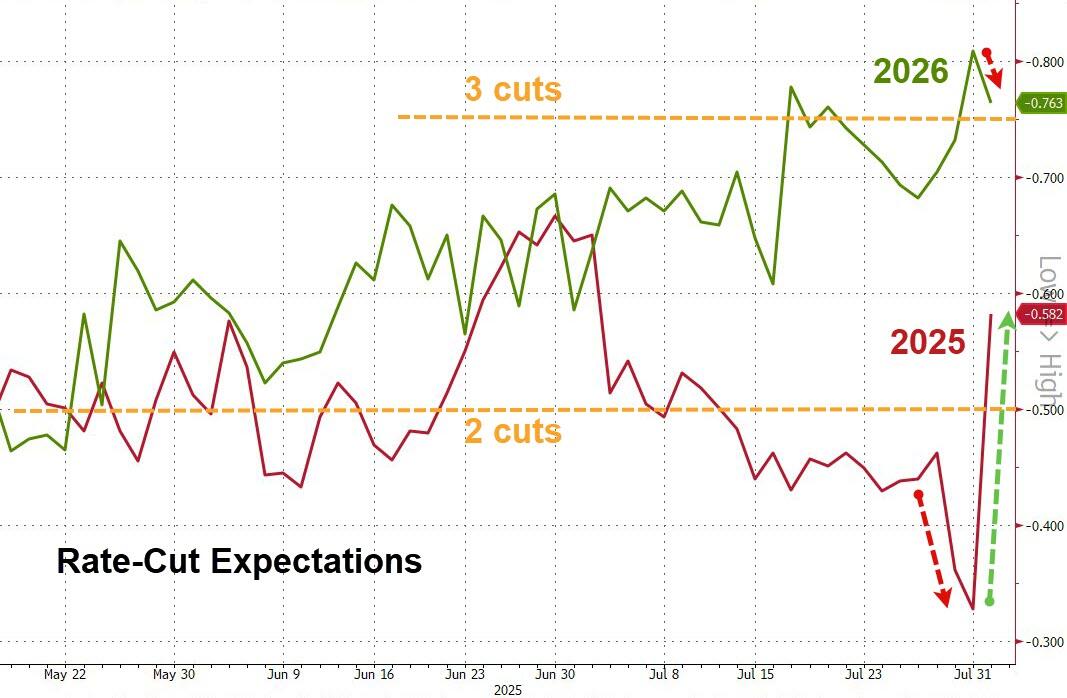
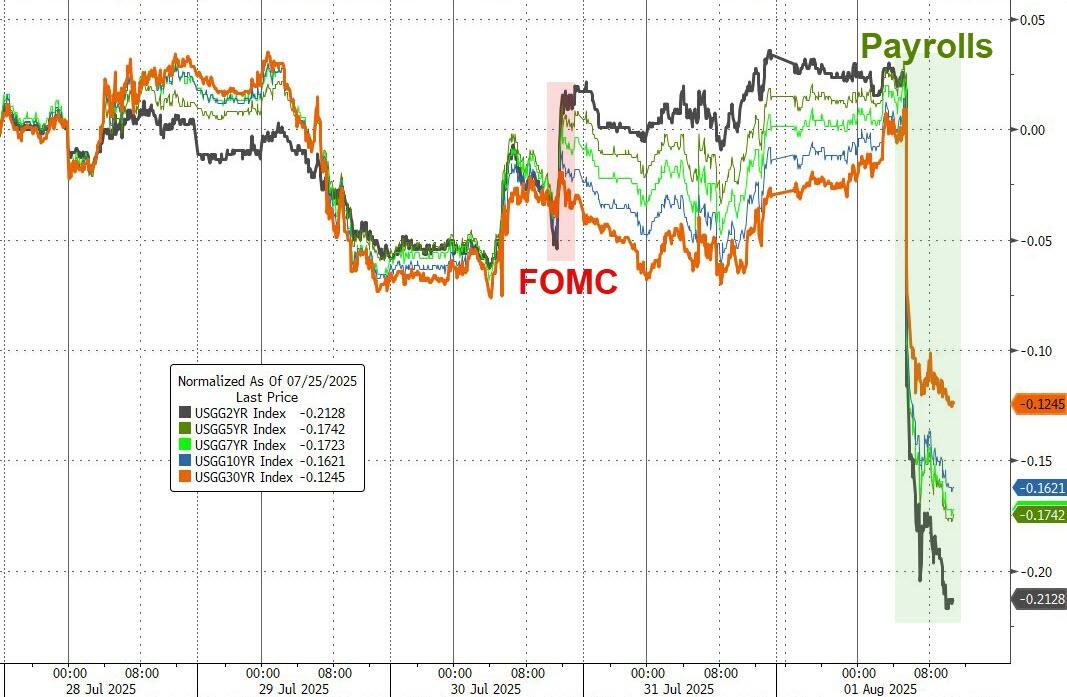
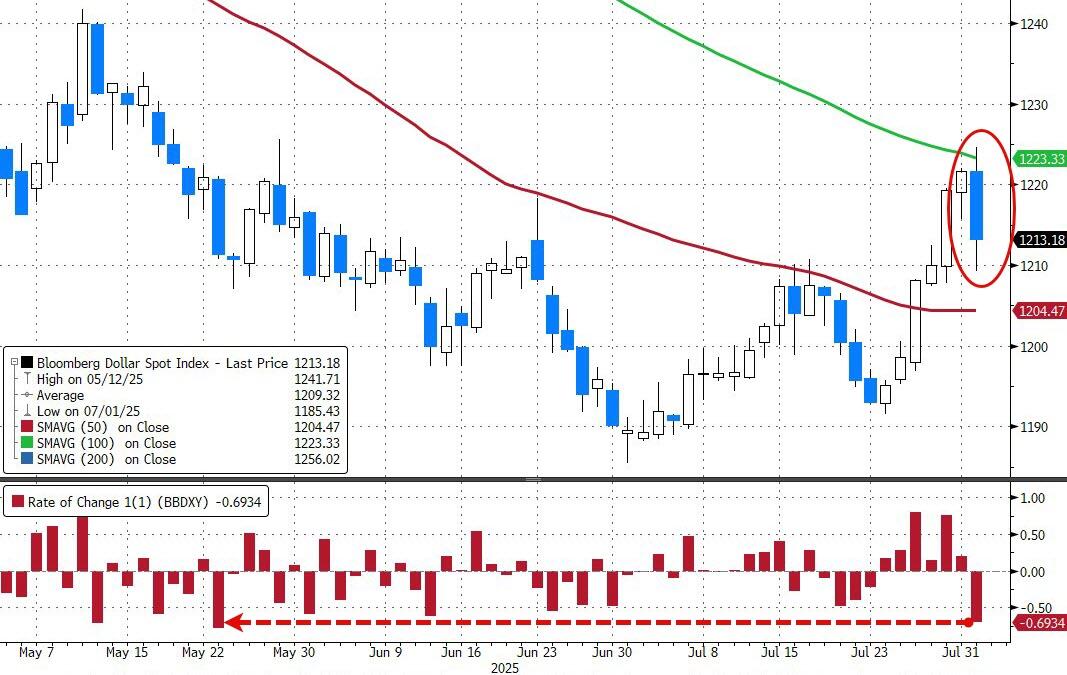
The rest of the market was a bit of a mixed bag: bond yields went sideways, rate-cut odds edged higher for the rest of the year, and the dollar took another hit.
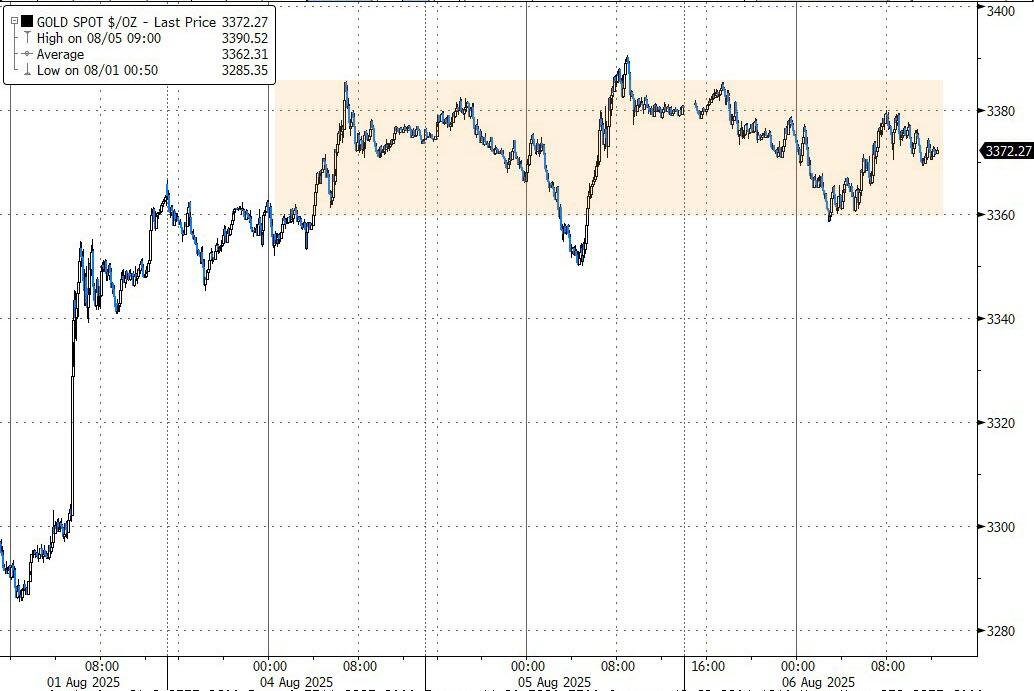
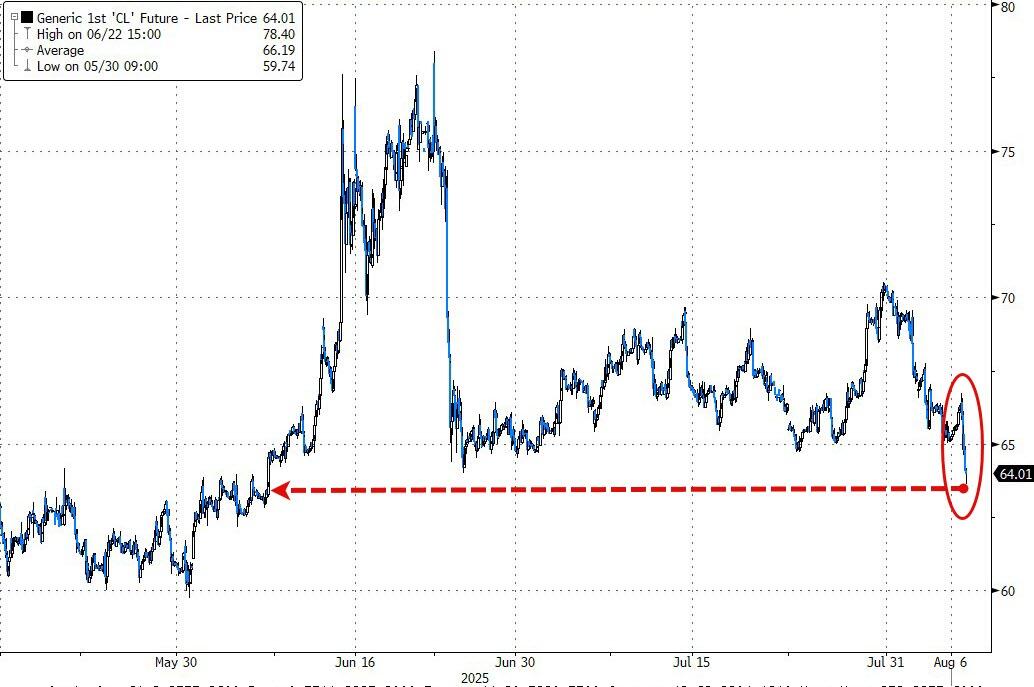
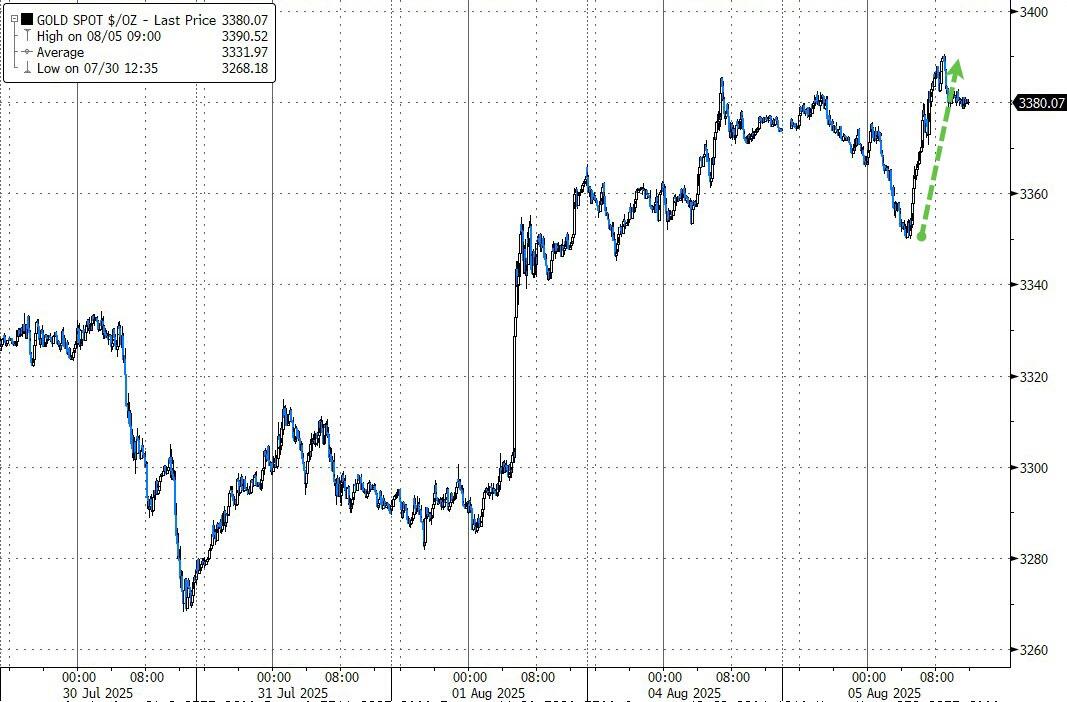
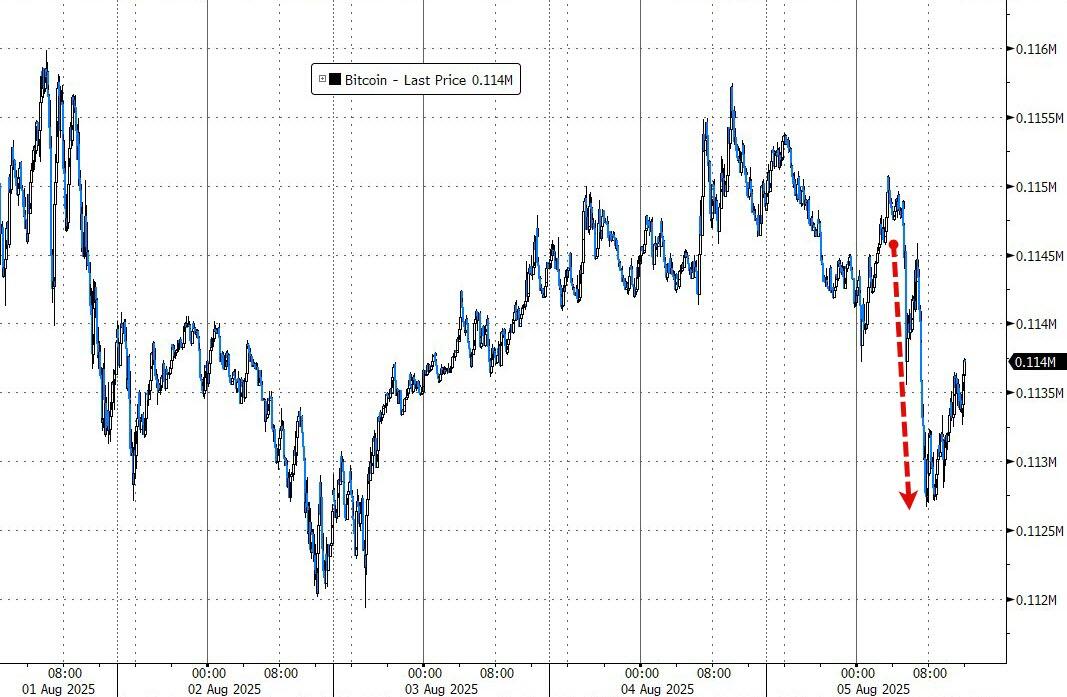
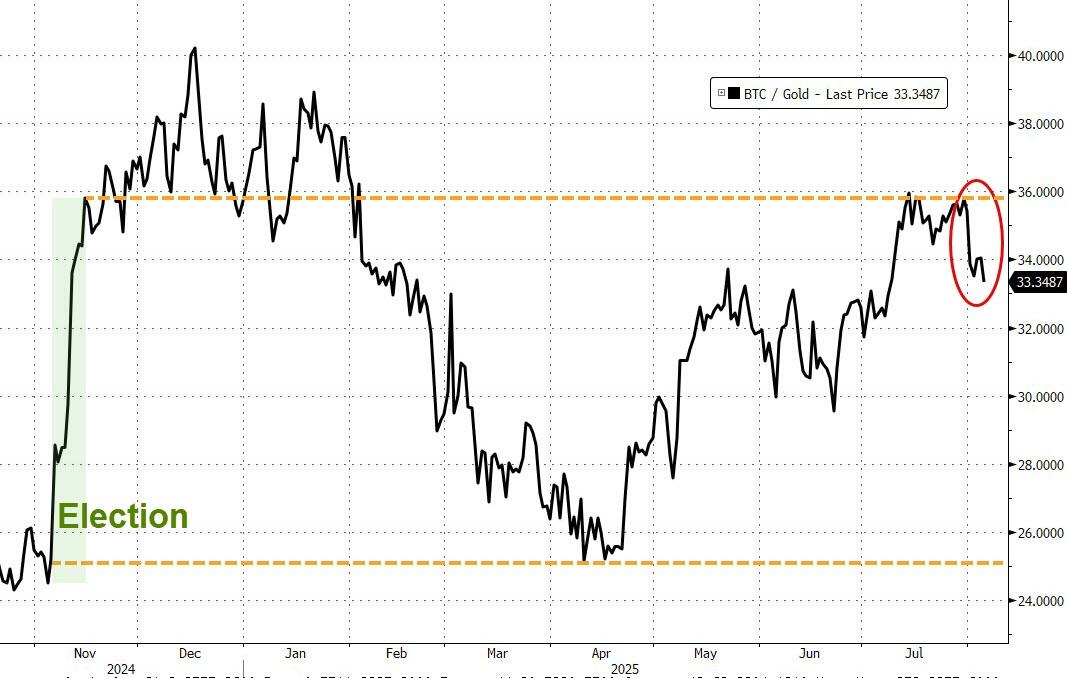
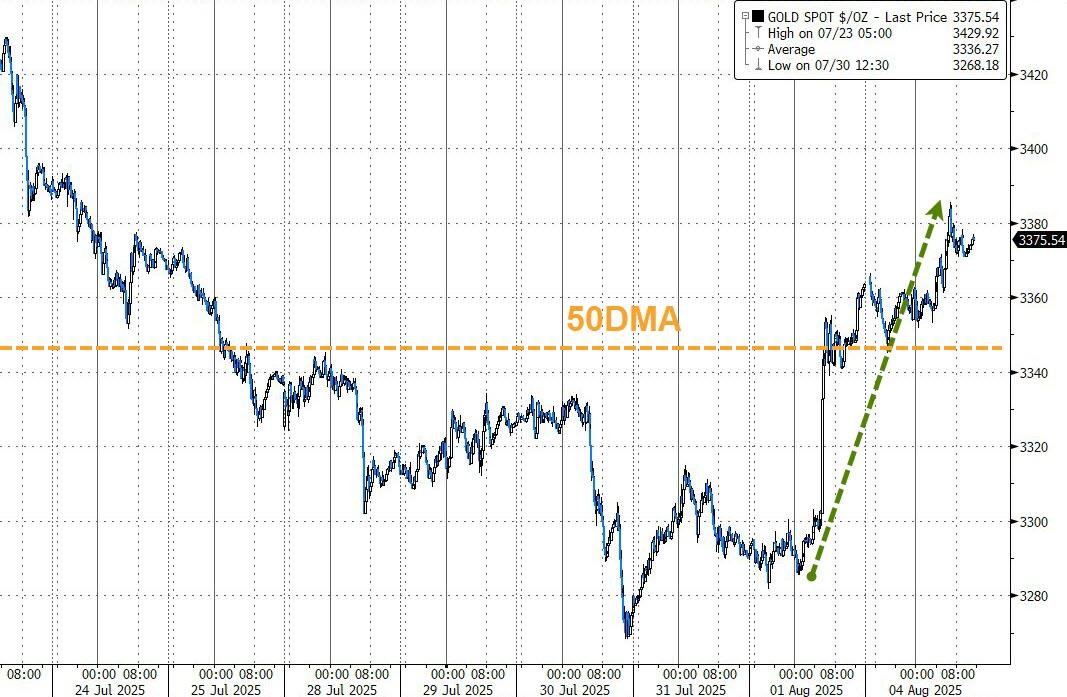
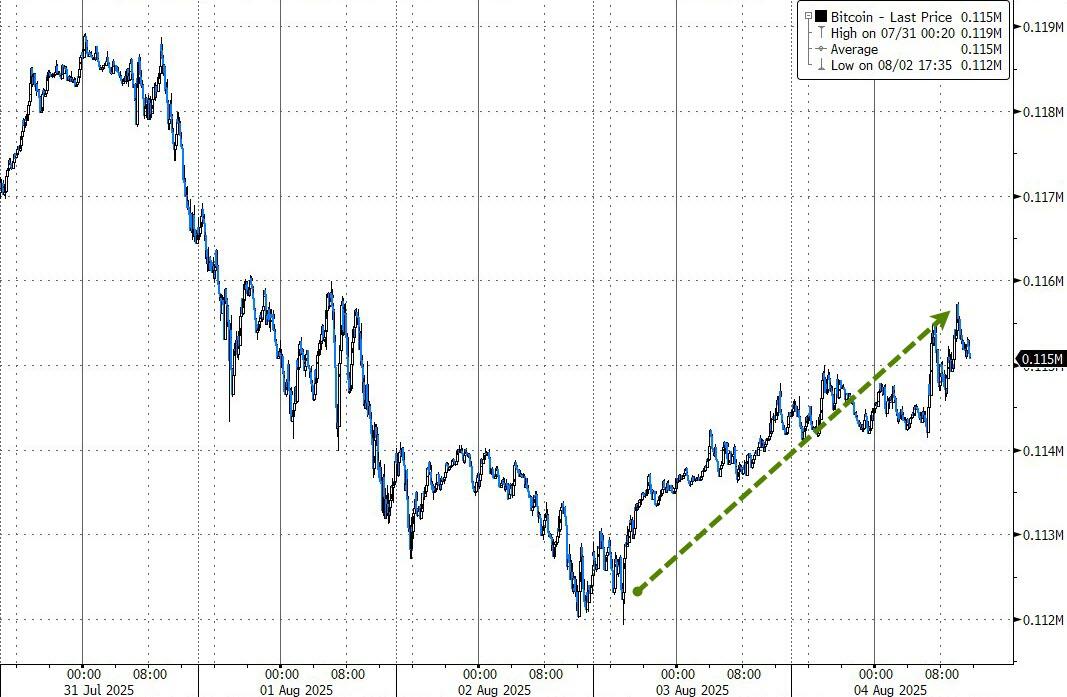
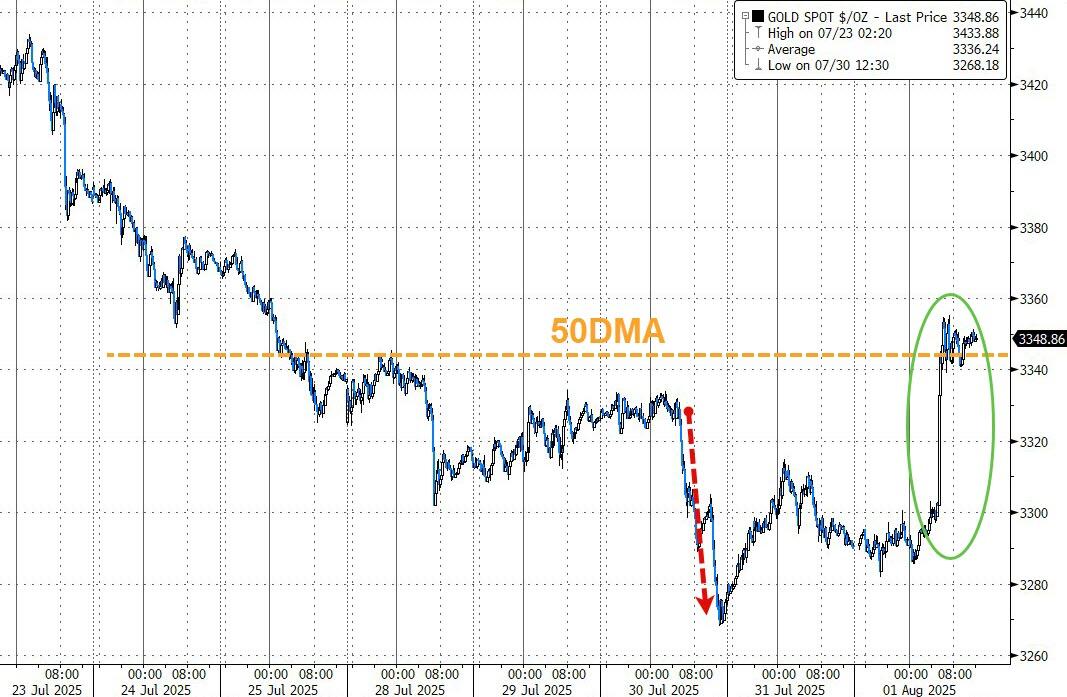
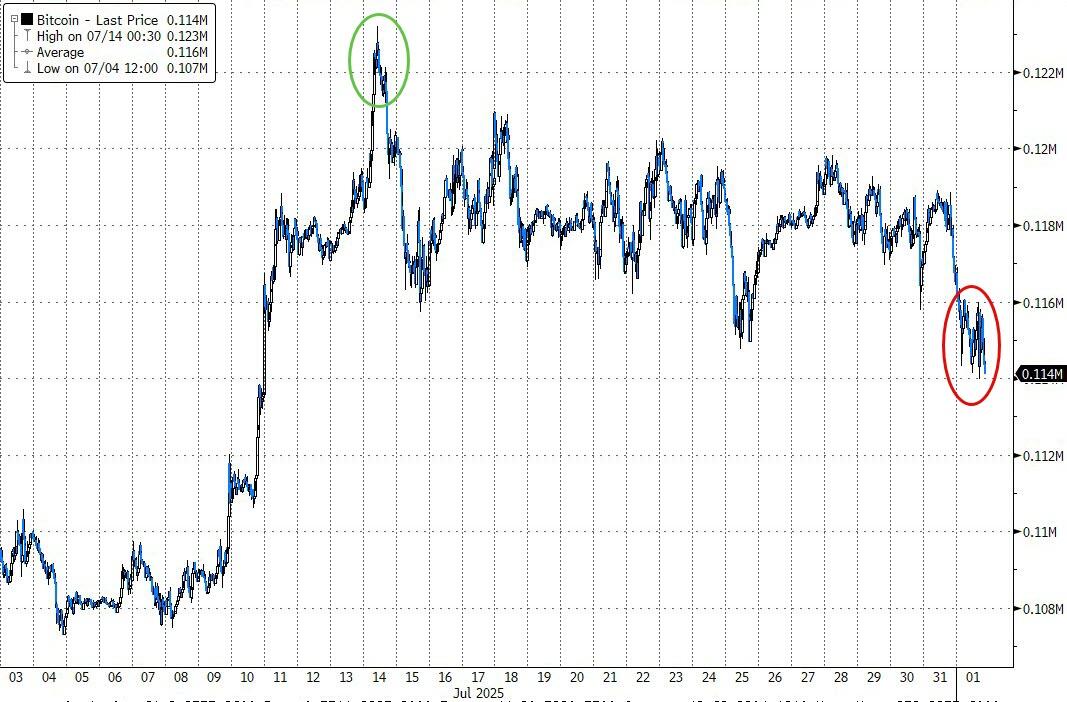
Gold couldn’t catch a break and slipped just a bit. Meanwhile, Bitcoin bounced nicely back above $115,000, clawing back more than it lost yesterday—while crude oil slid to a two-month low.
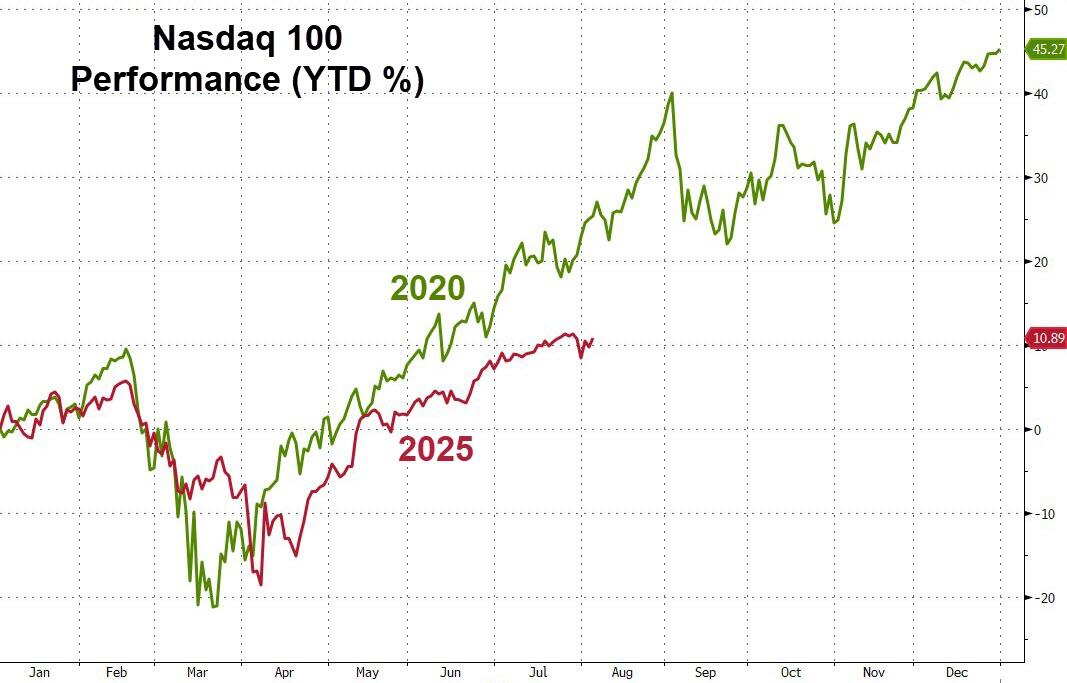
ZeroHedge pointed out that the Nasdaq 100’s performance this year is eerily like its 2020 run—so the big question is: Will history repeat itself with a sharp comeback, or are we headed for a different kind of finish this time?
Read More