Big Gains On Wall Street—A New Domestic Buy On The Horizon?

Ulli Market Commentary Contact

Thur pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

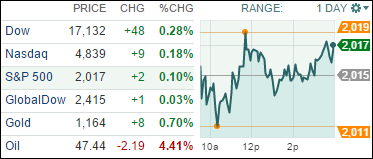
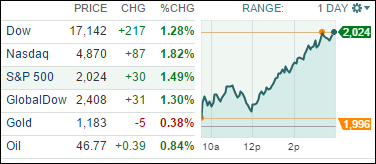
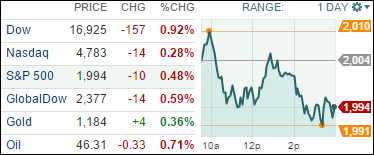
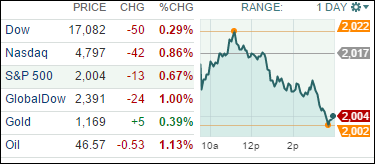
Stocks jumped Thursday, the Nasdaq gaining 1.8% and the Dow climbing 217 points amid mixed profit results from major banks and as less-than-stellar incoming economic data lowered chances of Federal Reserve interest rate hike later this year.

The rebound came a day after shares tumbled sharply after giant retailer Walmart (WMT) warned of a big drop in earnings in its 2017 fiscal year.

Driving the stock action Thursday was an earnings beat by banking giant Citigroup (C), which topped analyst expectations by 3 cents, and a minor miss from Wall Street titan Goldman Sachs (GS), whose earnings came in a penny shy of expectations. Both Citigroup and Goldman Sachs fell shy on revenue.

Wall Street also digested fresh economic data. First-time jobless claims fell 7,000 to 255,000 to a pre-recession low in the latest weekly report, signaling once again that the employment picture is improving. On the inflation front, inflation at the consumer level, or the CPI, fell 0.2% in September, in line with economists’ expectations. The continued low inflation also gives credence to Wall Street’s theory that the Fed will hold off on rate hikes this year.

The question now is will there be enough follow through momentum to generate a new domestic Buy signal? As you can see in section 3, we’re getting close but are not there yet.

In a reversal from yesterday, all of our 10 ETFs in the Spotlight joined the party and closed higher. The leader was Healthcare (XLV) with +2.17%, while Consumer Staples (XLP) and the Dividend ETF (DVY) lagged a little with +0.90%.
Read More

Earnings Drag Markets Down

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Markets closed lower today after a lackluster bunch of quarterly earnings reports. The reports gave a somewhat confirming nod to speculative investors that the U.S. and global economy will may experience a slowdown over the next year,

As far as earnings go, Walmart (WMT) shares experienced their lowest one-day drop in nearly thirty years after the U.S. retailing giant jolted financial markets by forecasting a 6% to 12% earnings drop in fiscal year 2017. The company said earnings for sales growth for the current fiscal year would be flat, a drop from the 1% to 2% increase earlier forecasted by Wall Street analysts.

On the other side of the coin, the air travel market seems to be boding well for Delta (DAL). Today, the company announced $1.4 billion in adjusted net income for the Q3, or $1.74 per diluted share, amid low fuel prices and solid demand from travelers. The strong performance that marked a 45% improvement over the same period a year earlier is expected to continue during the final three months of the year, according to Delta’s CEO Richard Anderson.

Also in earnings news today, shares of Netflix (NFLX) sank 8.7% to $100.61 after the company reported that U.S. subscriber additions fell below its own forecast.

None of our 10 ETFs in the Spotlight was able to buck the trend and all closed lower with Consumer Staples giving back -1.16%, while Healthcare (XLV) held up best with -0.19%.

Read More

Seven Day Streak Snapped; Earnings Disappoint

Ulli Market Commentary Contact

Tue pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

The Dow’s seven day winning streak was snapped today as stocks sank on fresh data showing China’s economy is slowing and investor angst amid the third-quarter earnings season.

The latest news out of China reaffirms fears of a slowdown in the world’s second-largest economy and again has everbody wondering whether the slowdown in Asia will dent business activity in the United States and Europe as well. I am not sure why there is any uncertainty; of course it will affect the rest of the world; the question to me is only the magnitude of it.

Still, Wall Street is mainly focused this week on the Q3 earnings season. Investors are split on how the earnings season will impact the stock market, which has rallied more than 7% from its lows back in late August.

After the closing bell, we heard from both JPMorgan Chase (JPM) and Intel (INTC). For both companies, it was a mix of good and bad news when it comes to revenue and earnings. JPMorgan Chase impressed with better than expected earnings, but the company’s revenue came in lower than expected, mostly due to a drop in its mortgage banking business. Intel, like JPMorgan, impressed with higher than expected earnings, but their revenues also fell short of expectations.

All of our 10 ETFs in the Spotlight retreated and headed south as the indexes slipped. Leading the pack to the downside was Healthcare (XLV) with -1.25% while the Dividend ETF (DVY) fared the best by only giving back -0.51%.

Read More

Markets Keep Climbing On Columbus Day

Ulli Market Commentary Contact

Mon pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

The Dow Jones industrial average, coming off its biggest weekly gain since February, ended modestly higher to post its seventh-straight session of gains as Wall Street awaited the barrage of corporate earnings reports, which begin tomorrow. The S&P 500 and Nasdaq both performed well today also.

The question remains: “Is this a new bull market or a bear market bounce?” While there are many viewpoints, I believe that until we actually see a crossing of our Domestic Trend Tracking Index (TTI) into bullish territory, this is nothing but a dead cat bounce, although one of great magnitude. Only time will tell whether a new bullish cycle is in the making.

Wall Street was also digesting a big deal in the tech sector, where Dell (DELL) teamed up with MSD a private equity firm Silver Lake to purchase data storage player EMC for $33.15 per share in a blockbuster cash and stock deal valued at more than $67 billion. The deal is notching its place in history as the biggest ever in the tech sector.

As I mentioned last week, most investors are anxiously awaiting corporate earnings this week from some of the big financial institutions, such as JP Morgan (JPM), Wells Fargo (WFC), Citigroup (C) and Bank of America (BAML). We will hear from Johnson & Johnson (JNJ) and Intel (INTC) on Tuesday.

7 of our 10 ETFs in the Spotlight headed north with the leader being Consumer Discretionaries (XLY) at +0.48%. On the downside, Mid-Cap Value (IWS) lost a scant -0.24%.

Read More

ETFs/Mutual Funds On The Cutline – Updated Through 10/9/2015

Ulli ETFs on the Cutline Contact

Below are the latest ETF Cutline reports, which show how far above or below their respective long-term trend lines (39 week SMA) my currently tracked ETFs/MFs are positioned.

The first report covers the ETF Master List from Thursday’s StatSheet and includes 381 ETFs, of which currently 41 (last week 18) are hovering in bullish territory.

The second report includes only High Volume ETFs. To clarify, High Volume (HV) ETFs are defined as those with an average daily volume of $10 million or higher.

These ETFs are generated from my selected list of some 97 that I use in my advisor practice. It cuts out the “noise,” which simply means it eliminates those ETFs that I would never buy because of their volume limitations. 7 ETFs (last week 4) have managed to remain in bullish territory after the recent market volatility.

The third report covers Mutual Funds on the Cutline. There are currently 49 (last week 15) above the line and 751 below it out of the 800 that I follow.

Take a look:

  1. ETF Master Cutline Report
  2. ETF High Volume Cutline Report
  3. MF Cutline Report

In case you are not familiar with some of the terminology used in the reports, please read the Glossary of Terms.

If you missed the original post about the Cutline approach, you can read it here.

One Man’s Opinion: Will Consumer Discretionaries Lead In Earnings Growth In Q3?

Ulli Market Review Contact

ManThe S&P 500, according to Estimize, is likely to see a negative earnings growth of 2-1/2 percent and revenues growth of negative 1.7 percent. In the last quarter, earnings growth expectations were 3.5 percent, but it ended up with about 1 percent. The peak-rate currently stands at about 66 percent for about 22 companies that have reported third-quarter results and companies do tend to beat expectations with going into the season.

But until now, all commodity-related stocks have slumped with energy EPS sliding 66 percent and materials losing about 5 percent. Globally, China is likely to remain a worry with the bursting of equity bubbles there and the effects are likely to be stronger than in the second quarter, she noted.

Asked which sectors are likely to perform well, Christine said consumer discretionary will be a winner since lower oil does benefit some sectors. Estimize expects the discretionary sector to record a 13.5 percent growth this quarter with a special focus on automobiles.

Read More