- Moving the markets
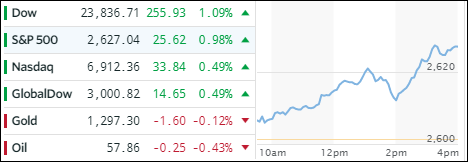
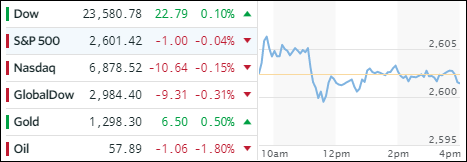
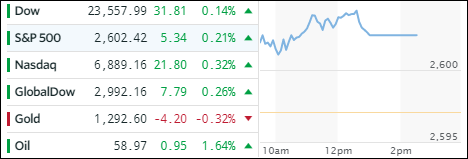
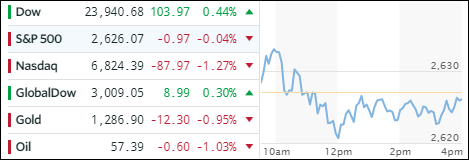
It’s really no surprise that the best performing sector of 2017 had to eventually come off its lofty levels and back to reality. That moment was today as, despite nine of the 11 S&P sectors gaining, Semiconductors (SMH) took a hit at the rate of -4.24%. Autodesk (ADSK) announced some earnings and restructuring plans that left the tech sector in the dust—at least for the day. However, considering that SMH was up over 45% YTD, a pullback like this had to be expected.
On the other side of the spectrum, the Dow ignored the bad news and sprinted again into record territory, while the S&P was not quite able to climb above the unchanged line. The ETF space affecting our portfolios was mixed and other areas made up for the Nasdaq’s weakness. Leading to the upside were Transportations (IYT) with a chest pounding +3.40% gain, which was followed by the Financials (XLF), which advanced +1.71%. Besides the Semiconductors dropping, we saw Emerging Markets (SCHE) surrendering -1.53%.
Interest rates rose with the yield on the 10-year bond gaining 3 basis points, which was enough to send the price of the 20-year bond (TLT) sharply lower by -0.99%. The effect on the High Yield sector (HYG) was only moderate with a loss of -0.13%. In a repeat from yesterday, both gold and oil slipped again while the US Dollar (UUP) traded in a tight range and ended up giving back -0.04%.