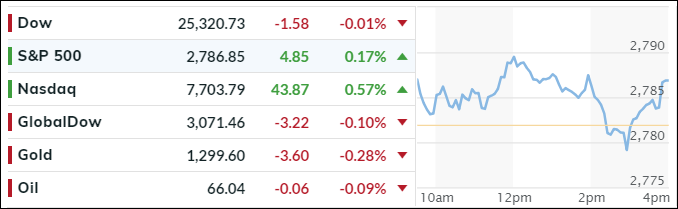
- Moving the markets
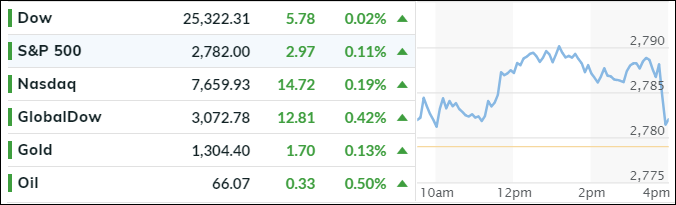
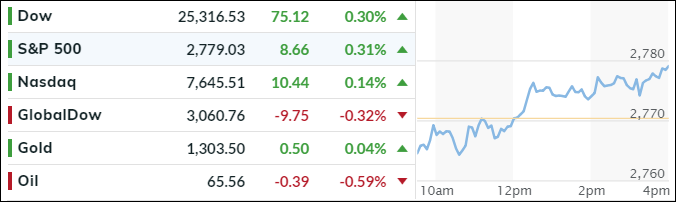
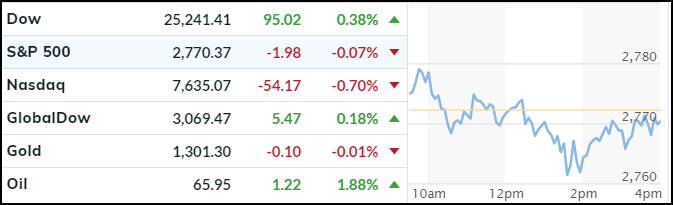
Not much mattered to the markets today, as the major indexes were stuck in a tight range with MSM seemingly ignoring or simply shrugging off the outcome of the historical meeting between Trump and Kim Jong Un.
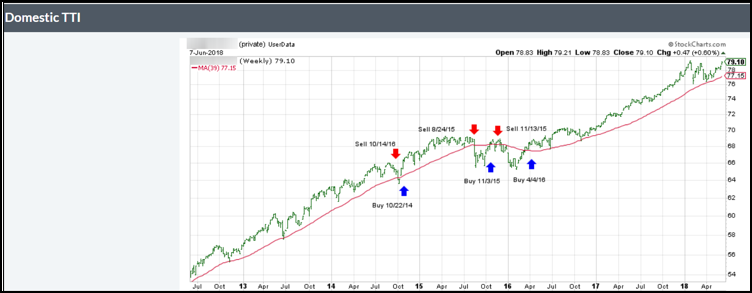
Undeterred by the flat session, bullish momentum remains in place, despite recent events to the contrary, like, as one writer pointed out, “the US starting a global trade war, Italy electing a populist government, emerging markets descending into yet another crisis, and inflation rising from the dead – all of which would be expected to spook normal financial markets and send capital pouring into safe havens.”
Especially, on the inflation front, things start to look shaky, to say the least. Today’s release of the CPI met the consensus estimate of +0.2% MoM making the expected YOY number +2.8%, the highest since December 2011 while, at the same time, real wage growth slumped. Hmm, makes me wonder what ever happened to the Fed’s mandate of an upper 2% inflation limit?
Things were quiet on the interest rate front. After an early attempt to break the 10-year 3% yield ceiling, yields started to ease up, faded and ended the session unchanged.
All eyes are now on central bank meetings this week. First, the Fed is expected to raise interest rates tomorrow at the end of their 2-day discussions. This will be followed by the ECB on Thursday, when they are supposed to announce the timing of the unwinding of their bond purchases.