ETF Tracker Newsletter For September 28, 2018

Ulli ETF Tracker Contact

ETF Tracker StatSheet

https://theetfbully.com/2018/09/weekly-statsheet-for-the-etf-tracker-newsletter-updated-through-09-27-2018/

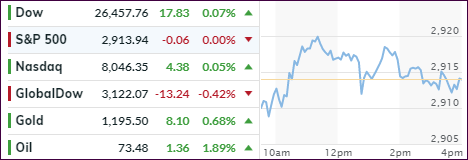
A Weak Close To A Positive Month

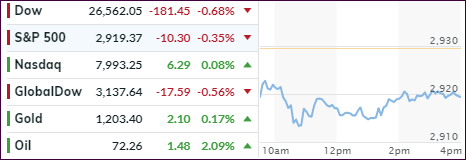
[Chart courtesy of MarketWatch.com]
  1. Moving the markets

The major indexes struggled to find some footing today, but in the end hugged the unchanged line after vacillating above and below it throughout the session.

Geopolitical tensions from Italy were back in focus after the Italian coalition decided yesterday on an “in your face” attitude towards the EU by simply widening their regulated budget deficit, which I mentioned yesterday. The verbal fireworks continued today and will sure be headline news in the following weeks.

In Argentina, the Peso plunged to new record lows, as the government hiked a major interest rate to 65%. Ouch! All this despite promises by the IMF to increase its bailout package. This is just the beginning of further deterioration in the Emerging Markets arena with a domino effect being a likely outcome that eventually will impact the developed nations as well.

Domestically, the major indexes had a mixed September but a strong quarter with the S&P 500 rising some 7%, its biggest quarterly advance sine 2013. This made it easy for investors, who tend to have very short-term memories, to not only forget the sharp market corrections of February and April but also appreciate the fact that US stocks are still outperforming the world’s indexes.

Makes you wonder how long that path can continue, especially given the fact that bonds had a bloodbath in September with yields ending at a much higher level than when they started the month. Rallying equities and rising bond yields are not a combination that will last for long.

Adding to that uncertainty was that true economic data points are decoupled from equity prices as this chart shows. Will the month of October be the big equalizer, as we’ve seen in the past? Who knows, but I am glad that we have an exit strategy in place, just in case reality bites the bulls in the butt.

Read More

Weekly StatSheet For The ETF Tracker Newsletter – Updated Through 09/27/2018

Ulli ETF StatSheet Contact

ETF Data updated through Thursday, September 27, 2018

Methodology/Use of this StatSheet:

  1. From the universe of over 1,800 ETFs, I have selected only those with a trading volume of over $5 million per day (HV ETFs), so that liquidity and a small bid/ask spread are assured.
  2. Trend Tracking Indexes (TTIs)

Buy or Sell decisions for Domestic and International ETFs (section 1 and 2), are made based on the respective TTI and its position either above or below its long-term M/A (Moving Average). A crossing of the trend line from below accompanied by some staying power above constitutes a “Buy” signal. Conversely, a clear break below the line constitutes a “Sell” signal. Additionally, I use a 7.5% trailing stop loss on all positions in these categories to control downside risk.

  1. All other investment arenas do not have a TTI and should be traded based on the position of the individual ETF relative to its own respective trend line (%M/A). That’s why those signals are referred to as a “Selective Buy.” In other words, if an ETF crosses its own trendline to the upside, a “Buy” signal is generated. Since these areas tend to be more volatile, I recommend a wider trailing sell stop of 7.5% -10% depending on your risk tolerance.

If you are unfamiliar with some of the terminology, please see Glossary of Terms and new subscriber information in section 9.


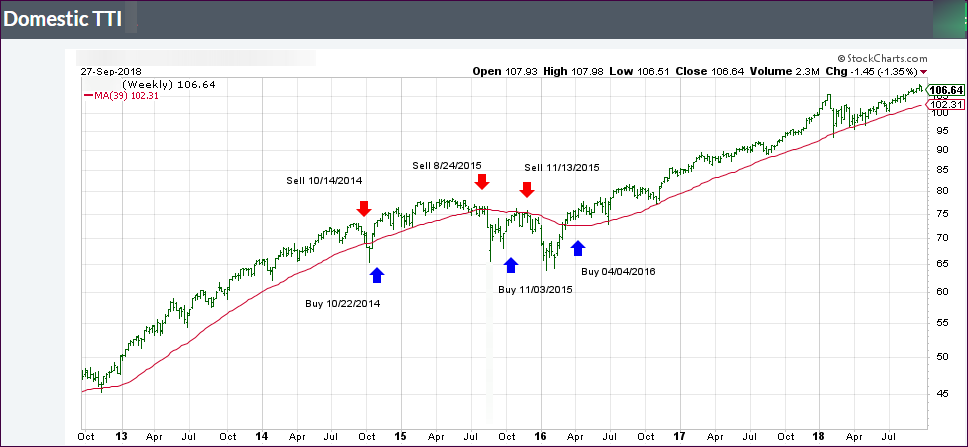
  1. DOMESTIC EQUITY ETFs: BUY — since 4/4/2016

 Click on chart to enlarge

Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in the above chart) is positioned above its long-term trend line (red) by +3.96% after having generated a new Domestic Buy signal effective 4/4/2016 as posted.

Read More

Slipping Off The Mid-Day Highs

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

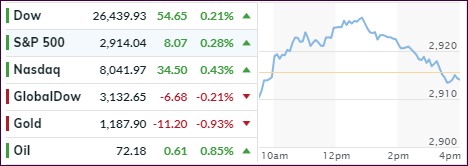
An early rally was rebuffed mid-day when bullish momentum faded, and the indexes headed south. For a while, it looked like we’d be ending up in the red again, but last hour buying halted the S&P 500’s 4-session skid, and we closed modestly in the green.

Some of this weakness was a hangover from yesterday; more specifically the Fed’s decision to stay the course on hiking interest rates. Some economic data released this morning did not help the bullish theme, such as Pending Home Sales dropping 1.8% MoM, which was just about 4 times worse than expected and reaching their lowest level since Oct. 2014.

This was followed by a surge of the Trade Deficit, which ballooned to $75.8 billion in August vs. expectations of $70.6 billion. In historical context, this is close to the all-time 2008 record high deficit of $76,025 billion. You think this might add some fire or urgency to the current trade war talks?

Italy made headlines today, as they defied Europe’s regulation on budget deficits, which are pegged to a maximum of 2% of GDP. However, the Italian governing parties agreed on a 2019 budget deficit of 2.4%, clearly above the agreed upon ceiling setting up a potential skirmish with an unknown outcome.

The immediate consequence was a drop in the Euro and a surge in the US Dollar, which extended its bounce back to 2-week highs. US bond yields were not affected and dropped slightly.

Tomorrow is the last trading day of September, and we’ll be staring October in the face, a month which has demonstrated in the past that it can be a bull market killer. It does not necessarily have to turn out that way, but in my view, it pays to be prepared by having an exit strategy should a major hiccup occur.

Read More

An Early ‘Hope’ Rally Runs Out Of Steam As Fed Hikes Rates

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

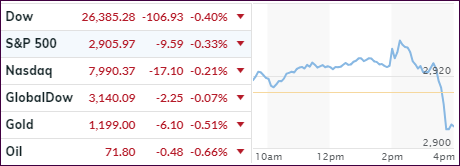
The Fed stepped up to the plate and delivered the 3rd 25 basis point interest rate hike this year, which was widely expected but hope for ‘accommodation’ still powered an early rally that ran out of steam once reality hit the markets.

The major indexes reversed course, headed south and closed marginally in the red. Furthermore, the Fed indicated that a 4th hike in December would be a distinct possibility and that 3 more might follow in 2019.

Bond yields took a dive and shaved off 5 basis points to close at 3.05%; a level last seen on September 19th. The US Dollar swung wildly intra-day, but the closing price of UUP was only +0.04% higher, which did not reflect the see-saw action of the session. The Bloomberg Dollar Index demonstrates the irrational exuberance shown over the past week as ZH quipped: “Does this remind you of a penny stock?”

We’ll have to see how the markets will digest the interest hike hangover over the next few days. It very well may simply present an additional uncertainty in the basket of “things to worry,” with tough trade talk, a weakening housing market and bloating federal debt rotating to compete for the headline of the day.

Read More

Aimless Meandering

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

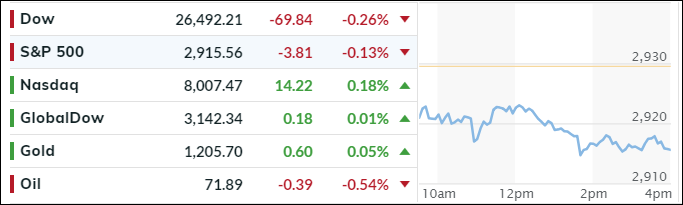
The markets diverged a little bit as the Dow and S&P 500 ended up in the red, while the Nasdaq bucked the trend and closed in the green. However, aimless meandering best describes today’s session with anxiety rising ahead of the Fed’s decision on interest rates tomorrow.

Ignoring the continued trade tensions between the US and China, the markets so far have managed to hover around all-time highs, even though this verbal mudslinging could spiral into a full-blown trade war, which would then result in reduced profits for international corporations and be a supporting meme for the bearish crowd.

With the Fed’s verdict on the directions of interest rates being out due tomorrow, the 10-year bond yield jumped 3 basis points to close at 3.10% and is now in striking distance of taking out its 7 year high. While a hike is somewhat priced in, a lot of hope exists that the Fed will skip this one and enact another one in December. We’ll find out tomorrow around 11:15 AM…

Read More

US/China Trade Wars Back In Focus

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

If you followed the news over the weekend, you would have gotten a pretty good indication as to today’s market direction. Trade war talk made the headlines Saturday morning as Trump’s fresh round of tariffs caused a reaction from  the Chinese, as they now refused to send two delegations to Washington while elaborating that “pressure tactics won’t induce them to cooperate” and pledging that Beijing will “avoid negotiating under threat,” and ending with “we hope that the US side will take measures to correct its mistakes.”

That was enough to kill some of last week’s exuberance in the markets and south we went with the Dow faring the worst, while the Nasdaq managed to crawl out of an early hole. However, in the bigger scheme of things the losses were modest and did not impact our investing strategy, but interest in stocks was sapped, at least for this session. It remains to be seen if there is more fallout to come as this verbal tug-of-war is sure to continue.

The US Dollar was in for a wild ride with ZH describing the action as follows: The Dollar index was sliding lower as Europe opened (China closed), spiked lower on EUR gains after Draghi inflation comments, only to surge higher for the rest of the day on safety concerns following Rosenstein’s resignation headlines…

The 10-year bond yield rose a tad but remains stuck in its recent trading range. I think the odds have now increased of a further breakout to the upside, since it appears that the markets have ‘gotten used to’ a plus 3% yield without much slippage to the downside. Eventually, that picture will change, but for right now the bullish theme for stocks remains intact.

Read More