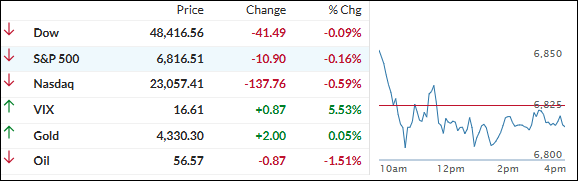
[Chart courtesy of MarketWatch.com]
- Moving the market
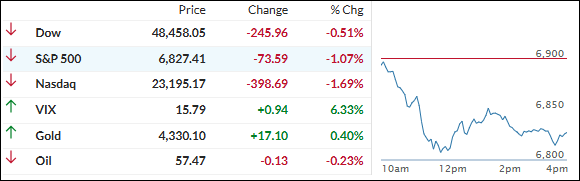
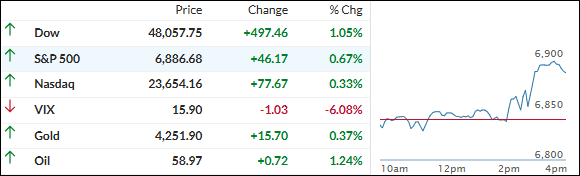
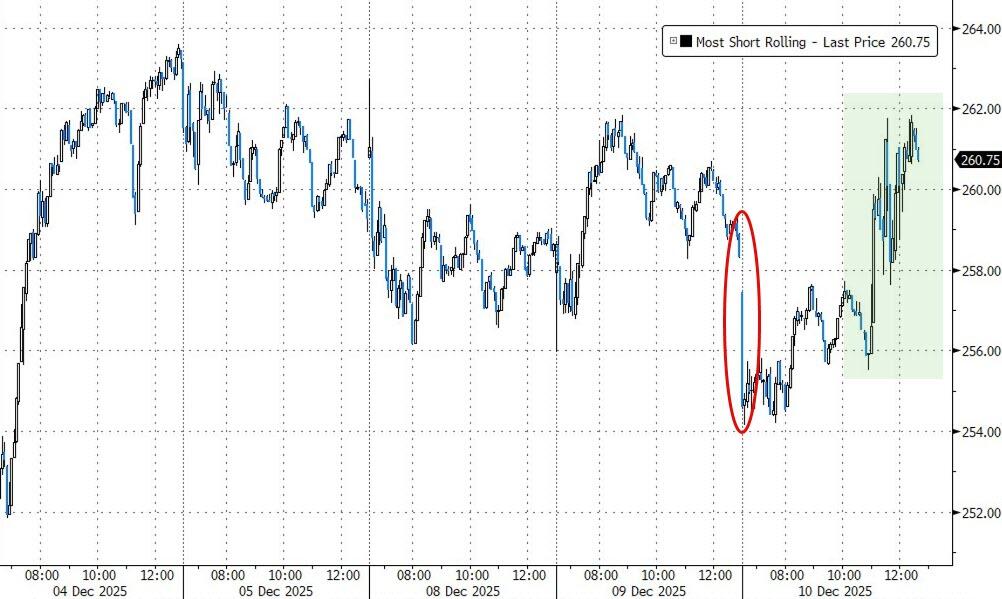
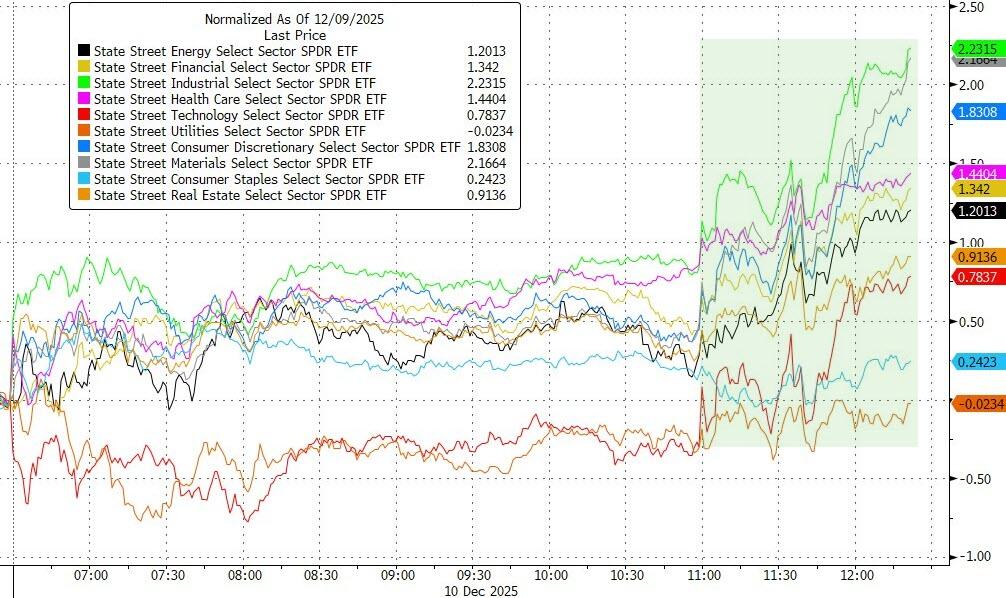
The market tried to get something going early, but the bounce fizzled and the major indexes slipped back into the red as pressure in the AI space kept weighing on sentiment.
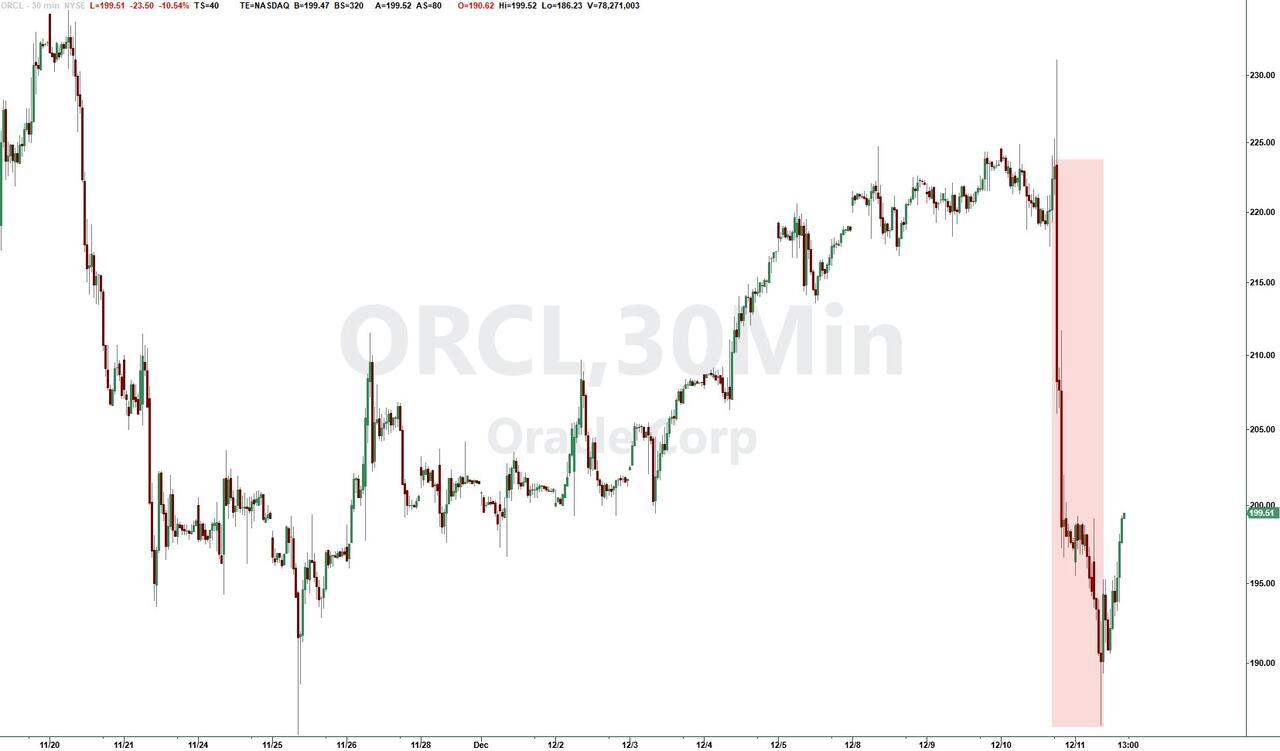
Chipmaker Broadcom dropped more than 4%, while Oracle slid over 3%, extending last week’s weakness that already had the S&P 500 and Nasdaq on the back foot.
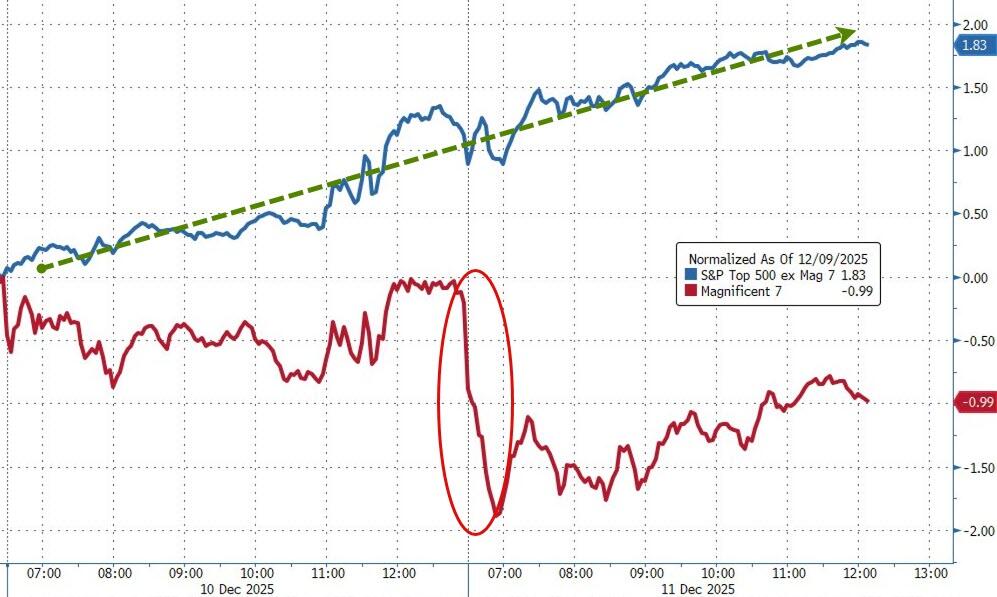
For now, it’s starting to look like the “Magnificent 7” may be a little less magnificent heading into 2026, as fierce competition in the AI race chips away at the dominance they’ve enjoyed.
That kind of shake-up could be a long-term win for the “other” 493 stocks in the S&P 500, which stand to benefit if leadership broadens out beyond a handful of mega-cap names.
This week’s data could play a big role in whether that rotation sticks. November nonfarm payrolls and October retail sales—both delayed by the fall government shutdown—are due Tuesday, with economists looking for roughly 40,000 new jobs, down sharply from September’s 119,000.
Then on Thursday, the November CPI report lands, giving markets a fresh read on the inflation side of the Fed’s mandate.
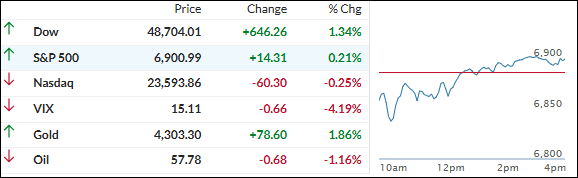
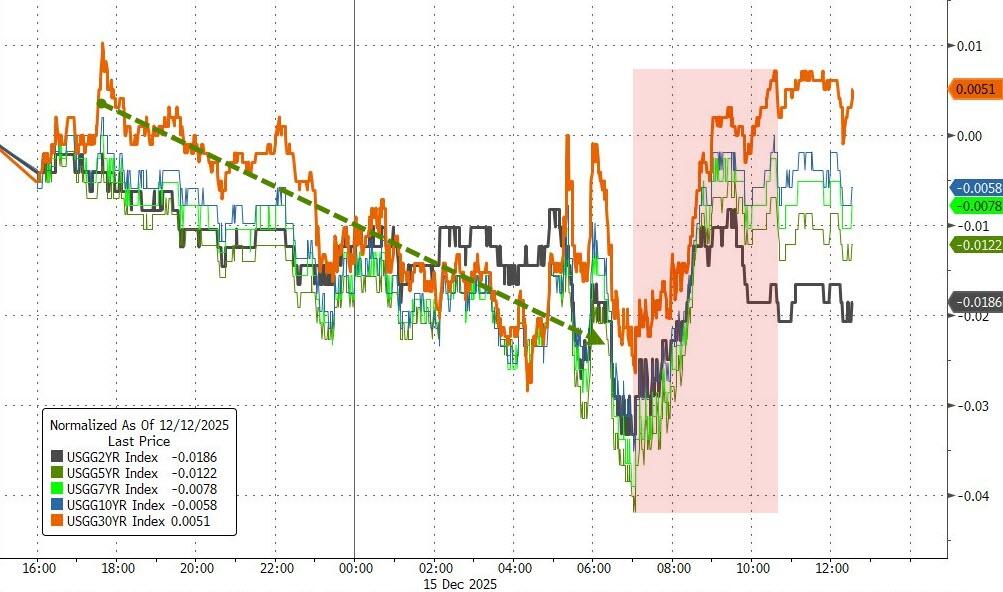
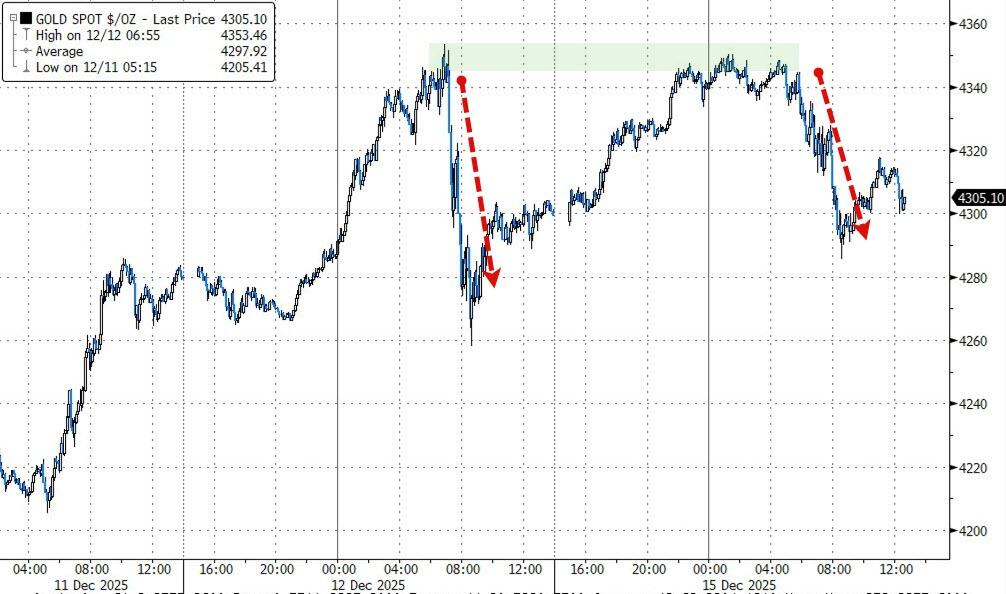
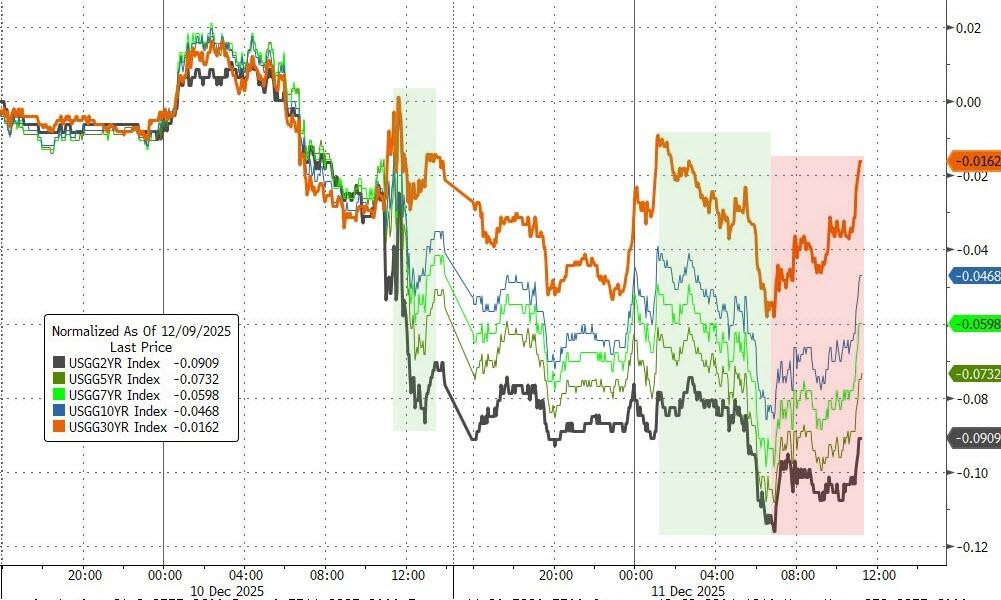
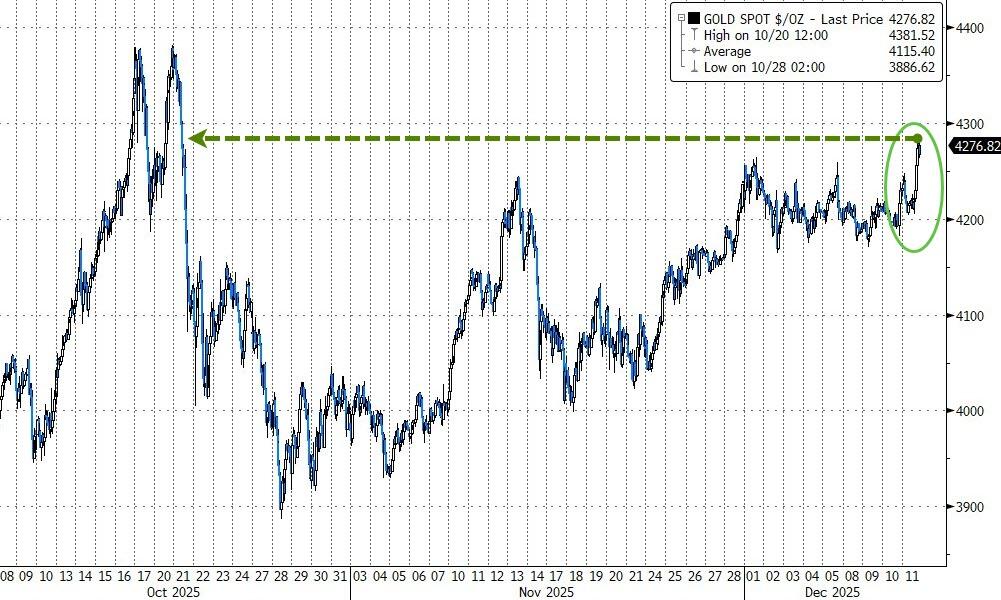
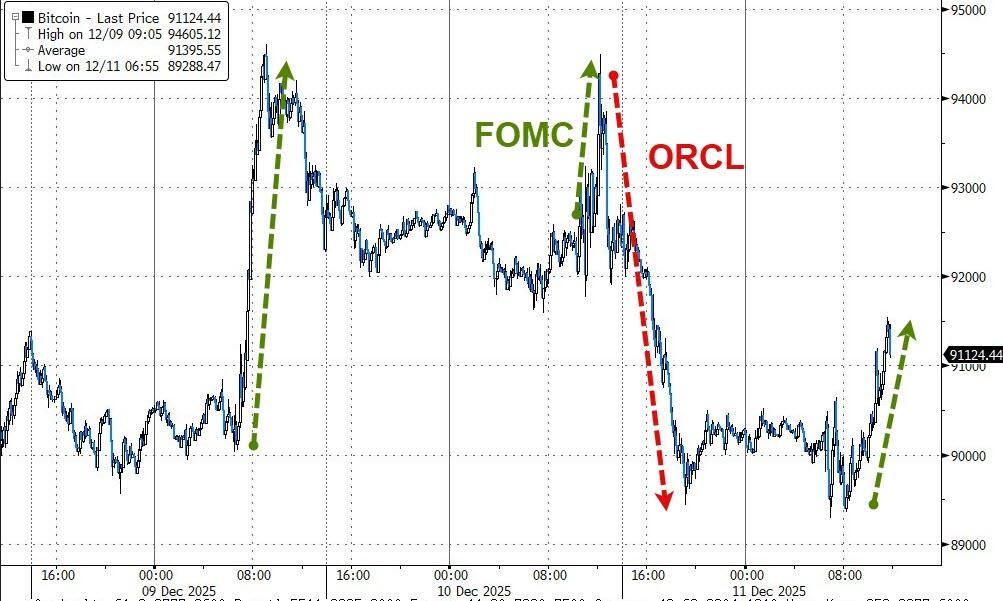
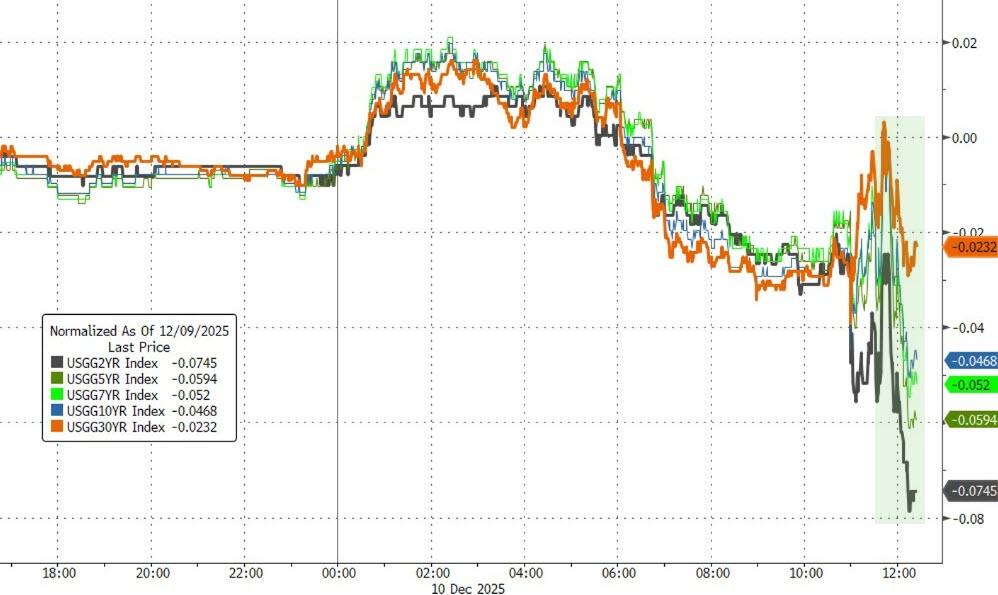
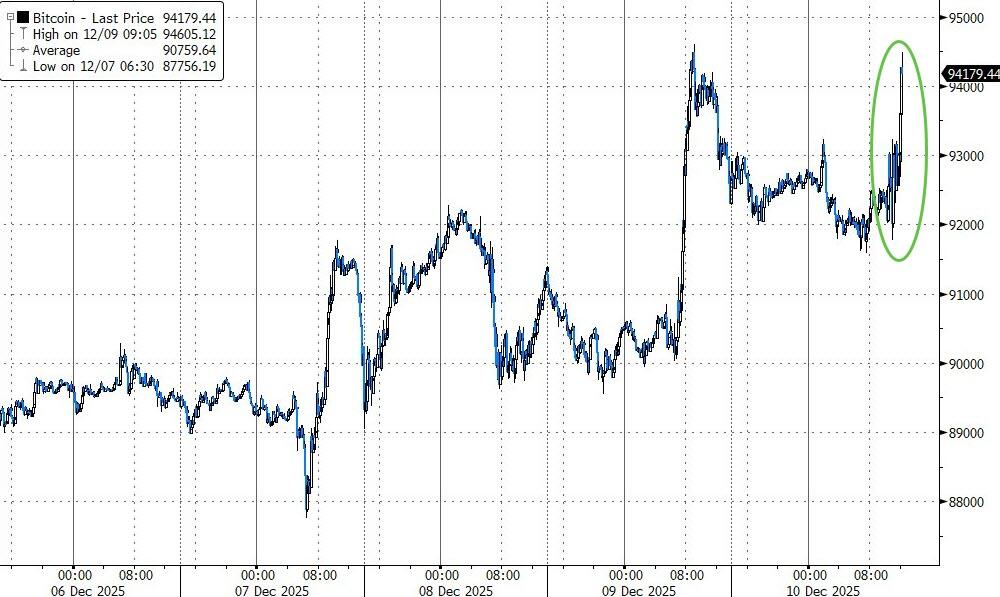
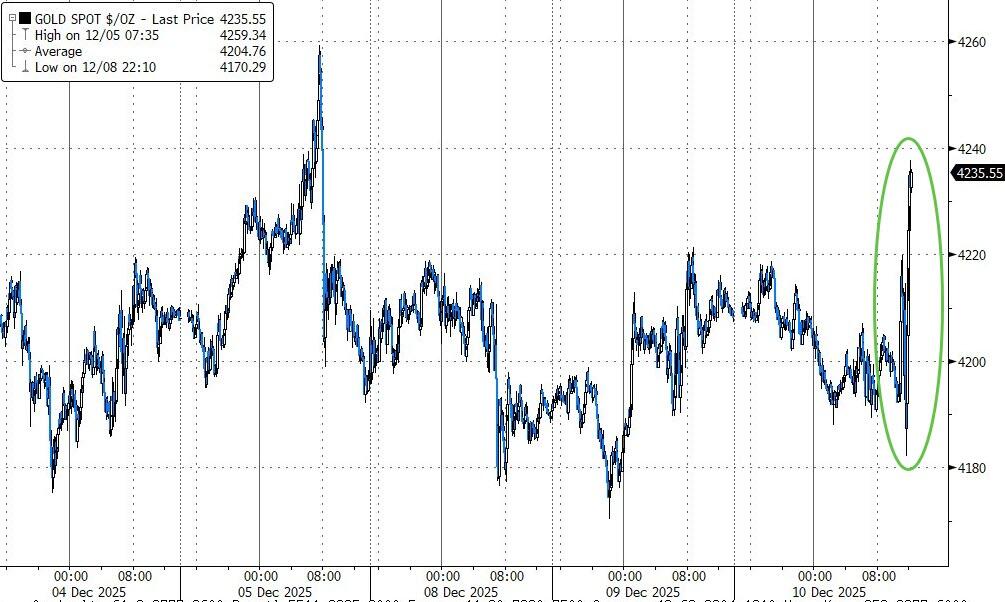
Away from equities, bond yields were mixed, Bitcoin slid to a two-week low before finding support around 85,000, and gold briefly tested Friday’s highs before pulling back to finish with a modest gain.
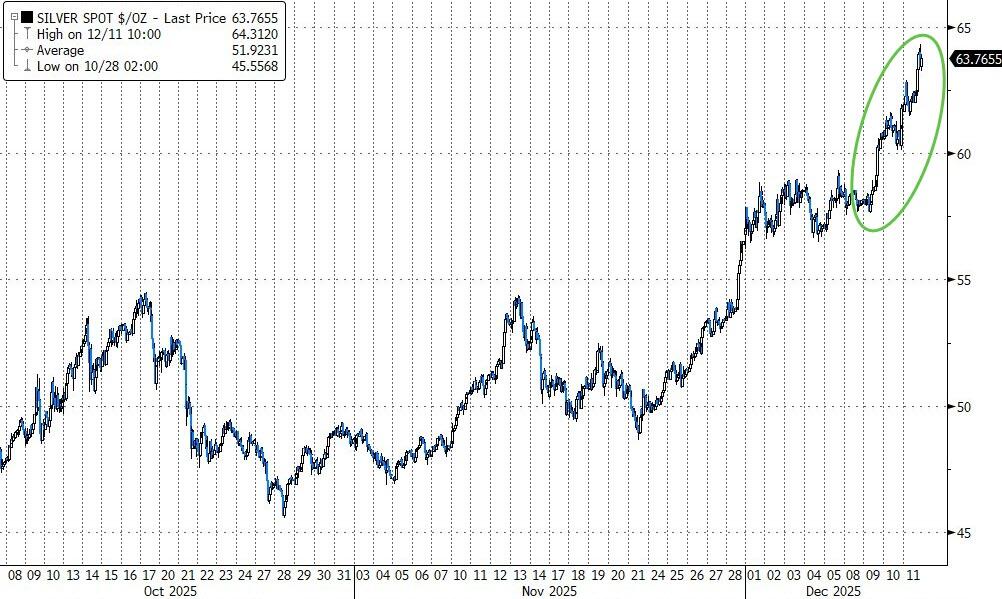
Silver ripped higher again to close above 64, and copper tacked on nearly 1%, underscoring how consistently the metals complex has helped shore up portfolios on days when stocks can’t get out of their own way.
With AI leaders stumbling, economic data back in focus, and metals quietly doing the heavy lifting, the question now is whether this is the early stage of a healthier, more diversified market—or just another pause in an AI-dominated story that comes roaring back once the next batch of headlines hits.
Read More