Sunday Musings: Marching In Sync

Ulli Uncategorized Contact


Chart courtesy of YahooFinance

Emails, along with references to articles about the impending bond bubble, keep coming. Some even suggest that now is the time to go short treasuries.

To recap, the happy trio is still marching in sync. I refer to the happy trio as being gold (GLD), the domestic stock market (VTI) and the domestic bond market (BND). Historically, these three asset classes do not move in the same direction at the same time, at least not for very long.

While gold has been referred to as a hedge against inflation in the past, more recently it has been a hedge against uncertainty and a sliding dollar in an environment supported by general deflationary tendencies.

Bonds on the other hand flourish when the economy is slowing down, or is perceived to be slowing, as interest rates fall to stimulate economic activity.

That is the time when stocks and bonds can rally in sync, but only up to a point. Once the pendulum swings the other way, and economic steam has picked up to a level where interest rates are being pushed up again, bond prices will head south.

The timing of the back and forth movement is not chiseled in stone, which is why there is some overlap before a major trend prevails again.

I think we have reached a point where something has to give. We are either in an environment of improving economic activity, which supports the stock market, or we’re not, which would be good for bonds.

The fact that the Fed is entertaining more quantitative easing via QE-2 next week is obviously a sign that the economy is lagging and not standing on its own two feet. In other words, the patient is still bedridden.

To me, that means we are at a crossroads where the stock market is hoping that QE-2 will be working so that we have justification for the current rally. On the other hand, the mere fact that the Fed feels it has to intervene can keep the bond rally going as well.

Sooner or later, only one of the two is going to be right. Either the economy recovers or it doesn’t. Alternatively, there is a good chance that it simply will sputter along for years to come.

While no one has the foresight to determine the eventual outcome, my guess is that the bond market will come out ahead as the perceived recovery will not materialize. This is not a prediction but merely my current view.

With everyone expecting a bursting of the bond bubble, is anyone considering a bursting of the current stock bubble? Remember, the recent stock rally is based on very rosy assumptions about the recovery. If they do not materialize, there is no reason for the major averages to hover around these lofty levels.

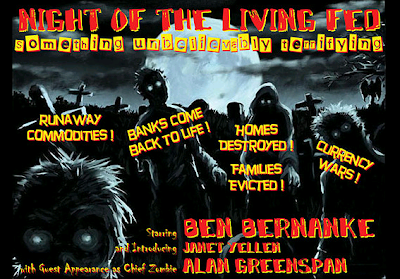
Fed Zombies

Ulli Uncategorized Contact


In case you missed it, MarketWatch reports that “Fed zombies are hungry for quantitative easing:”

The easy-money policies of Federal Reserve chairmen Ben Bernanke and Alan Greenspan have rarely impressed veteran fund manager Jeremy Grantham, but now the chief investment strategist at GMO, a Boston investment firm, is likening Fed actions to an economic horror show.
“Adhering to a policy of low rates, employing quantitative easing, deliberately stimulating asset prices, ignoring the consequences of bubbles breaking, and displaying a complete refusal to learn from experience has left Fed policy as a large net negative to the production of a healthy, stable economy with strong employment,” Grantham wrote in his latest quarterly commentary, “Night of the Living Fed.”

In a scathing indictment of the Fed, Grantham casts Bernanke as a desperate zombie whose manipulation of asset prices through lower interest rates — exacerbated by a widely expected second round of quantitative easing beginning next month — weakens not just the U.S. economy but also destabilizes currency and commodity markets.

Moreover, Grantham alleges, artificially stimulated asset prices encourages risk-taking investment behavior that can lead to asset bubbles that invariably end badly, as was the case with Internet stocks and housing.

Fed forever blowing bubbles

The Fed has been inflating asset prices as part of policy since at least the mid-1990s. The wealth effect is the primary mechanism, make people richer and they’ll spend more. So QE is there to goose asset markets. But this’ll end badly. And the next time the Fed won’t have any silver bullets left to kill recession.

In his commentary, Grantham is especially harsh with former Fed Chairman Greenspan. “The net effect of deliberately encouraging the start of asset bubbles — particularly in the case of housing — and then neglecting them and leaving them to burst, created the worst domestic and global recession since 1932,” Grantham said.

“Capitalism has been manipulated far more, and more dangerously, by the last two Republican-appointed Fed bosses than everything else added together,” Grantham added. “It is naive, if fashionable, to blame the rather current lame Administration for all of our problems. They inherited a cake already baked, or better, ‘half-baked,’ and the master bakers were the current and former Fed bosses.”

Grantham doesn’t stop there. The real victims of “Fed Manipulated Prices,” he said, are individual savers.

“When rates are artificially low, income is moved away from savers…toward borrowers,” Grantham said. “This means less income for retirees and near-retirees with conservative portfolios, and more profit opportunities for the financial industry.”

Nowhere to hide; somewhere to invest

Yet stock investors, ironically, can find hope in this bleak picture, Grantham said.

The biggest reason is that 2011 is the third year of the four-year Presidential Cycle, a historical phenomenon in which not only stocks do well, but high-risk stocks fare best of all.

In year three of the cycle, “risky, highly volatile stocks have outperformed low risk stocks by an astonishing average of 18% a year since 1964,” Grantham noted.

Plus, the third year of the last 19 cycles — over a span of almost eight decades — has not seen a serious bear market since the 1930s, and in the one year of the 19 that was down, the market lost just 2%.

Accordingly, Grantham wrote, “the line of least resistance is for the market to go up and for risk to flourish,” with the Standard & Poor’s 500-stock index possibly reaching 1500 a year from now.

“Of course, if we get up to 1400 or 1500 on the S&P;, we once again face the consequences of a badly overpriced market and overextended risk-taking,” Grantham cautioned.
…

Stocks are overpriced, but bonds are even less attractive, Grantham said. Gold, meanwhile, isn’t for serious investors, he added. “In the longer run,” he said, “resources in the ground, forestry, agriculture, common stocks and even real estate are more certain to resist any inflation or paper currency crisis than is gold.”

[My emphasis]

I agree with Grantham’s analysis of the Fed’s easy monetary policies, and the bubbles it has created. What amazes me is that the upcoming QE-2 injection is supposed to cure all that ails the economy; at least those are the expectations.

One only has to look to Japan and their two lost decades to see that stimulus in its various forms did not and never will bring about the desired results. That fact seems to have been lost on the Fed being hell-bent on doing something…

Grantham refers to the third year of the last 19 election cycles not having seen a serious bear market in almost eight decades. While that is an impressive statistic, I want to point out that we are also in unchartered territory by never having been on the back side of a real estate/credit bust of such gigantic proportions with still unknown long-term consequences.

If Grantham is right, and the S&P; 500 heads higher based on current fundamentals, the eventual pullback may very well be even more severe. It’s all a guessing game, so to me the sensible thing is to always have an exit strategy in place, such as I advocate. If you don’t, you will leave your portfolio exposed to the vagaries of the market place.

No Load Fund/ETF Tracker updated through 10/28/2010

Ulli Uncategorized Contact

My latest No Load Fund/ETF Tracker has been posted at:

http://www.successful-investment.com/newsletter-archive.php

Vacillating around the unchanged line was the theme of the week as anticipation about next week’s elections took center stage.

Our Trend Tracking Index (TTI) for domestic funds/ETFs moved above its trend line (red) by +6.13% (last week +6.52%) and remains in bullish mode.


The international index has broken above its long-term trend line by +6.99% (last week +7.21%). A new Buy signal was triggered effective 9/7/10. If you decided to participate, be sure to use my recommended sell stop discipline.


[Click on charts to enlarge]

For more details, and the latest market commentary, as well as the updated No Load Fund/ETF Tracker StatSheet, please see the above link.

Out Of The Deep Red

Ulli Uncategorized Contact


Yesterday’s market activity reminded me of the classic Clint Eastwood movie titled “The good, the bad and the ugly,” only in reverse.

The major indexes started out looking very ugly, then looked bad and ended up looking pretty good, as most of the losses were recovered by the end of the day.

Earnings misses were one reason, while disappointment with durable goods were another. Commodity prices headed south while the dollar rose.

Technically speaking, the S&P; 500 is struggling to break through the glass ceiling in the 1,184 area. But the mother of all concerns was the Fed and how big of a move it will make next week.

A WSJ story casts doubt on the magnitude of the planned QE-2 intervention. It seems like the markets have priced in a major sum, something along the lines of $2 trillion.

The story suggested it may not be a shock and awe effect as hoped for, but the amount could very well be limited to a few hundred billion dollars to start with while measuring its effect over time. That indeed would be a disappointment to the markets as much more was expected.

Again, it’s just a story, but it shows the uncertainly not only in the markets but in my view also at the Fed. We are entering unchartered territory, and no amount of monetary injection can interrupt the trend (economic slowdown) that is currently in place, and we will very likely not prevent a double dip from occurring—at least in my opinion.

It’s anybody’s guess how much volatility we’ll be seeing next week. Depending on the election outcome, there could be a huge relief rally and then a reaction to the Fed announcement.

My suggestion? Be sure you know where your sell stops are.

A Mixed Bag

Ulli Uncategorized Contact


There was nothing straight forward about yesterday’s trading session. The major indexes bobbed and weaved within a fairly narrow range but managed to close at the unchanged line to slightly up despite a weak opening.

The reason was a combination of punches thrown by the current heavyweights, the economy and earnings. While a report on home prices was disappointing, it was offset by a gain in consumer confidence. That should have pushed the markets higher, but weak earnings kept a lid on any attempts to move to a higher level.

The dollar was up, as were interest rates, while gold was down slightly and crude oil was higher just a bit. The net result translated into tiny market gains.

It appeared that investors were simply cautious ahead of next week’s double whammy: The elections and the Fed announcement regarding QE-2. Short of any unforeseen major events, I expect this slow and directionless trading to continue over the next few sessions.

G-20 Relief

Ulli Uncategorized Contact


It was a rally right from the start after yesterday’s opening with the S&P; 500 heading straight for the 1,200 level.

Support came from the G-20 meeting, which ended as all of those types of meetings end: long on talk, but short on results. I guess the positive twist was that nothing was really decided other than a call for more sustainable current-account deficits. That sent the dollar south but helped metals, gold and crude oil move higher.

After an initial jump, the major indexes slowly retreated for the remainder of the session, but managed to close up. It seemed like every attempt to higher levels was met with selling, which may have been a case of computer-generated trading as we were approaching the 1,200 milestone.

Existing home sales came in better than expected, although the median price was down from a year ago. Distressed sales, either via foreclosed homes or short sales, made up 35% of the market.

Bank stocks continued to weaken because of the continuing saga involving errors and omissions in the foreclosure paperwork. The Fed announced that it is investigating foreclosure practices, which means this ordeal is far from being over. If surprises are uncovered, there is bound to be some effect on stock market direction.