Early Selling—Late Rebound

Ulli Uncategorized Contact


Even poor economic reports were not able to keep this market subdued for any lengthy period yesterday.

A drop in the Consumer Confidence Index clearly confirms that job security, or insecurity, still contributes to a lack of spending causing this indicator to drop from 54.3 in November to 52.5 in December.

Suspicions that the housing market is still in a major struggle were confirmed by the Case-Shiller 20-city home price index, which fell 1% in October. It was its third monthly decline in a row. Year over year the index is down 0.8%.

To my way of thinking, a bottom in real estate is not even in sight yet since many areas are still priced in bubble territory. The only way we will find a true bottom in this market is when the median income in any given area supports the median price of a home. Anything else is nothing but wishful thinking.

Gold, energy and commodities had their day in the spotlight. Especially gold reacted strongly to the upside as a weak auction of 5-year Treasury notes pushed interest rates higher.

In the end, the markets inched higher again—on fairly poor news. It makes me wonder if the cause was simply low volume or whether all of Wall Street’s optimists are manning the trading computers while the pessimists are still on extended Holiday vacation.

2011 Forecasts

Ulli Uncategorized Contact


Hat tip goes to Random Roger for this link to “More Gains in 2011?”

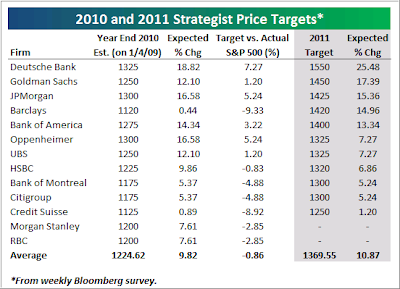
All but two of the major Wall Street firms surveyed by Bloomberg have provided their 2011 S&P; 500 price targets. And so far, every single strategist has provided a year-end (2011) price target that is higher than the S&P; 500’s current level. The consensus year-end estimate currently stands at 1,369.55, which represents a gain of just over 10% from where the S&P; is currently trading.

As shown below, Deutsche Bank has the highest 2011 year-end price target at 1,550. At 1,550, the S&P; would be just 16 points below its all-time high reached in October 2007. A return to new all-time highs by 2011 would be quite the comeback for the market. Goldman Sachs has the second highest price target at 1,450, which is 100 points below Deutsche Bank’s target. A move to 1,450 would be a gain of 17.39% from current levels. JP Morgan, Barclays, and Bank of America all see the S&P; rising to 1,400 or higher next year.

Credit Suisse currently has the lowest 2011 year-end price target at 1,250, which is just 1.20% higher than where the index is trading now. Citigroup and the Bank of Montreal are both at 1,300, HSBC is at 1,320, and UBS and Oppenheimer are both at 1,325.

At the start of 2010, the consensus year-end price target was 1,224.62 for the S&P; 500, which is just 10 points below where the index is currently trading. Barring a big move higher or lower in the last two weeks of the year, the strategists collectively will have been pretty good prognosticators in 2010. Don’t hold your breath for a repeat performance, however.

Since no one has the ability to look into the future, forecasting is simply a hit or miss proposition, although on average, the group above did very well for 2010.

While the average forecast for 2011 of +10.87% for the S&P; 500 is certainly a possibility, much depends on the unknown events that suddenly could have the markets run into a brick wall and reverse their trends.

Domestic events could include continued budget and underfunded pension problems on every level government and subsequent defaults and bankruptcy filings along with massive layoffs.

Globally, real estate/credit bubbles in China, Australia and Canada may finally play themselves out along the lines of what we’ve seen in 2008. Additionally, China’s overheating economy may be forced into slowdown mode to contain inflation, which will affect global trade for sure and will have an impact on the U.S. as well.

Europe will continue to struggle with the debt issues of its Euro zone member countries, and I would not be surprised to see the first default occurring at some point during the next year. That would likely cause a domino effect.

While any of these possibilities could derail the U.S. market, the question remains as to whether the impact will be only a temporary pullback, or a trend reversal back into bear market territory. It all depends on the magnitude of the event or if several of them are occurring simultaneously.

It pays to be prepared for either outcome by focusing on the direction of my Trend Tracking Indexes (TTIs) along with those of the major indexes. Using these in combination with my recommended exit strategy will give you not only piece of mind but also a plan as to how to deal with market adversity.

Merry Christmas

Ulli Uncategorized Contact

I would like to extend my best wishes for a safe and happy Holiday season to you and your family. I will be taking a couple of days off but will be back on the regular posting schedule as of Monday.

No Load Fund/ETF Tracker updated through 12/23/2010

Ulli Uncategorized Contact

My latest No Load Fund/ETF Tracker has been posted at:

http://www.successful-investment.com/newsletter-archive.php

The major indexes managed to add another 1% to this month’s tally.

Our Trend Tracking Index (TTI) for domestic funds/ETFs has moved above its trend line (red) by +5.25% (last week +5.26%) and remains in bullish mode.


The international index has broken above its long-term trend line by +7.17% (last week +6.46%). A new Buy signal was triggered effective 9/7/10. If you decided to participate, be sure to use my recommended sell stop discipline.


[Click on charts to enlarge]

For more details, and the latest market commentary, as well as the updated No Load Fund/ETF Tracker StatSheet, please see the above link.

Snaking Higher

Ulli Uncategorized Contact


Right now, it appears that nothing can seem to end the persistent climbing of the major indexes. Yesterday was no exception as the markets ended up higher by a few points.

Energy and utilities provided a boost along with better-than-expected existing home sales for November. Of course, oil rising above $90/barrel for the first time in 2 years can hardly be a considered a positive. Neither can be an anemic GDP growth of 2.6% annualized for the quarter.

None of this appears to matter to the markets as confidence seems to have increased that 2011 will be a much better year economically speaking, which is expected to support higher stock prices.

The big neutralizer will be the stubbornly high unemployment rate despite stronger numbers in manufacturing along with elevated consumer spending. To me, real estate will continue its downward spiral for the simple reason that we’re stuck with this high unemployment number. After all, last time I checked, people buy houses and make mortgage payments with monies earned from real jobs and not from unemployment benefits.

How these positives and negatives will play out next year is anyone’s guess. Stay on top of the trends so you can easily spot reversals and take evasive action via your sell stops, which will help to protect your portfolio from extreme downside risk.

Holiday Cheers

Ulli Uncategorized Contact


Three things got the markets going early on yesterday. For one, there was some sigh of relief that dangers of another Korean shootout were laid to rest, at least for the time being. Second, rumor had it that N. Korea was showing willingness to let the United Nations inspectors monitor its nuclear program.

Third, but not least, in regards to the European debt crisis, Chinese Vice Premier Qishan said that the nation would “back measures aimed at stabilizing European counties struggling with debt.” At least for this moment in time, global issues were not on traders’ minds.

The markets inched higher and never looked back. My plan to liquidate one of our country ETFs did not work out as the emerging markets staged a nice rebound rally after seeming to have stalled for the past few weeks. For the time being, we will hold on to this position subject to our sell stop rules.

All major indexes have climbed to some pretty lofty levels when looking at the percentages they have moved above their respective trend lines. The S&P; 500, for example, has now reached a point that is 9.8% above its 200-day moving average. Last time this happened was in late April prior to the market heading sharply south and surrendering some 15% by early July.

I am not suggesting that a repeat is imminent, but I am saying that, based on emails from and phone calls with readers, some investor complacency has definitely set in again. It is for certain that the markets will correct again, we just don’t know the timing and magnitude of it.

Simply be aware and make sure you have your exit strategy planned and in place, so you don’t panic when the next correction strikes.