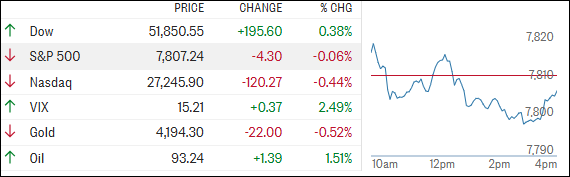
[Chart courtesy of MarketWatch.com]
- Moving the market
The market started the week with a split personality.
The Dow managed to stay in positive territory, helped by a strong move in Salesforce after a favorable analyst upgrade, while the S&P 500 and Nasdaq drifted lower as investors looked ahead to a packed week of earnings reports and inflation data.
Tech was a mixed bag. Micron weighed on the Nasdaq after concerns emerged about growing competition from China’s CXMT, but the broader AI story remains intact.
In fact, expectations for another strong earnings season continue to underpin investor optimism. As always, though, what executives say about demand, costs, and the road ahead may matter more than the numbers they report.
Geopolitics also kept traders on their toes. Oil climbed roughly 2% as fresh tensions in the Middle East overshadowed talk of a Russia-Ukraine energy ceasefire. It seems every diplomatic headline now comes with a sequel before the credits even roll.
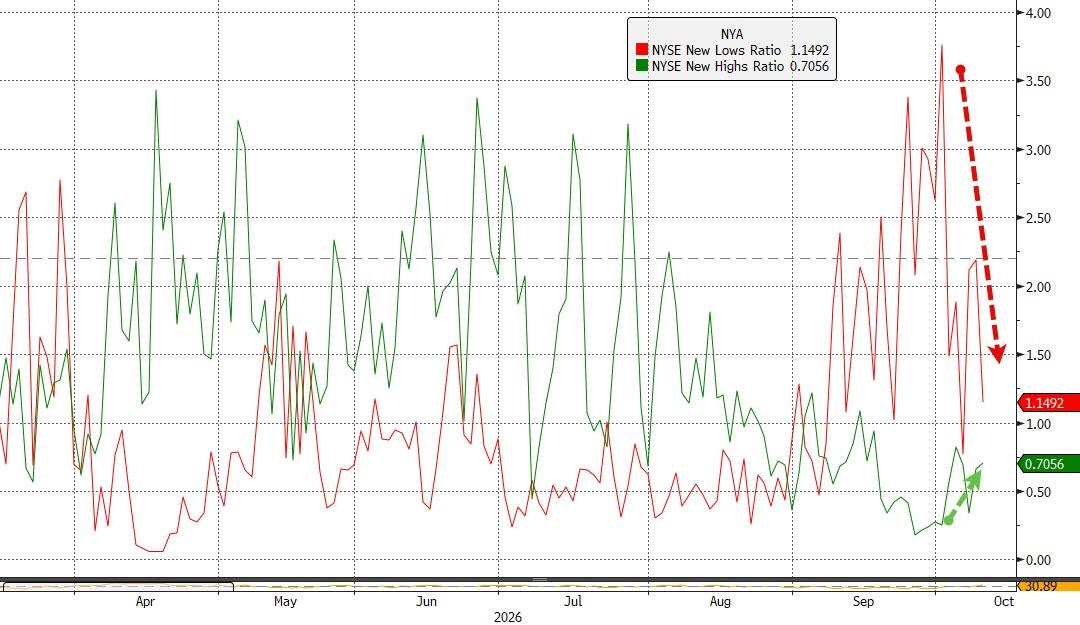
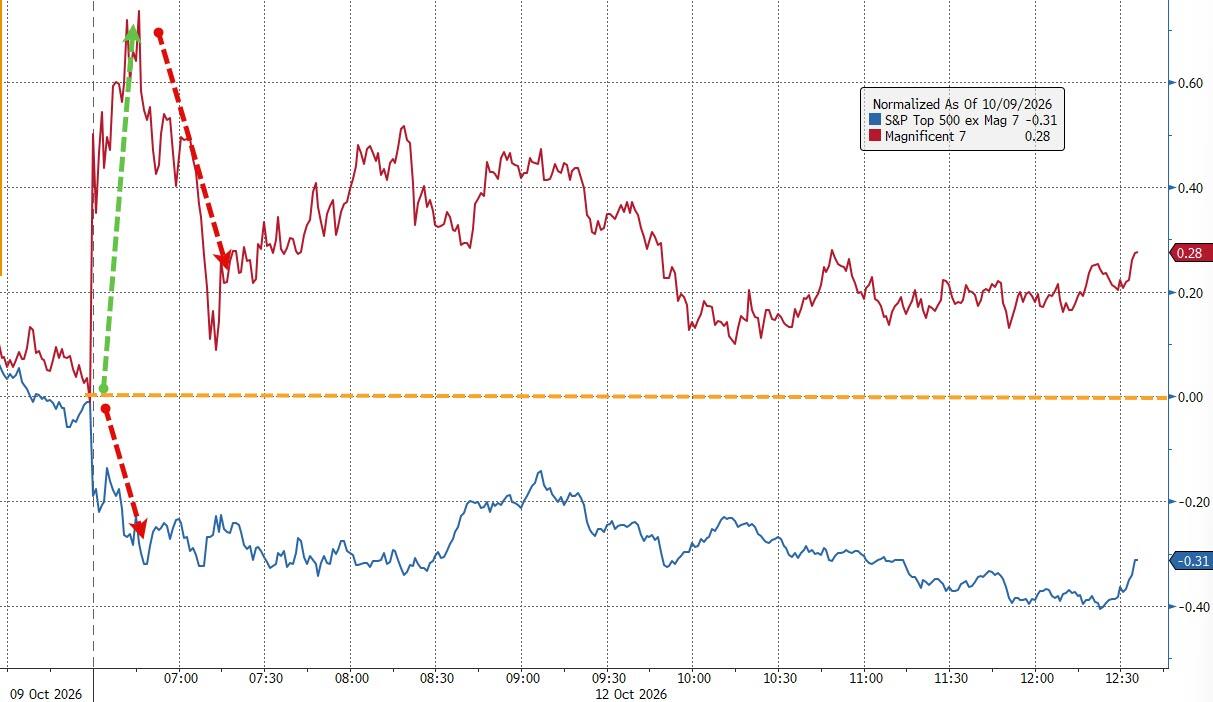
Under the surface, market breadth actually improved, the Magnificent Seven outperformed the other 493 members of the S&P 500, and the dollar climbed to its highest level since May 2025.
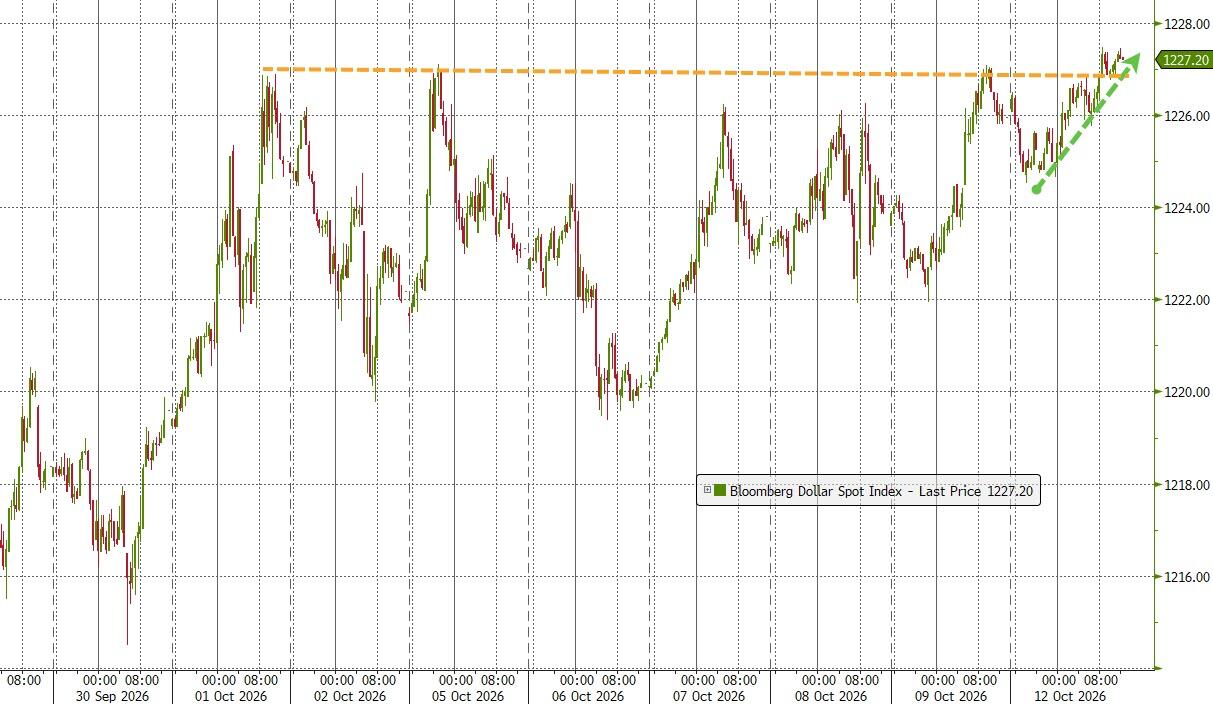
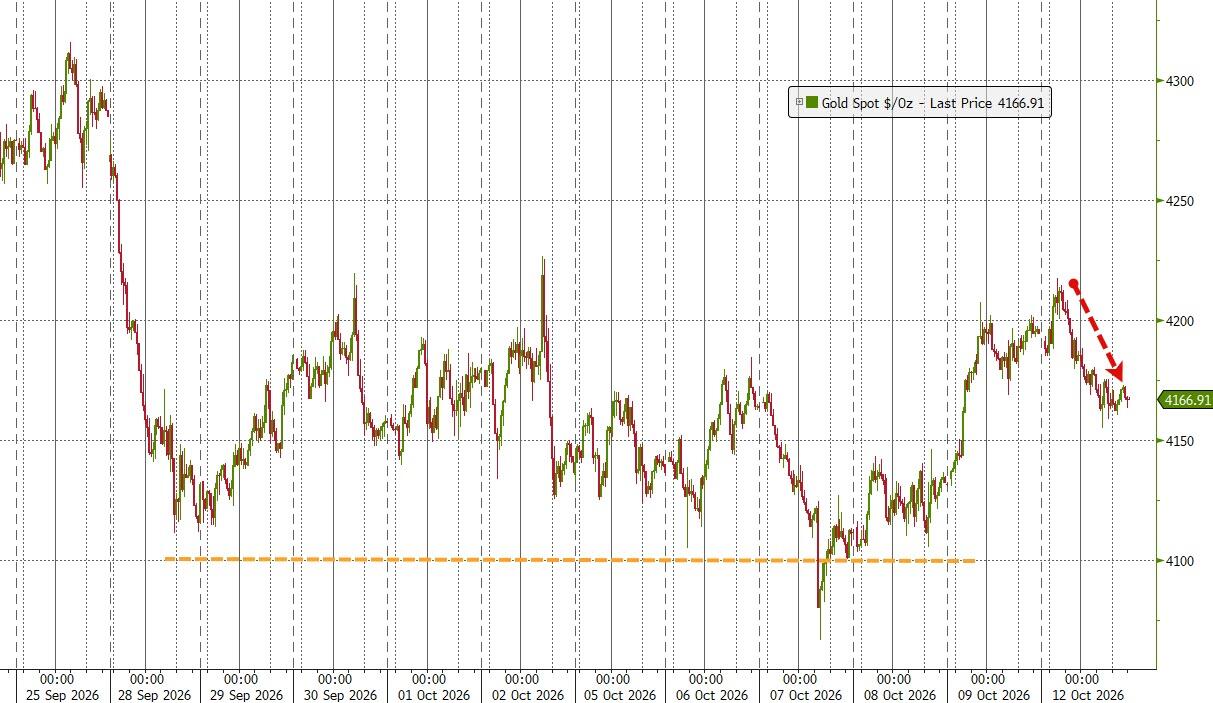
Gold felt the pressure from the stronger dollar, while Bitcoin’s weekend rally fizzled just enough to end little changed from Friday.
Perhaps the most interesting development was the lack of participation. Trading volume was exceptionally light, reaching levels rarely seen outside holiday periods.
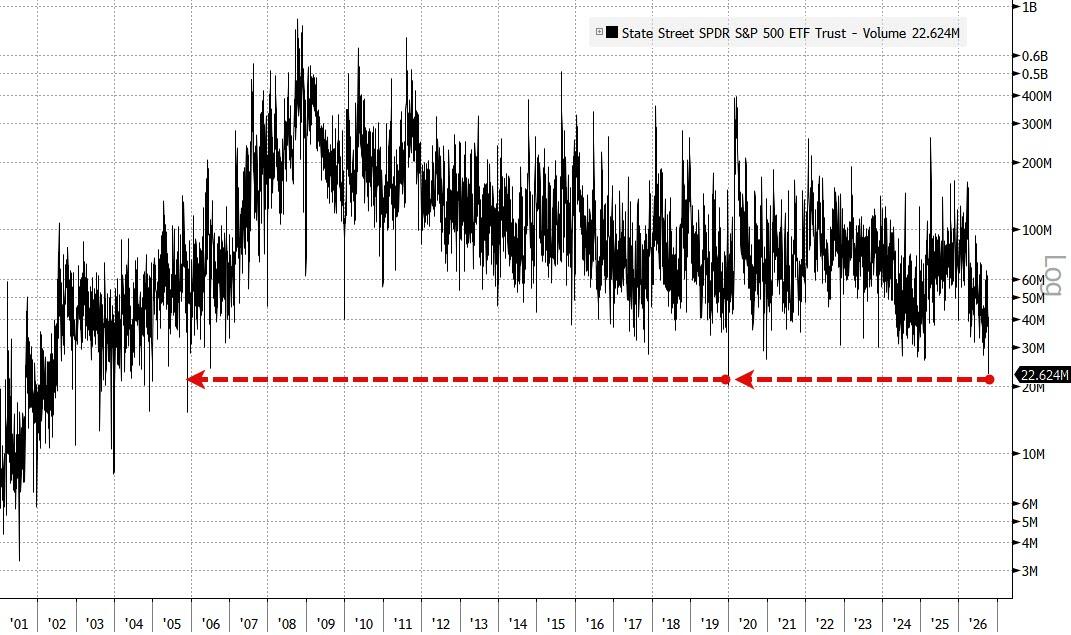
Is this simply traders catching their breath ahead of earnings season, or an early sign of investor fatigue?
2. Current domestic “Buy” Cycle (effective 5/20/2025); International “Buy” Cycle (effective 5/8/25)
Our domestic bullish cycle that began on November 21, 2023, concluded on April 3, 2025, following a market downturn triggered by President Trump’s tariff policy announcement.
This development caused significant declines across major indexes and broader market indices. However, markets subsequently rebounded, culminating in a new domestic “Buy” signal taking effect May 20, 2025.
Concurrently, our International Trend Tracking Index (TTI) experienced parallel volatility. On April 4, 2025, it breached critical thresholds, prompting a “Sell” recommendation. This position reversed as global markets recovered, with the International TTI regaining sufficient momentum to issue a new “Buy” signal effective May 8, 2025.
3. Trend Tracking Indexes (TTIs)
The Dow managed to sneak out a gain today, while most of the market drifted modestly lower.
Gold and silver took a step back, but copper decided not to follow the crowd and posted a solid advance.
Our domestic TTI was essentially unchanged, while the international model finished in positive territory.
Overall, it was a fairly quiet session, likely helped by the bond market taking Columbus Day off and leaving equities without their usual dance partner.
This is how we closed 10/12/2026:
Domestic TTI: +3.65% above its M/A (prior close +3.58%)—Buy signal effective 5/20/25.
International TTI: +2.89% above its M/A (prior close +2.65%)—Buy signal effective 5/8/25.
All linked charts above are courtesy of Bloomberg via ZeroHedge.
———————————————————-
WOULD YOU LIKE TO HAVE YOUR INVESTMENTS PROFESSIONALLY MANAGED?
Do you have the time to follow our investment plans yourself? If you are a busy professional who would like to have his portfolio managed using our methodology, please contact me directly to get more details.
Contact Ulli