Market Indexes Slip On Uncertainty; Will The Fed/ECB Deliver?

Ulli Market Commentary Contact

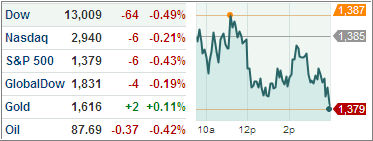
[Chart courtesy of MarketWatch.com]

Uncertainty and a certain amount of nervousness among traders provided the background for the day, as the major indexes all slid into the end of the month.

There was not much propping up going on as today proved to be a repeat of yesterday’s theme with the indexes hovering slightly above and below the unchanged line.

On the economic side, personal income increased greater than expected while spending was unchanged and consumer confidence surprised to the upside. Summer vacations and the Olympic Games contributed to a lackluster day.

However, this current lull could change in a hurry as all eyes are feasted first on Wednesday’s Fed meeting along with the European Central Bank powow, which is to be followed on Friday by the mother of all economic reports, namely the unemployment figures.

Read More

US Equities Stall After Two-Day Rally; UNG Bursts, KWT Fades

Ulli Market Commentary Contact

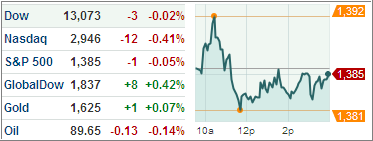
[Chart courtesy of MarketWatch.com]

US equities remained just about flat with a slight negative bias today, snapping a two-day winning streak as investors chose to hold back ahead of the central bank meetings and monthly jobs report later this week.

The Dow Jones Industrial Average (DJIA) lost 3 points, with the index’s heaviest component JP Morgan Chase (JPM) leading the decliners, slipping 2 percent after Deutsche Bank downgraded it to ‘hold’ from ‘buy’, citing lofty earnings estimates. 16 of the Dow’s 30 components ended in red as the overall breadth turned negative.

After three successive up sessions, the S&P 500 Index (SPX) closed fractionally lower, slipping less than 1 point  with healthcare dropping the most among its 10 business sectors. Telecommunications emerged the day’s biggest percentage gainer.

US Treasuries rose as risk sentiment turned sour amid rumors the probable peripheral bond purchase by the European Central Bank may not be sufficient to halt the current sovereign debt crisis. No surpise there, as this announcement last week was nothing but hot air to begin with since it did not have the support of paymaster Germany.

Read More

ETFs/Mutual Funds On The Cutline – Updated Through 7/27/2012

Ulli ETFs on the Cutline Contact

Below are the latest ETF Cutline reports, which show how far above or below their respective long-term trend lines (39 week SMA) my currently tracked ETFs/MFs are positioned.

The first report covers the ETF Master List from Thursday’s StatSheet and includes 398 ETFs, of which currently 265 (last week 224) of them are hovering in bullish territory.

The second report includes only High Volume ETFs. To clarify, High Volume (HV) ETFs are defined as those with an average daily volume of $10 million or higher.

These ETFs are generated from my selected list of some 93 that I use in my advisor practice. It cuts out the “noise,” which simply means it eliminates those ETFs that I would never buy because of their volume limitations. 48 ETFs (last week 41) have managed to remain in bullish territory after the recent market volatility.

The third report covers Mutual Funds on the Cutline. There are currently 690 (last week 578) above the line and 171 below it out of the 861 that I follow.

Take a look:

1. ETF Master Cutline Report

2. ETF High Volume Cutline Report

3. MF Cutline Report

In case you are not familiar with some of the terminology used in the reports, please read the Glossary of Terms.

Last Week In Review: ETF News And Blog Posts To 7/29/2012

Ulli Market Review Contact

In case you missed it, here’s a summary of the ETF topics and market reviews I posted to my blog during the week ending on 7/29/2012.

It was a tale of two markets. The first three days, the bears were in firm control only to be pushed aside by sudden bullish sentiment thanks to well timed jawboning by ECB president Draghi.

As a result, initial losses reversed, and the major indexes closed the week to the upside. Again, it’s important to note that none of what ails Europe has been resolved, but merely old ideas have been put back on the news front burner assuring the bulls that all will be fine and no stone will be left unturned to guarantee the EU survival.

Of course, we’ve all heard this before, which means that after the initial euphoria wears off, the major indexes will shift into retreat mode. QE hopes anywhere you look are enough these days to lift markets. For how long and how far that is the unknown question.

Over past week, we covered the following:

Read More

Will The US Q2 GDP Number Trigger Another Round Of Quantitative Easing?

Ulli Market Commentary Contact

Friday’s GDP growth number may not be the best, but it’s still much better than the European nations, particularly when compared to the horrible UK number that we saw this week, says Peter Dixon, global equities economist at Commerzbank AG in London.

The economy clearly shows a downside risk since growth momentum slowed down to 1.5 percent in Q2 from 1.9 percent in Q1, but 12 consecutive up quarters show the US economy has been resilient, though it may not be entirely insulated from the European shocks.

It will probably be a little early for the Fed to step in with another round of stimulus measures next week, says Peter, since a much more significant weakening of the economy will possibly convince all FOMC members to vote for another round of QE. However, by mid-September we can expect another round of asset purchases if things don’t improve.

Reacting to European Central Bank President Mario Draghi’s Thursday pledge on preserving the euro, Peter said what Draghi meant may not be in sync with what the European politicians have in mind. Draghi may have meant haircuts for private investors and higher inflation in the region to devaluate Spanish and Italian debt, while politicians may take a very different view on the matter.

Read More

New ETFs On The Block: Powershares DWA Small Cap Technical Leaders Portfolio (DWAS)

Ulli Small Cap ETFs Contact

Aligning with the latest trend of fund launches that that focuses on smaller issuers, Invesco PowerShares joined the wave by launching the DWA Small Cap Technical Leaders Portfolio (DWAS) last week. The latest offering from the ETF powerhouse comes after a brief hiatus of five months but helps the company expand into more niche segments.

DWAS follows the Dorsey Wright Small Cap Technical Leaders Index (the underlying index) that tracks small companies with powerful relative strength characteristics. The securities for the Index are shortlisted based a proprietary selection methodology that identifies companies demonstrating relative strength characteristics.

Relative strength characteristics are determined by the Index Provider based on the firm’s market performance compared to other companies. Research has shown relative strength can be a powerful indicator of future performance and the previous relative strength funds from PowerShares have all outperformed markets.

The Underlying Index contains approximately 200 companies from a small-cap universe of approximately 2,000 of the smallest US companies that are chosen from a broader set of 3,000 companies. The index is rebalanced and reconstructed on quarterly basis.

The DWAS portfolio is well diversified with 200 individual holdings and is relatively balanced with the top 10 holdings aggregating just 15 percent of total assets under management.

The fund seeks to invest at least 90 percent of assets in small-cap equities, strictly in accordance with the guidelines specified by the index provider. However, DWAS may invest more than 25 percent of net assets in one single firm or groups of companies only to the extent that the underlying index reflects, thus increasing concentration risk.

Read More