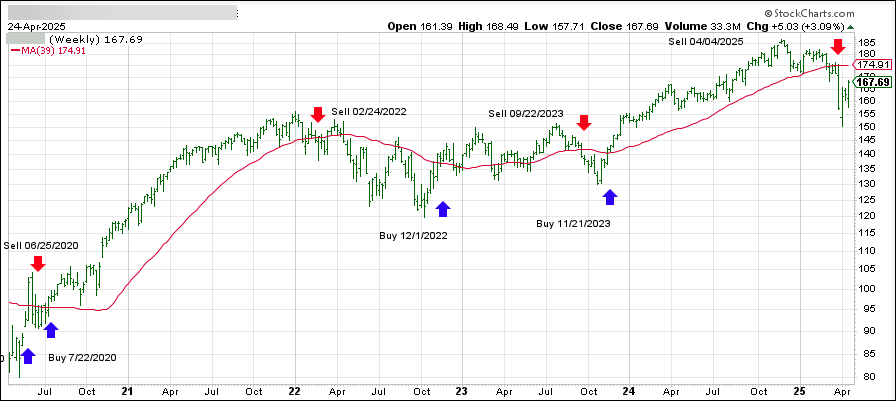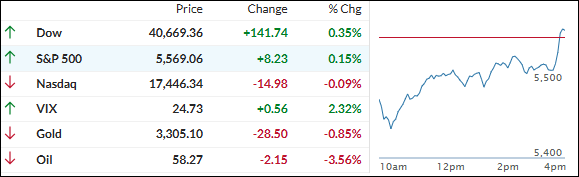
[Chart courtesy of MarketWatch.com]
- Moving the market
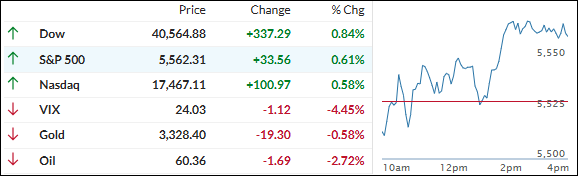
An early stumble interrupted April’s comeback rally as bad news about the U.S. economy pulled the markets down.
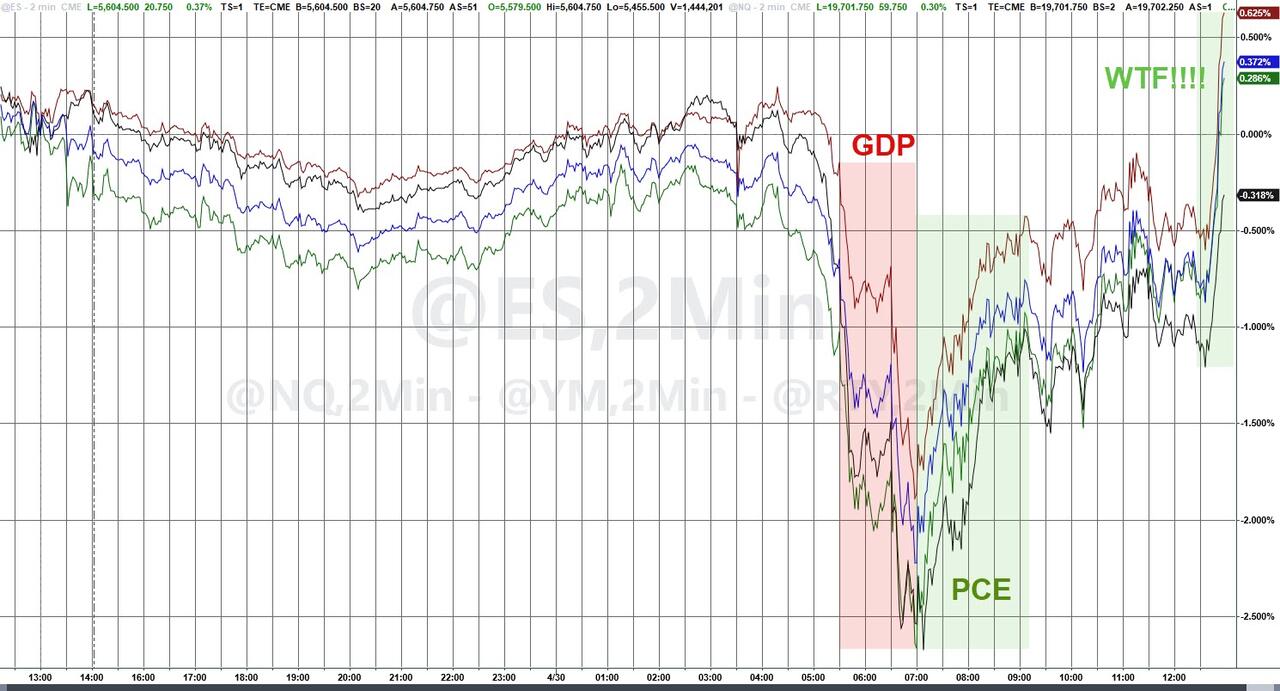
First-quarter GDP declined by 0.3%, a sharp reversal from the 2.4% increase in the fourth quarter. The Commerce Department report also showed a slowdown in consumer spending and a decline in government spending, the latter being a result of DOGE cuts.
A separate private payroll report from ADP signaled a slowdown in that sector, with private payrolls in April growing by only 62,000, well below the estimated 120,000. This dampened bullish sentiment, which had pulled the S&P 500 out of an 11% tailspin, leaving the index down only around 1% for the month.
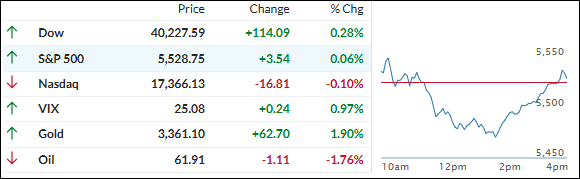
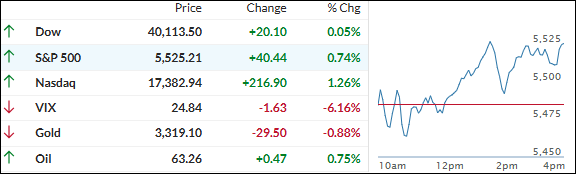
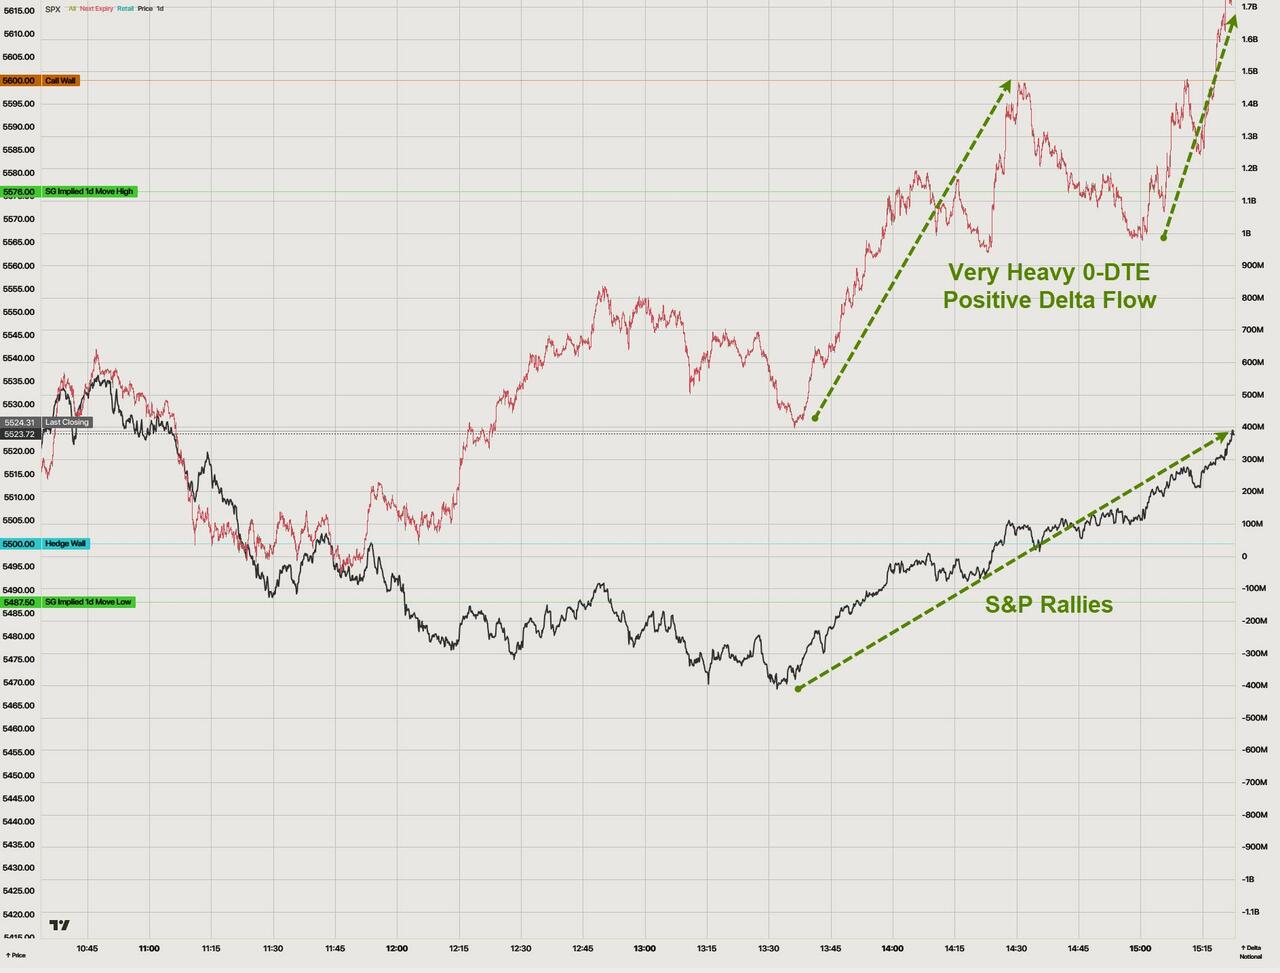
In the end, the Dow, and the S&P 500 managed to crawl back out of their early hole to close slightly in the green, helped by a last-hour melt-up. It was a choppy end to a choppy month, described by ZH as a 16% peak-to-trough drawdown followed by an 18% rally in the last few weeks.
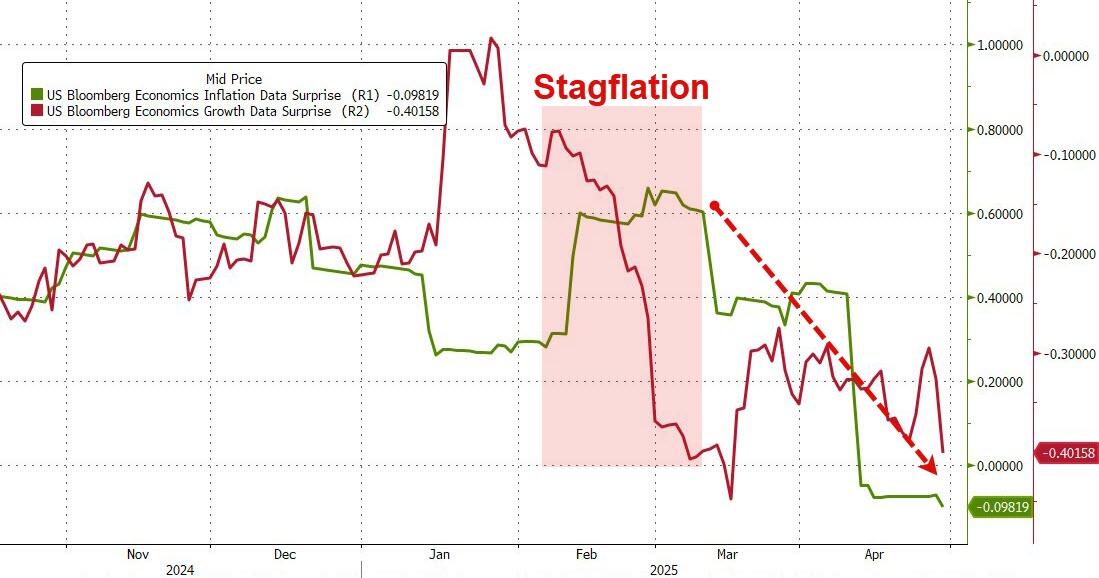
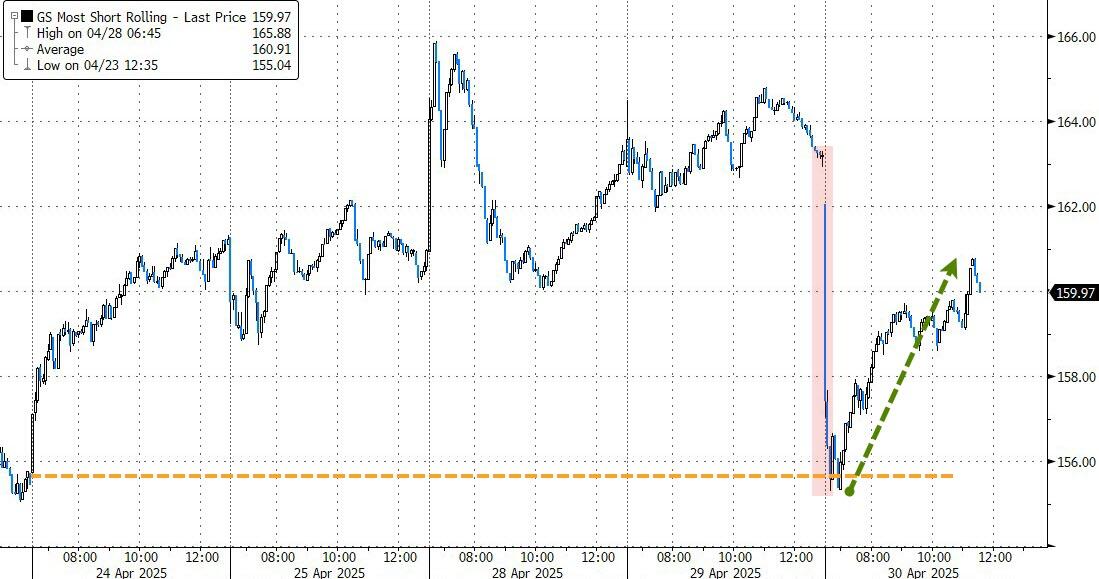
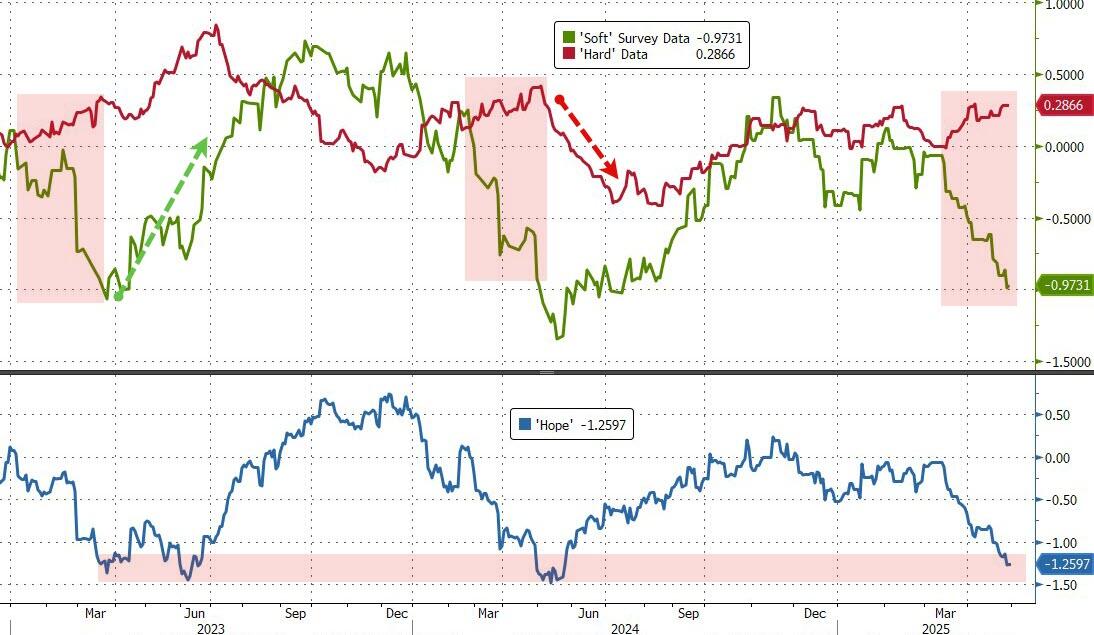
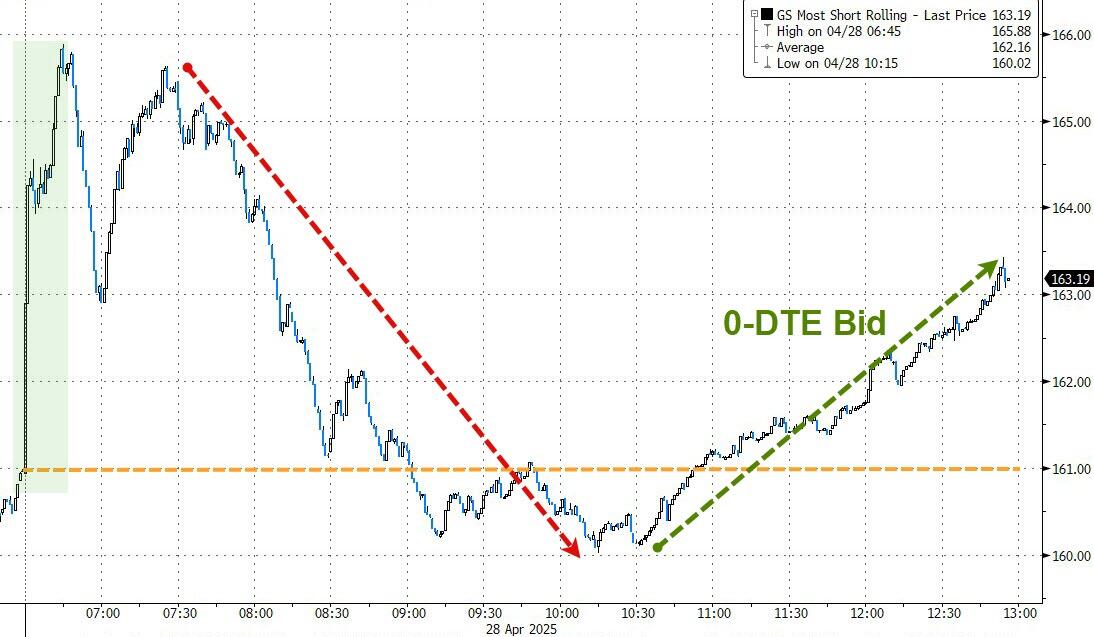
Growth and inflation data surprised to the downside, pushing the much-feared stagflation scenario to the back burner, at least for now. The most shorted stocks dumped after the opening but were squeezed higher as dip buyers stepped in.
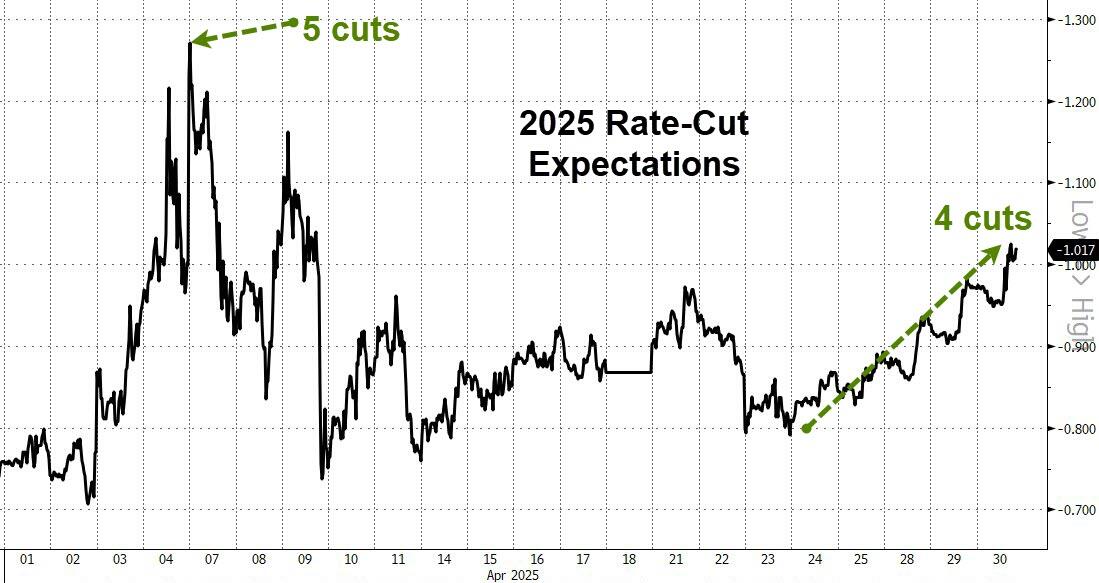
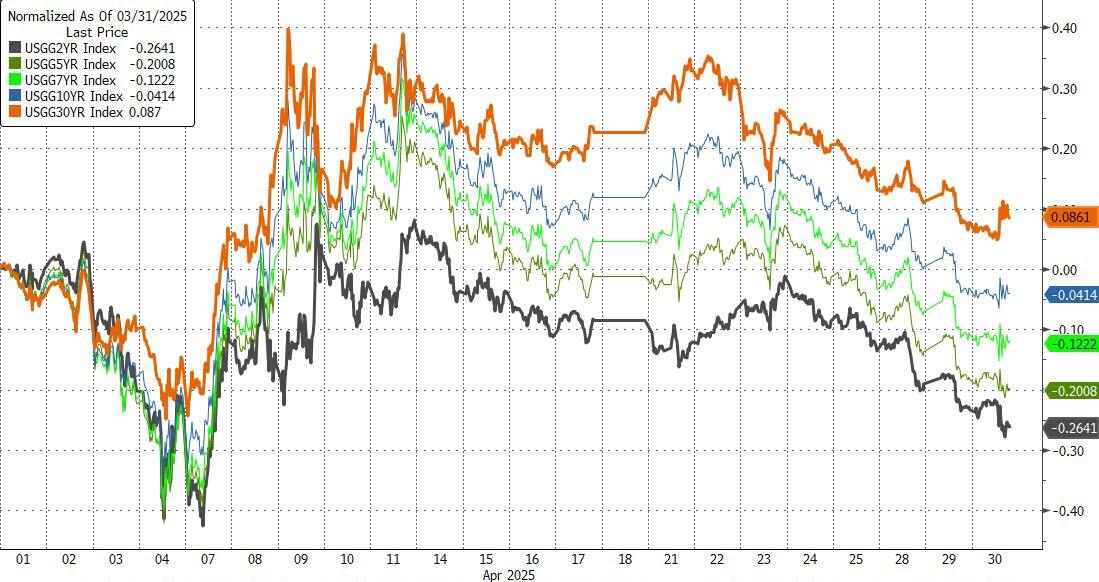
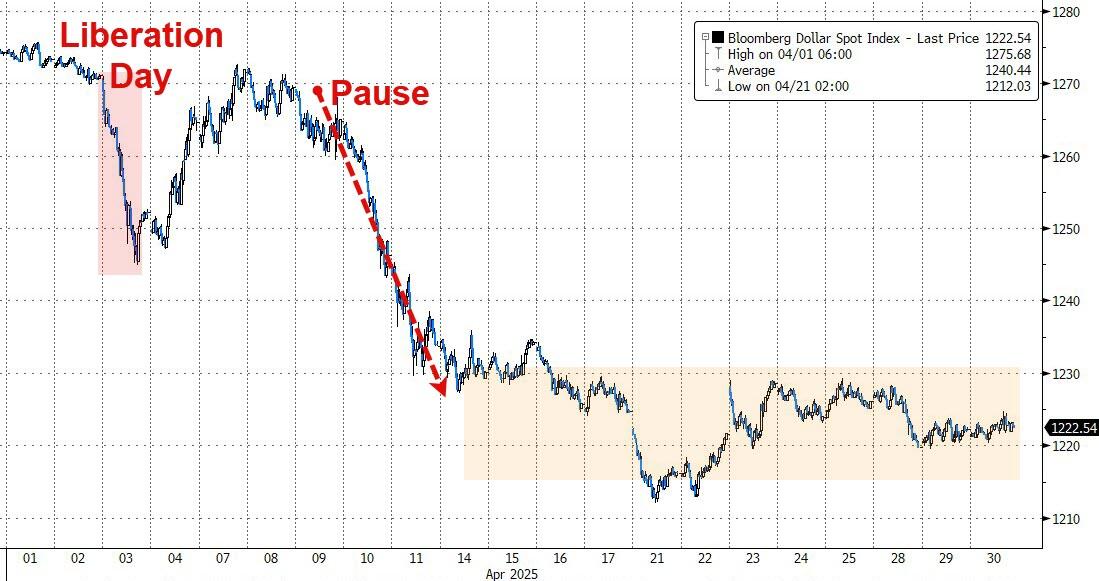
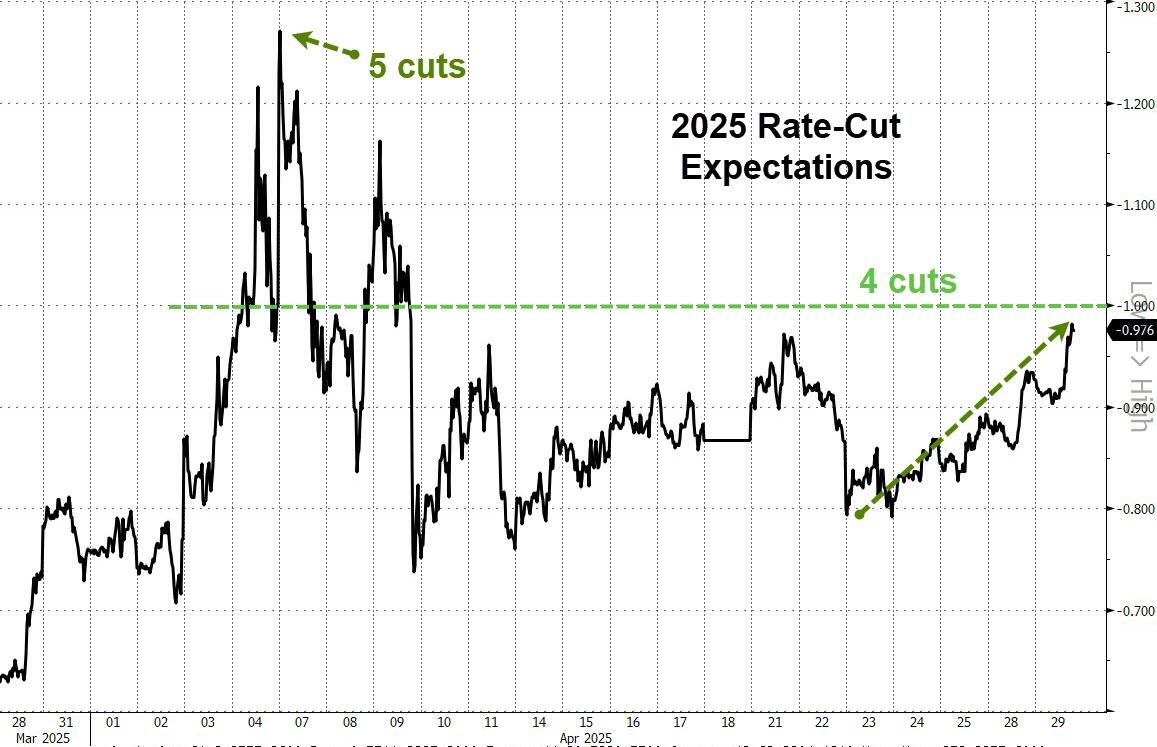
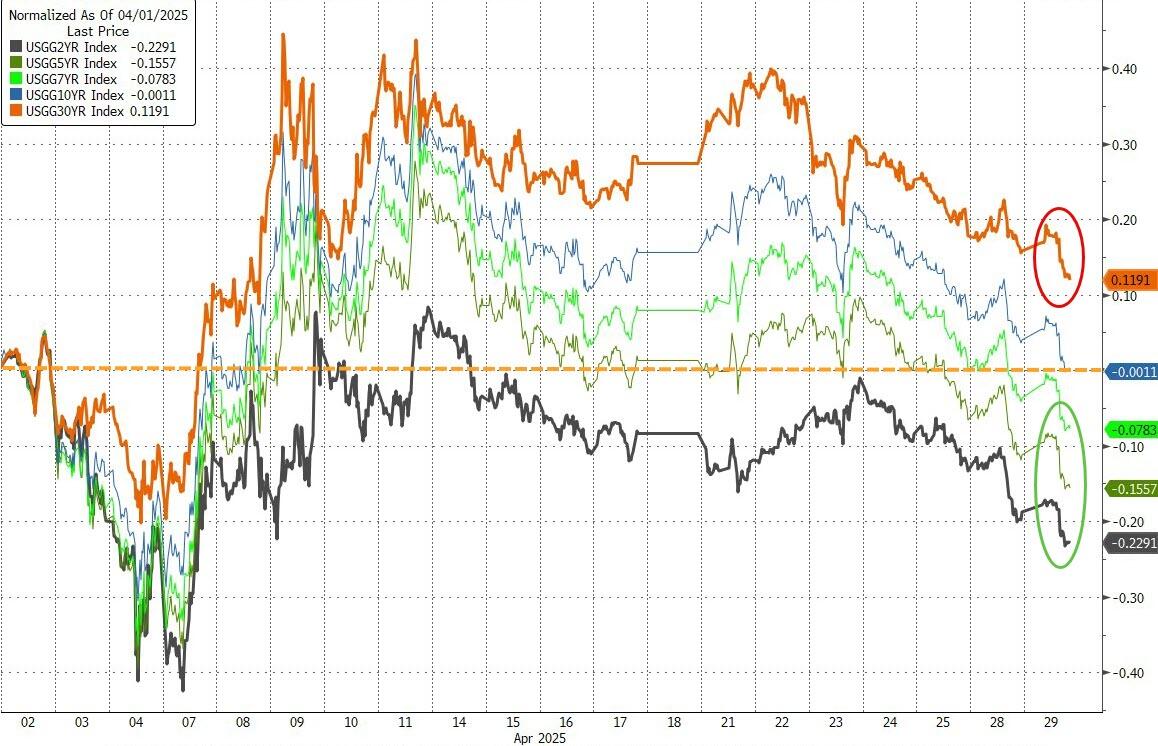
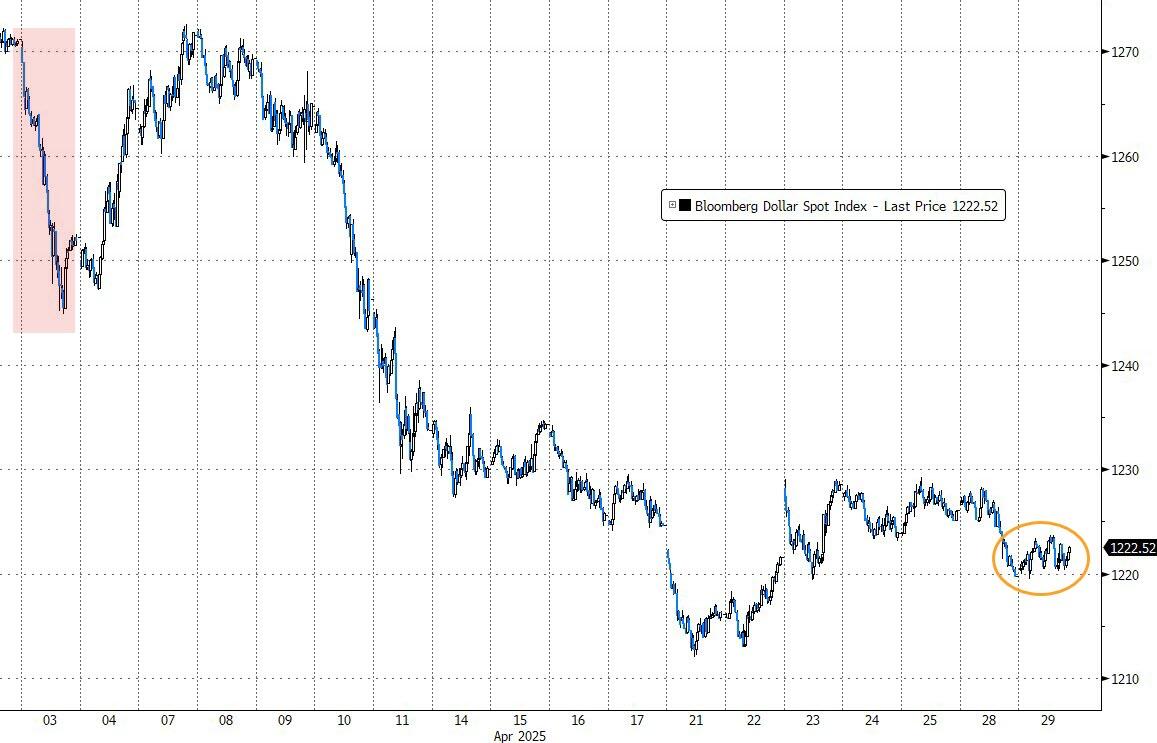
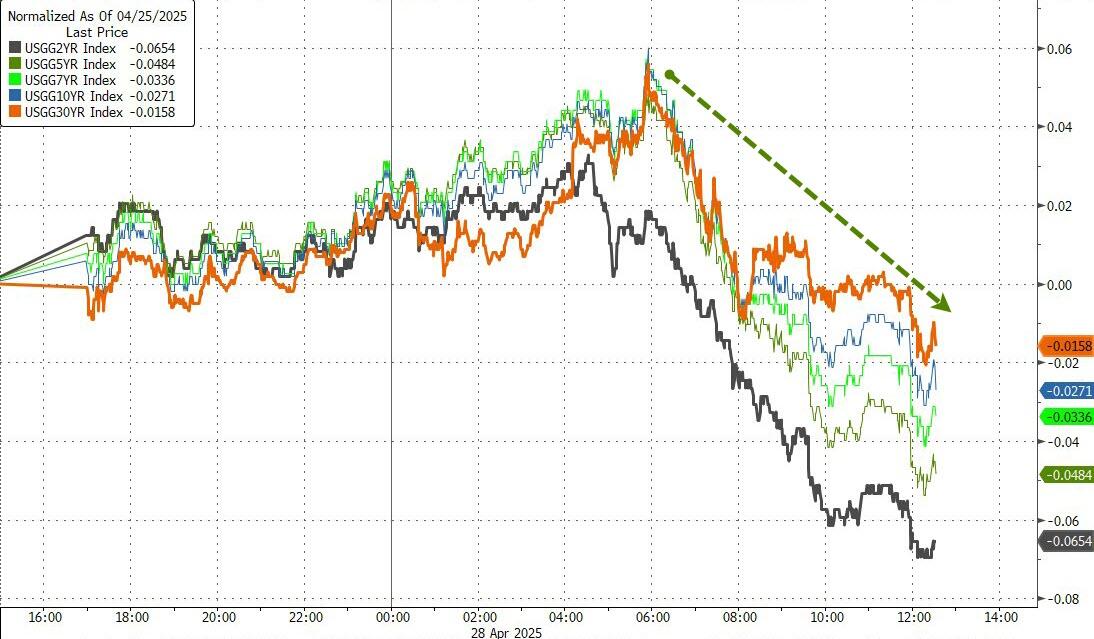
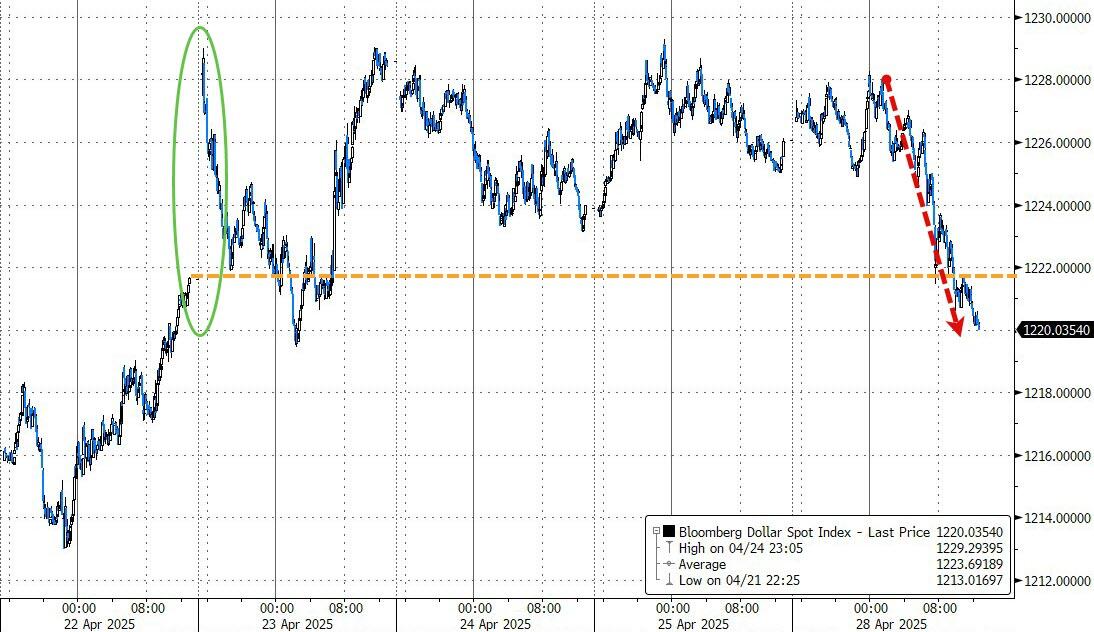
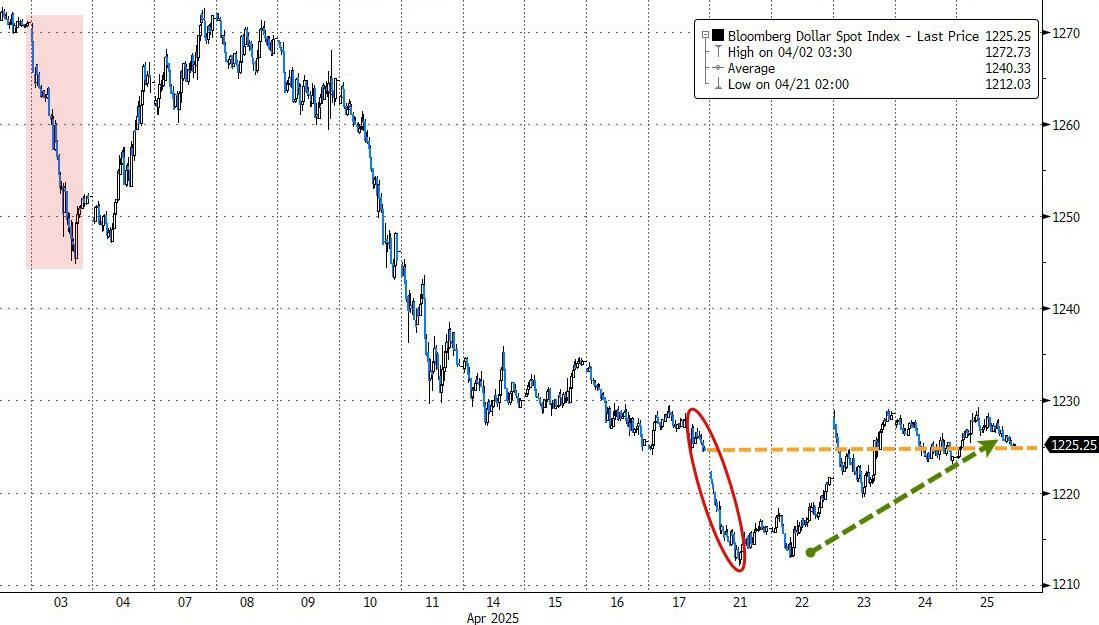
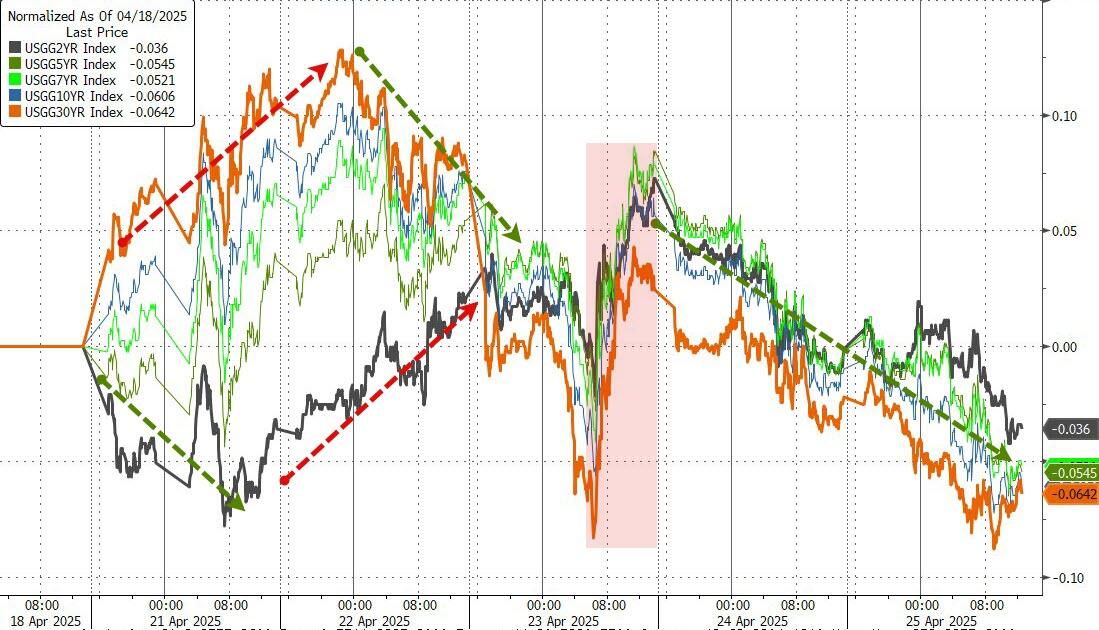
With weak macro data, it came as no surprise that rate-cut expectations surged while bond yields slipped. The dollar dropped over 4% during April, its worst performance since November 2022.
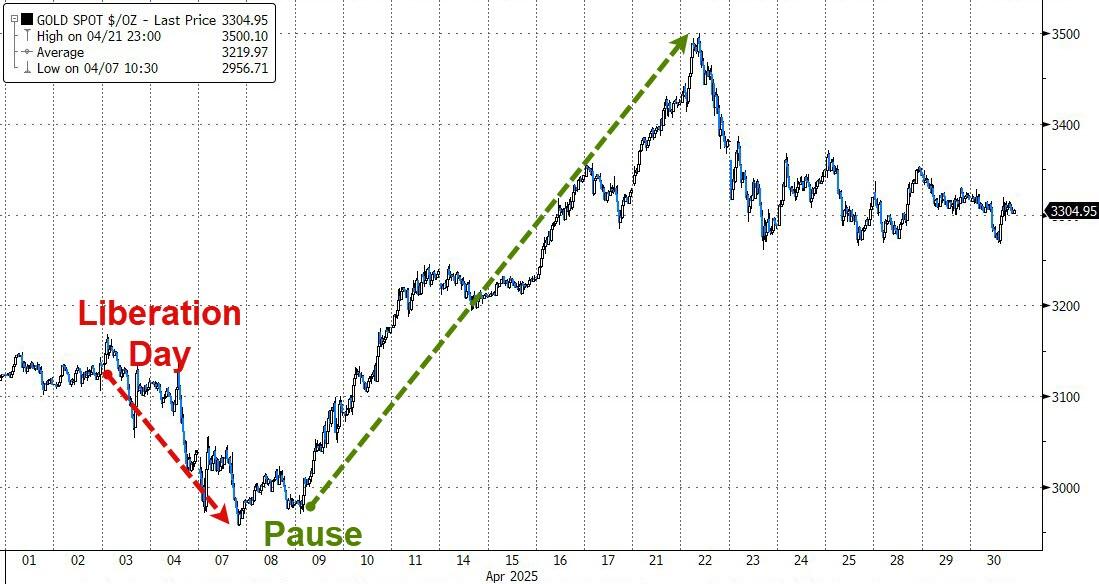
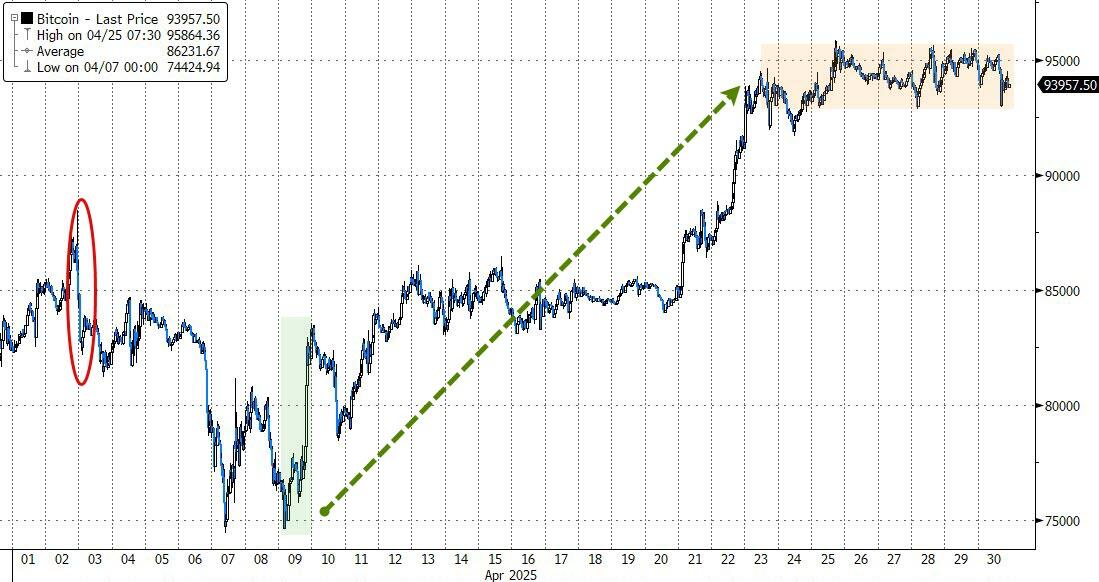
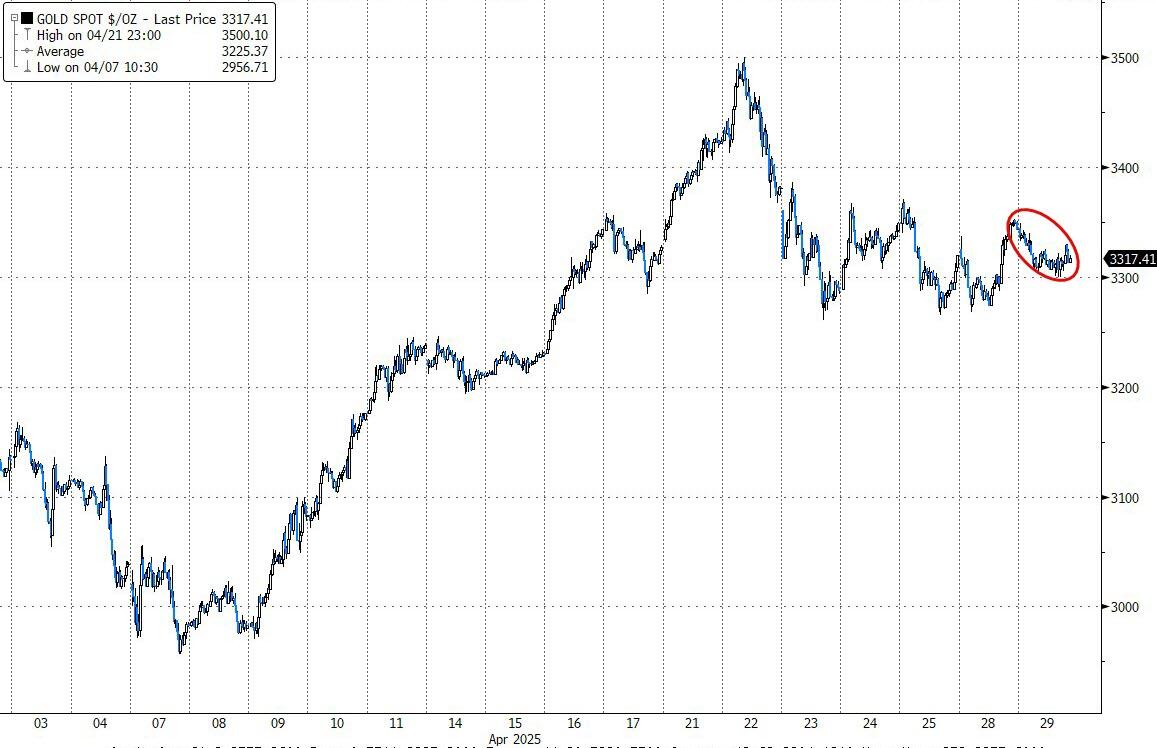
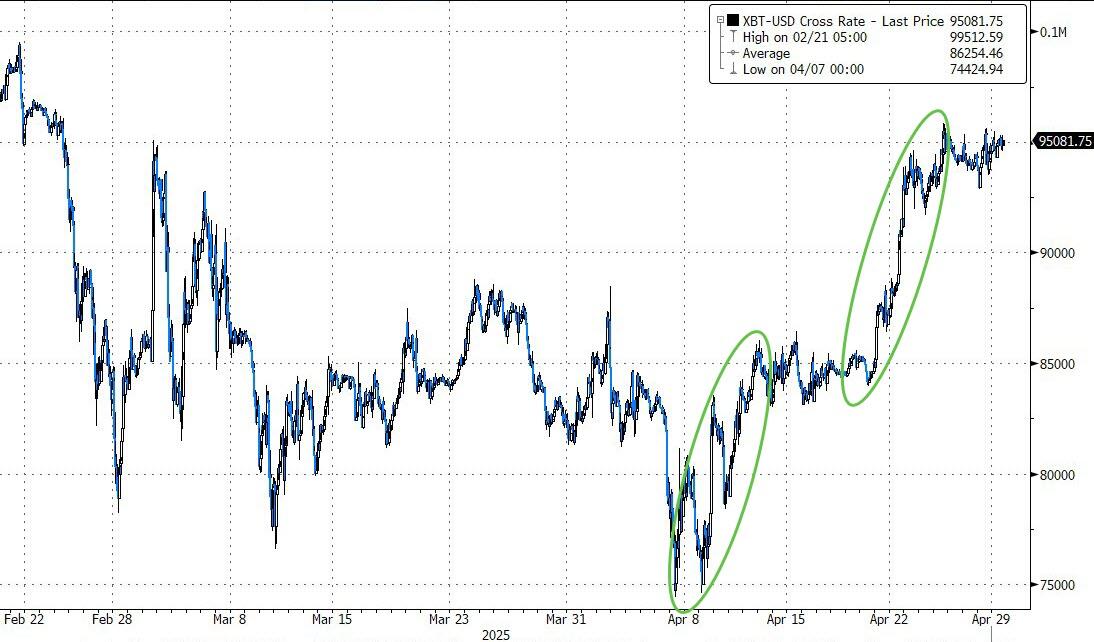
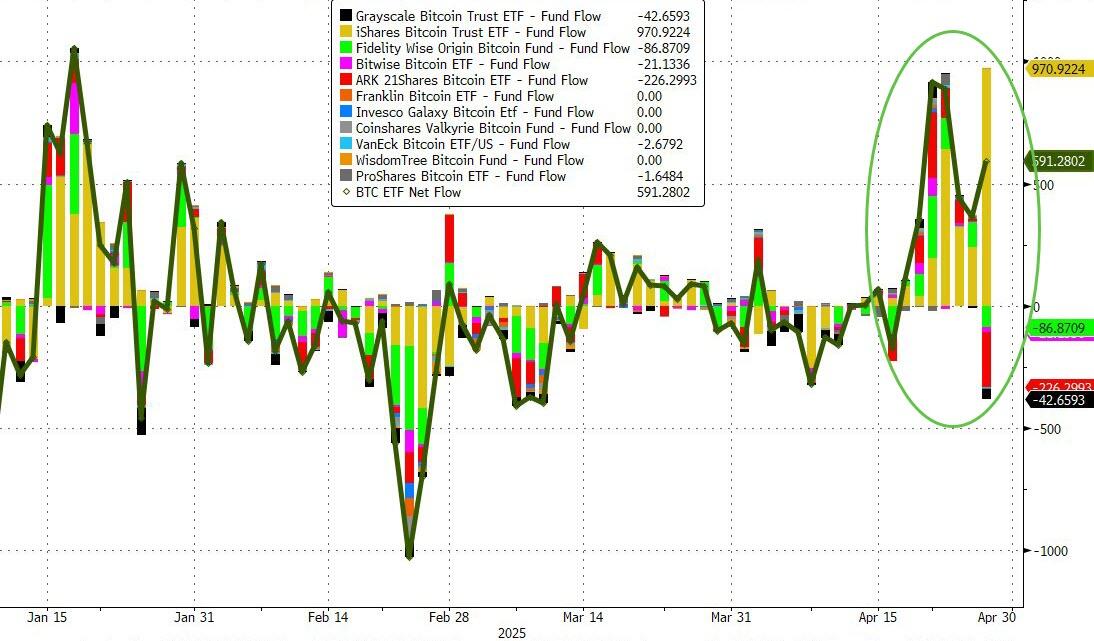
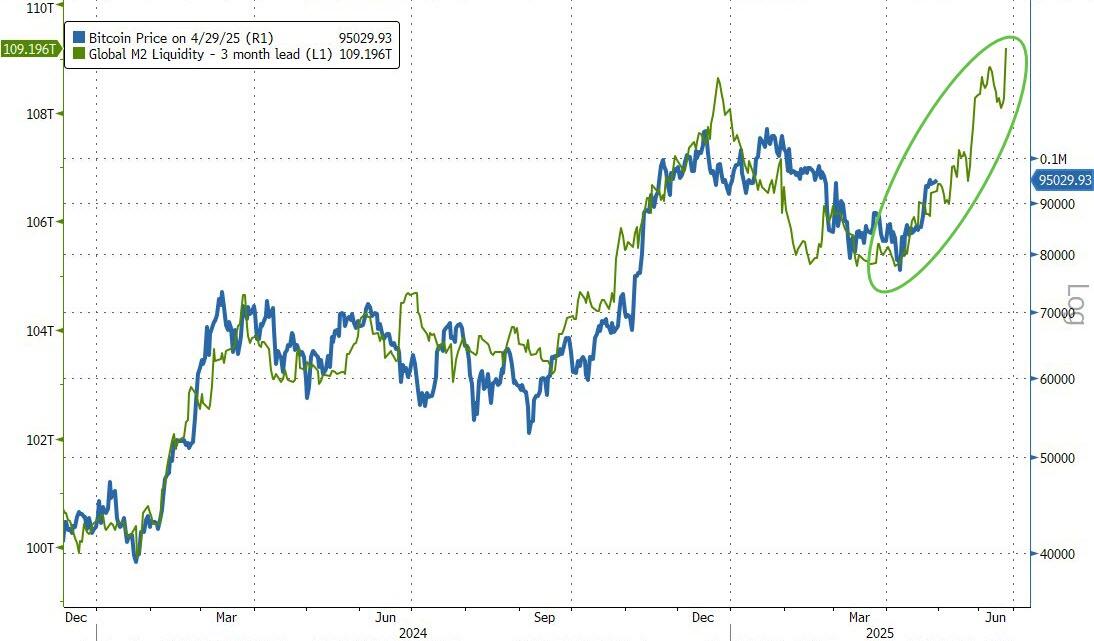
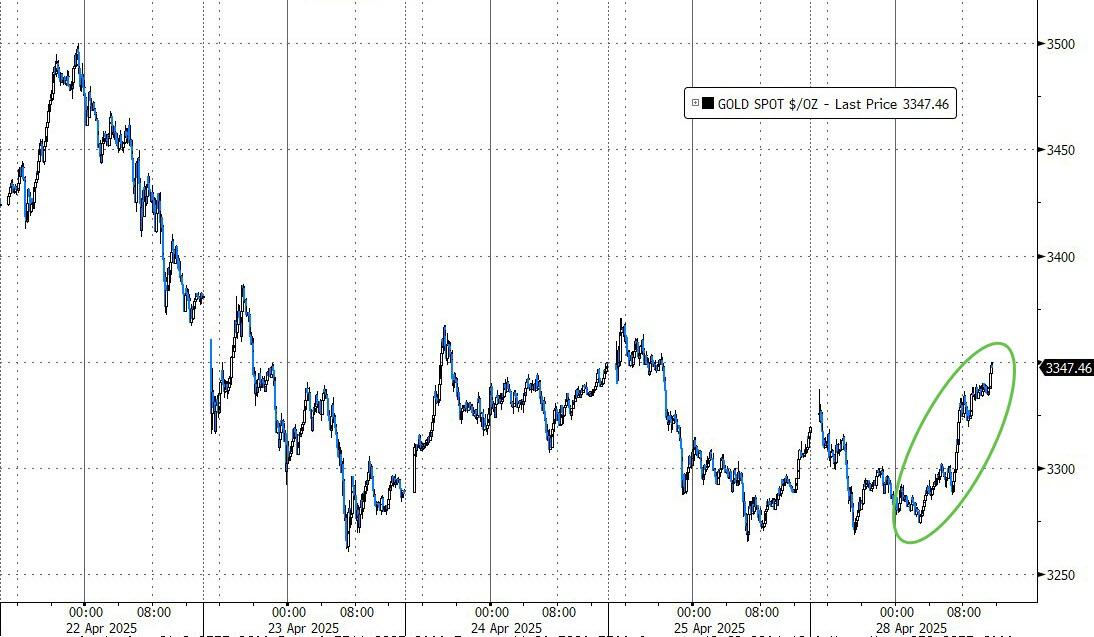
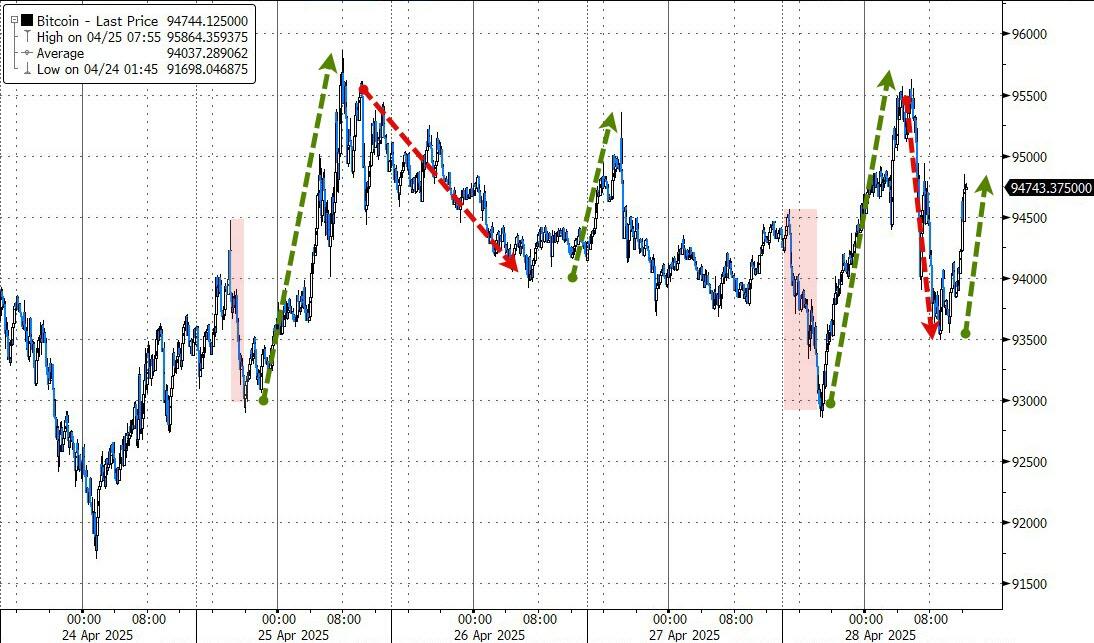
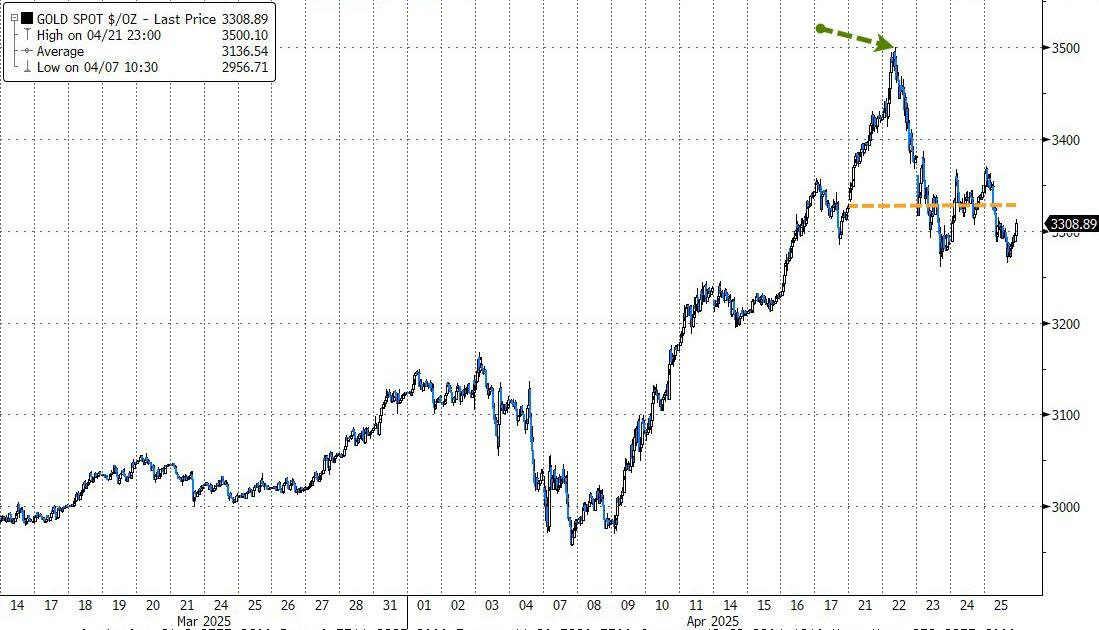
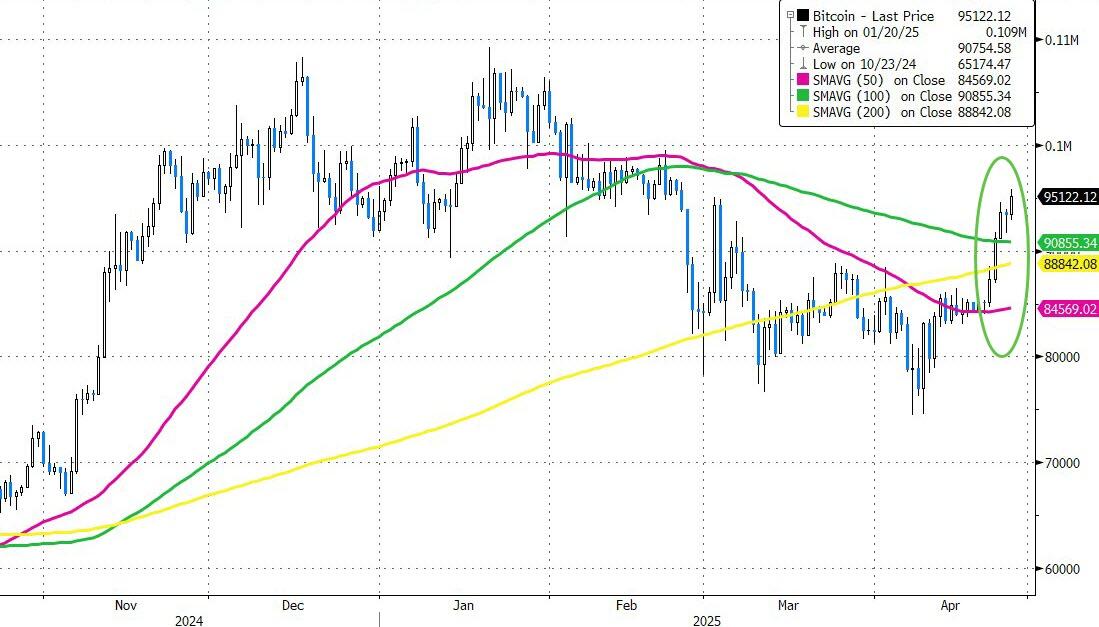
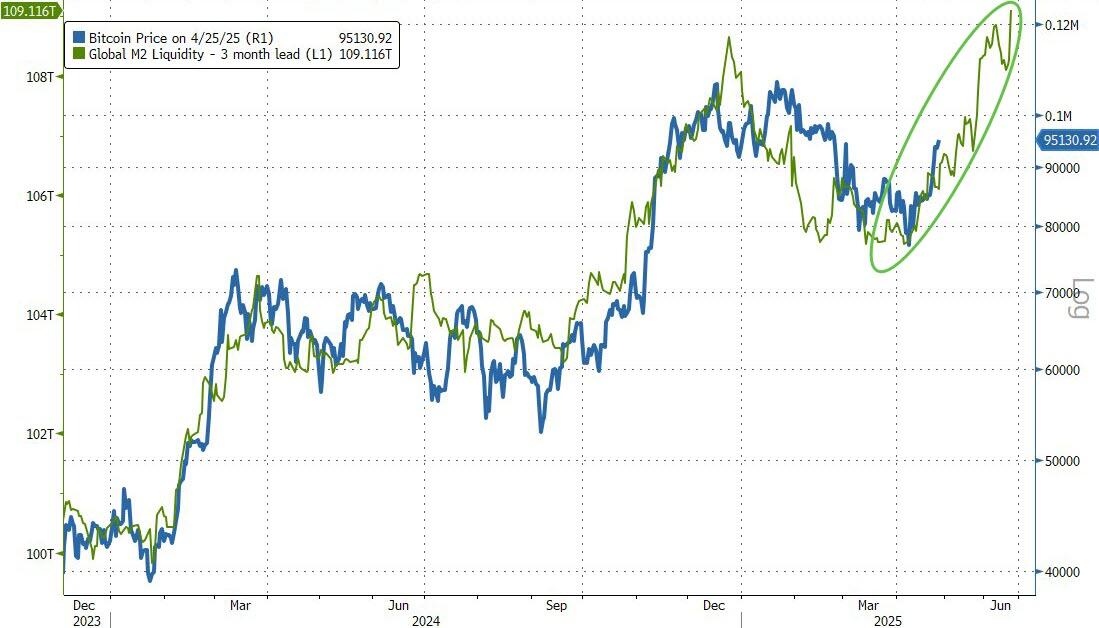
Gold moved in the opposite direction, gaining almost 6%, marking its fourth straight monthly rise, while Bitcoin rallied 14% for the month, its best performance since November, according to ZH.
It seems we are back to “bad news is good news,” as far as stocks are concerned, with bonds, crude oil, dropping U.S. inflation, and copper pointing to a recession, while rate-cut expectations are jumping higher along with equities.
Read More