ETF/No Load Fund Tracker Newsletter For May 1, 2015

Ulli ETF Tracker Contact

ETF/No Load Fund Tracker StatSheet

————————————————————-

THE LINK TO OUR CURRENT ETF/MUTUAL FUND STATSHEET IS:

https://theetfbully.com/2015/04/weekly-statsheet-for-the-etfno-load-fund-tracker-newsletter-updated-through-04302015/

————————————————————

Market Commentary

STOCKS POST STRONG MAY ENTRANCE, BUT CLOSE WEEK LOWER

Fri pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Equities rebounded as Wall Street kicked off May with a strong rally and the Dow recouping most of the previous day’s losses. Stocks finished the week slightly lower though.

Don’t forget that May kicks off what has traditionally been the worst six months for stocks, which has brought rise to the old saying “sell in May and go away.”

Investors digested a relatively heavy flow of news during the week across both economic and corporate earnings reports, and the tone was pretty mixed overall. Health care and discretionary stocks led decliners, while materials and energy both moved higher on the week.

In earnings news, LinkedIn (LNKD) is the latest social media stock to take a pounding following its earnings report. In the wake of lowering its outlook after Thursday’s closing bell, the stock plunged 18.6%. Chevron (CVX), like fellow Dow component Exxon Mobil (XOM) on Thursday, reported a big dent in its business tied to sinking oil prices. CVX’s reported profit fell 43% and shares dropped 1.8%.

Economic news was mixed throughout the week, with the GDP and consumer spending reports headlining the weak data, while housing indicators were a bit better than economists were looking for. Despite the slower start to the year, economists still expect a rebound in economic growth as the year unfolds. Over the next five trading days, the April jobs report will headline another busy week of both economic and corporate earnings news. Factory orders will be announced Monday, and Tuesday brings the ISM Non-Manufacturing index.

Today’s reversal pushed all of our 10 ETFs in the Spotlight higher with the leader being consumer discretionaries (XLY) with +1.38%, while healthcare (XLV) came in at a close second with +1.35%. The weakest member of the group turned out to be DVY with a gain of 0.50%.
Read More

Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 04/30/2015

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, April 30, 2015

TOC021915

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


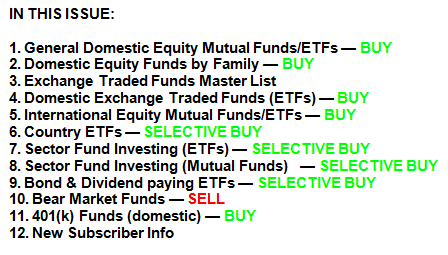
1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: BUY — since 10/22/2014

TTI0430

Our main directional indicator, the Domestic Trend Tracking Index (TTI), broke through its long-term trend line generating a “Sell” for this arena effective 10/14/2014, which was followed by a violent break back above the line on 10/22/14 generating a new “Buy.” It was a classic whipsaw signal, and you can read more on my blog as to the events as they were unfolding.

As of today, our TTI (green line in above chart) is positioned above its long term trend line (red) by +2.29% keeping us in the market with our established positions.

Read More

Ending April On A Sour Note

Ulli Market Commentary Contact

Thur pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

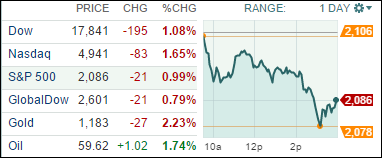
Stocks ended the month on a weak note as traders reacted to new information, ranging from a suddenly weakening dollar vs. the euro and strong incoming U.S. data that raised fresh fears about interest rate hikes.

We heard some solid economic data released today, including a better-than-expected reading on manufacturing in the Chicago region and a bigger-than-expected rise in employment costs, which could be signaling that the first-quarter soft patch may, in fact, be transitory, as the Federal Reserve suggested in its policy statement yesterday. Stocks fell for a second straight day after Wednesday’s news of anemic GDP growth of 0.2% in the first quarter, and the Fed’s announcement that showed policymakers are still grappling with when to begin raising interest rates but indicated they could hike rates at any meeting.

In earnings news, ExxonMobil (XOM) earnings fell 46% on lower oil prices and revenue. On the flipside, the company announced a 9.5% dividend increase. The stock fell 0.6%. Time Warner Cable (TWX) saw its largest increase in video subscribers in six years. But earnings missed Street expectations, and TWC dropped 1.5%.

Also in earnings, shares of LinkedIn (LNKD) plunged 27% in extended trading on a weak corporate earnings outlook. The leading online professional network said it expects adjusted per-share earnings of 28 cents on sales of $670 million to $675 million for the current quarter, which ends June 30.

As for the international realm, shares fell in Asia on Thursday following the U.S. economic news, and Japan also reported that its industrial output fell 0.3% in March from the month before and 1.2% from the previous year.

All of our 10 ETFs in the Spotlight again slipped and closed in the red. Leading the group to the downside was this year’s winner, healthcare (XLV), with a loss of 1.40%, while consumer staples (XLP) held up best by giving back only 0.33%.

Read More

A True “Hump Day” Of Ups And Downs

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

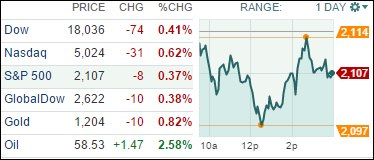
Stocks closed lower as investors digested weaker-than-expected economic growth and the latest statement from the Federal Reserve that indicated policymakers were still grappling with when to begin raising interest rates.

Continuing with Fed matters, The Federal Reserve gave a slight signal today that it could raise interest rates at any meeting, opening the door to the possibility of a mid-summer rate hike.

In M&A news, it was all about Salesforce.com (CRM) today. Shares of the company soared on a report that the cloud computing giant has hired sell-side advisors to field takeover inquiries. The stock gained 12% on the day to close at $74.65. Salesforce.com has a market value of nearly $50 billion, said S&P Capital IQ analyst Scott Kessler. Which would make it the largest ever takeover of a software company.

The only major earnings news was that of Fiat Chrysler Automobiles (FCAU). The company reported earnings per share of 52 cents compared with a loss of $1.55 per share for the same period a year ago. Those results accelerated way beyond analysts’ expectations of just 7 cents per share, however, the stock dropped 5.5% on the day.

All of our 10 ETFs in the Spotlight slumped and closed down. Holding up the best was IYF with a scant 0.10% loss, while SPLV gave back 1.00%.

Read More

Stocks Close Mostly Higher On Mixed Economic Data; Twitter Falters

Ulli Market Commentary Contact

Tue pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

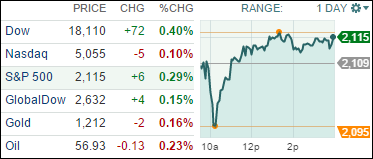
Stocks cut early losses and closed mostly higher as the Federal Reserve began a two-day policy meeting to discuss the economy and interest rates. The Nasdaq was the only major index that closed in the red, down 0.10%.

As you know, interest rates have been at the forefront of news headlines for the past year. However, it still seems that most economists believe there’s virtually no chance the Fed will hike rates Wednesday after stating last month that an April move was unlikely. But investors will be scouring the central bank’s post-meeting statement though for clues as to whether a June liftoff remains a possibility.

In earnings news, you may want to “tweet” this bit of info. Shares of the social media company Twitter (TWTR) plunged after it reported first-quarter revenue far below Wall Street estimates and issued a disappointing outlook for the current quarter and for the rest of the year. Twitter reported a loss of $162 million, or 25 cents a share, compared with a loss of $132 million, or 23 cents a share a year ago. Shares of Twitter fell as much as 20% and closed down 18% to $42.27.

In other economic news, stocks fell early in the trading session after it was reported that consumer confidence unexpectedly tumbled in April. We also saw disappointing job growth numbers and continued. We did hear some positive news though on the housing front. Home prices climbed at a faster pace in February than the previous month, driven by higher sales and a limited supply of available houses.

In a reversal from yesterday, 9 of our 10 ETFs in the Spotlight headed higher with DVY showing the best gain at 0.58%, while XLY ended up in the red with a loss of 0.35%.

Read More

Pulling Back From Record Highs

Ulli Market Commentary Contact

Mon pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

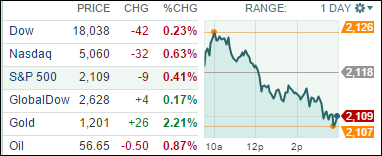
A pause sure was in order after last week’s push into record territory. The major indexes pulled back as the chart above shows.

The focus remains on earnings with the name of the game being to beat the already lowered expectations. After the closing bell, Apple managed to beat handsomely by posting an amazing 33% rise in earnings, which pushed the stock up by 1.82% in after-hours trading.

Things might heat up by mid-weak, as a preliminary reading on the first quarter GDP will be released on Wednesday, while the Fed will also deliver the latest policy statement after its two-day meeting.

Only 1 of our 10 ETFs in the Spotlight managed to buck the downward trend, namely IOO, which gained 0.39% on the day. Leading the downside was XLV, which gave back 1.81% as bio stocks in general were pulled off their lofty levels.

Read More