1. Moving the Markets
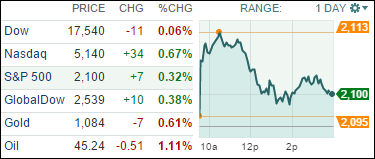
While most indexes managed to close above the unchanged line, the Dow ended up slipping thanks to a weak performance in energy and Disney.
The early rally was based on hope that odds of an interest rate increase by the Fed next month subsided a bit due to a soft reading on ADP’s payroll report of 185,000 newly created jobs in July vs. 229,000 in June.
Of course, as we’ve seen in the past, ADP being a front runner to Friday’s jobs report by the Labor Department does not mean there are any conclusions to be had in what Friday’s numbers will look like. In the past, we’ve seen higher and lower figures, so this is not indicative of what we can expect. Nevertheless, a weak report could mean that the Fed might not hike next month, or so the theory goes.
9 of our 10 ETFs in the Spotlight headed higher led by Healthcare (XLV) with +0.84%, as Consumer Discretionaries (XLY) bucked the trend and closed lower by -1.08%.