1. Moving the Markets
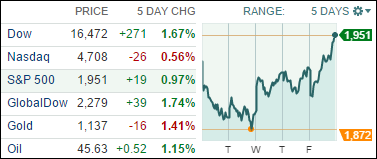
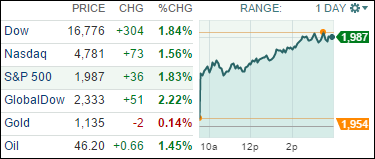
Stocks kicked off the week in rally mode Monday as investors view a Federal Reserve interest rate hike this year as less likely after Friday’s weak jobs report raised questions about the pace of U.S. growth.
Third quarter earnings season kicks off this week when Alcoa (AA) reports on Thursday. Analysts are predicting a decline of 4.8% for S&P 500 companies, which would be the first quarter-over-quarter profit decline since 2009.
The culprit for market declines is largely pointing towards the energy sector. Companies in the energy sector are expected to post 60% lower profits for Q3, which is mainly due to a 50% drop in oil prices from this time last year. Don’t let these numbers fool you though, because energy companies skew the numbers. Excluding energy sector stocks, corporate profits are on track to be growing 3.5%, according to S&P capital IQ.
In other corporate news, we heard today that American Apparel (APP) has filed for bankruptcy, after its made-in-the-U.S. model faltered, its fashion sense slipped and its controversial former CEO became embroiled in scandal over his behavior in the workplace. The company, which flirted with bankruptcy as early as 2011, has about 8,500 employees at six factories and 230 stores in the U.S. and 17 and it famously bet its business model on clothing made in the U.S.
Continuing Friday’s theme, all of our 10 ETFs in the Spotlight rallied and closed higher with the leader being the MidCap Value (IWS), which added +2.14%. The laggard for the day was Healthcare (XLV) with +0.26%.