1. Moving the Markets
Despite great anticipation, the Fed minutes turned out to be a dud, as the usual jawboning concluded with “policy makers judged a rate hike could be warranted ‘relatively soon,’ if the economy continues to strengthen.” Of course, I did not expect any changes prior to the election since the Fed is in support of the incumbent party.
On the other hand, a December hike is not a certain thing either, especially if job openings, Fed chief Yellen’s favorite market indicator, continue to plunge. Today’s report showed the August number of job openings tumbling by some 388k, which was the lowest in a year.
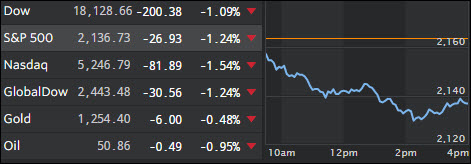
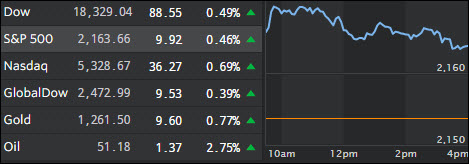
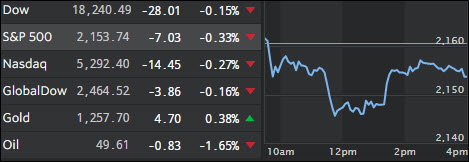
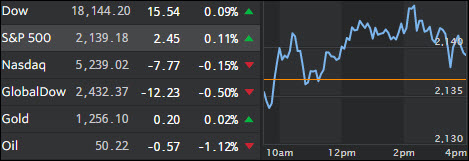
At day’s end, the major indexes went nowhere with the Dow and S&P slightly gaining while the Nasdaq retreated a tad. I expect this sideways trend to continue through the elections but would not be surprised if volatility picks up again, especially if a known systemic problem, such as Deutsche Bank, makes negative headlines again, which could affect market direction suddenly and without warning.