ETF Tracker Newsletter For February 2, 2018

Ulli ETF Tracker Contact

ETF Tracker StatSheet

https://theetfbully.com/2018/01/weekly-statsheet-etf-tracker-newsletter-updated-01-25-2018/

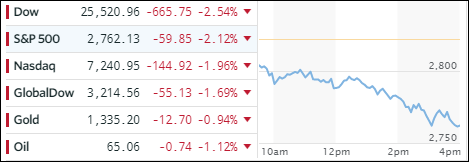
 S&P 500 AND DOW SPORT LARGEST WEEKLY DECLINE IN 2 YEARS
[Chart courtesy of MarketWatch.com]
  1. Moving the markets

There was simply no place to hide. After having broken all kinds of records during the past year, it was time for the bears to have their moment in the spotlight—at least for this week. The major indexes got spanked with the S&P 500 dropping -2.12% for the day, its biggest one-day drop since September 2016, and -3.9% for the week. Not helping matters was the VIX, which saw its largest spike since August 2015. However, the correction was orderly with no sense of panic.

Today’s pullback was not limited to US stocks, but equities around the world (China, Europe, Asia) confronted the long-known reality that nothing goes up forever. The question now is whether this is the beginning of a new bearish trend or merely a hiccup in this aging bull market. At this point it’s too early to tell, and we will need more data points to make that decision.

Contributing to this week’s market drop were a variety of reasons with rising interest rates being on top of the list. I have pointed out in previous posts that once a certain threshold is passed, bond yields will have a negative impact on equity prices. The 10-year yield is one of those indicators, and it shot higher again today by 6 basis points to close at 2.84%, its highest level since January 2014. That resulted in another pounding of the 20-year bond (TLT), which lost -0.93%.

Also not assisting the bulls was today’s stronger than expected jobs report (200k added) showing that wages grew at the fastest pace in more than 8 years, causing inflation fears to spread and pushing yields higher. As MarketWatch pointed out correctly, “the market is now pricing in tighter monetary policy if inflation driven by wage growth accelerates.”

Needless to say, red was the color of choice for the day. Interestingly, the US Dollar (UUP) vacillated around the unchanged line but managed to eke out a gain of +0.61%.

Read More

Weekly StatSheet For The ETF Tracker Newsletter – Updated Through 02/01/2018

Ulli ETF StatSheet Contact

ETF Data updated through Thursday, February 1, 2018

Methodology/Use of this StatSheet:

  1. From the universe of over 1,800 ETFs, I have selected only those with a trading volume of over $5 million per day (HV ETFs), so that liquidity and a small bid/ask spread are assured.
  2. Trend Tracking Indexes (TTIs)

Buy or Sell decisions for Domestic and International ETFs (section 1 and 2), are made based on the respective TTI and its position either above or below its long-term M/A (Moving Average). A crossing of the trend line from below accompanied by some staying power above constitutes a “Buy” signal. Conversely, a clear break below the line constitutes a “Sell” signal. Additionally, I use a 7.5% trailing stop loss on all positions in these categories to control downside risk.

  1. All other investment arenas do not have a TTI and should be traded based on the position of the individual ETF relative to its own respective trend line (%M/A). That’s why those signals are referred to as a “Selective Buy.” In other words, if an ETF crosses its own trendline to the upside, a “Buy” signal is generated. Since these areas tend to be more volatile, I recommend a wider trailing sell stop of 7.5% -10% depending on your risk tolerance.

If you are unfamiliar with some of the terminology, please see Glossary of Terms and new subscriber information in section 9.


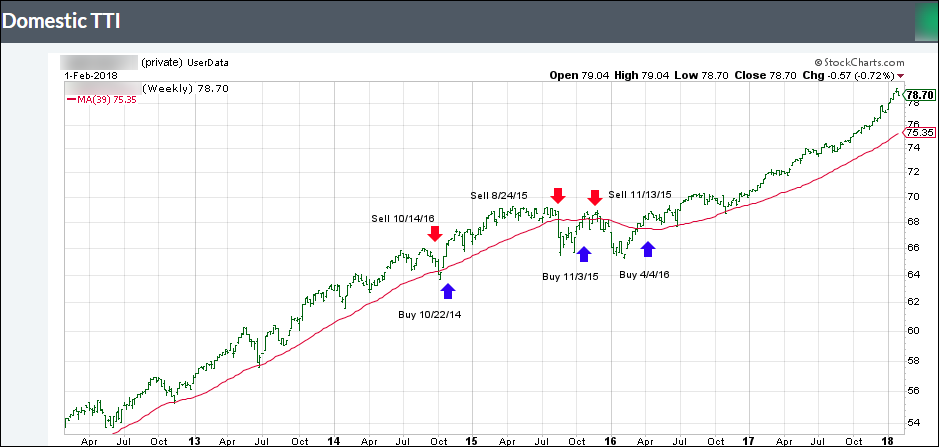
  1. DOMESTIC EQUITY ETFs: BUY — since 4/4/2016

Click on chart to enlarge

Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in the above chart) is positioned above its long-term trend line (red) by +4.64% after having generated a new Domestic Buy signal effective 4/4/2016 as posted.

Read More

Uncertainty Reigns Ahead Of Jobs Report

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

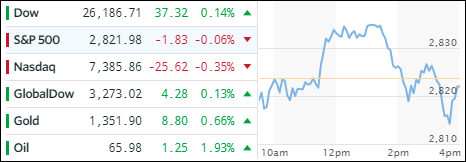
It was another roller coaster ride with the indexes vacillating around their unchanged lines. A nice mid-day rally fizzled out and accelerated to the downside in the last hour when dip buyers stepped in to limit the damage. Volatility picked up due to rising interest rates and inflation along with uncertainty ahead of tomorrow’s jobs report.

The mixed picture carried over to ETF land where winners and losers were just about evenly matched. Bucking the bearish trend were Financials (XLF +0.94%), Aerospace & Defense (ITA +0.57%) and International SmallCaps (SCHC +0.42%). On the other end of the spectrum, we saw Emerging Markets (SCHE -1.41%), Semiconductors (SMH -0.61%) and Transportations (IYT -0.56%) closing in the red.

The bond arena saw a bloodbath today with the yield on 10-year jumping 6 basis points to 2.78%, a level last seen in April 2014, while the 30-year climbed above the 3% level to end the session at 3.01%. As a result, bond prices plunged with the widely held 20-year (TLT) losing -1.45%, which it had last visited in May last year.

If you are wondering how the US dollar (UUP) fared in this environment, it should come as no surprise that it got spanked as well (-0.52%), or monkey hammered as some analysts referred to it. But, but, as President Trump recently confirmed, we have a strong dollar policy. Go figure…

Read More

Stumbling But Closing In The Green

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

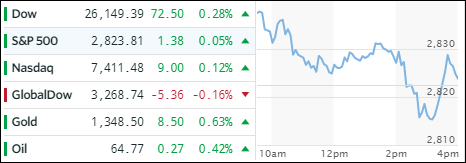
An early rebound faltered, and the major indexes declined below the unchanged line but managed to crawl back into positive territory to close out the month with solid gains. The Dow added +5.8%, its best January since 1997, while the S&P 500 and Nasdaq rallied +5.6% and +7.4% respectively. The culprit for the weakness was the Fed hinting that it is “set to raise interest rates as early as its next meeting in March.”

As a result, bonds were spooked with the 10-year yield bouncing to 2.74%, which is its highest level since early 2014, but closing at 2.72%. In the end, equities closed mixed along with our ETFs. Emerging markets (SCHE) were the clear leader with a solid gain of +1.26%, which was closely followed by Semiconductors (SMH +0.84%). Closing in the red were US SmallCaps (SCHA -0.50%) and International SmallCaps (SCHC -0.10%).

Gold and Crude Oil both closed up, but the US Dollar (UUP) lost another -0.13% and had its worst January since 1987.

Read More

Major Indexes Down For 2nd Straight Day

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

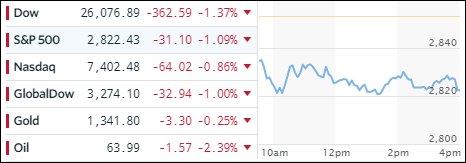
It should be no surprise to anyone that, given the tear the markets have been on over the past 14 months without much of an interruption, a correction or pullback was way overdue. Weakness was broad based with the main culprits being healthcare, technology, energy and financials. Especially, some of the diving healthcare stocks contributed some 40% of the Dow’s decline.

Not helping matters was another VIX spike to above the 15 handle, its highest level since August. Bond yields continued pushing up with the 30-year now honing in on the psychologically important 3% level, while the 10-year yield sported a gain of 3 basis points to end the session at 2.73%. Both, bond and stock holders, had the worst day since election when considering that the much hyped “safe” combination, stocks down and bonds up, failed.

However, in the end, a view of the big picture is important, which says equities are still on path to their best monthly gain in 2 years—and the 15th monthly gain in a row (thanks to ZH for this stat). The US dollar (UUP) took a dive despite Treasury Secretary Mnuchin desperately trying to take back his words at Davos that “a weaker dollar is good for us as it relates to trade and opportunities.” His jawboning today, that he “supports a strong greenback in the long term,” merely softened the dollar’s slide.

Read More

10-Year Bond Yield Pumps And Equities Dump

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

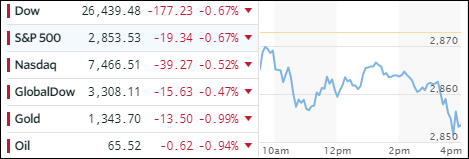
A host of news events combined forces to pull equities off their lofty levels with the S&P 500 having its worst day in 5 months, while bonds had their worst day in 6 weeks. First, there were the NAFTA negotiations, which appeared to be progressing well, but the fly in the ointment was that there was no willingness to issue a joint statement thereby putting pressure on the stock market early on.

The VIX spiked and did not pull back and, with the market manipulators apparently asleep at the wheel, closed at its highest since August. Then rising interest rates kicked in with the 10-year bond yield jumping 4 basis points to close at 2.70% (intra-day to 2.72%) its highest level since April 2014. A variety of individual stocks took a noticeable dive such as WYNN (Steve Wynn sex scandal), AAPL (iPhone X orders slashed) and CAT (declining margins), all of which gave the bears the upper hand—at least for this day.

However, in the bigger scheme of things today’s pullback is hardly worth mentioning when considering the rapid market advances we’ve seen not only last year but during the first month of this year as well. With all this debacle going on, the US Dollar (UUP) managed to buck the overall negative trend by closing up +0.26%; a tiny bounce off its multi-year lows.

Read More