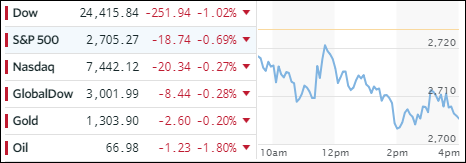
- Moving the markets
While worries about Italy’s politics faded for the moment, they were quickly replaced by news of a new Spanish PM, with a very critical view of the European Union, causing more uncertainties in the markets.
However, taking top billing was the Trump administration’s confirmation imposing steel and aluminum tariffs on the EU, Mexico and Canada beginning at midnight tonight. The response by the EU was quick and angry and counter balancing measures were said to be on its way.
Not helping the bearish mood were headlines that the housing rebound is slowly dying with new, existing and pending home sales tumbling in April.
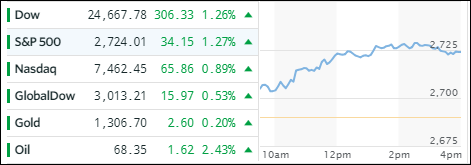
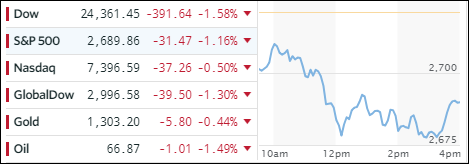
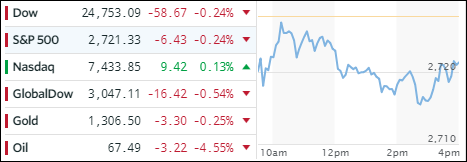
As a result, the major indexes headed south again, after an encouraging rebound yesterday, but they managed to close in the green for the month with the S&P 500 adding 2.2%.
Despite sliding bond yields, with the 10-year dropping 1 basis point to close at 2.83%, we’ve seen as of late a variety of risk scenarios that have kept a lid on market advances.
Looking back to the beginning of the year, we’ve struggled with a range of issues, namely higher interest rates and inflation, which was followed by trade/geopolitical fears and now Italian and Spanish politics.
And, let’s not forget the potential downgrade and/or possible demise of Deutsche Bank (DB), AKA the mother of all derivatives. Making its situation even more critical was today’s disclosure by the Fed that DB had been placed on a “troubled condition” status a year ago. Ouch!
It promises to be an interesting summer…