The Morning After: Fed’s Softened Rate Outlook Propels Equities

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

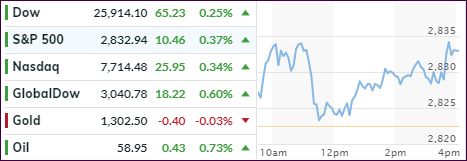
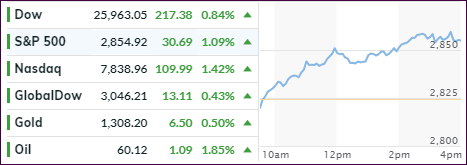
The fallout from the Fed’s soft outlook on interest rates was, so far, overwhelmingly positive with the bulls grabbing the baton and storming deeper into bullish territory. While the idea that no rate hikes on the horizon for 2019 stoked equity investors, worries kept creeping up that this was just a function of a slowing economy that could eventually result in the much-dreaded recession.

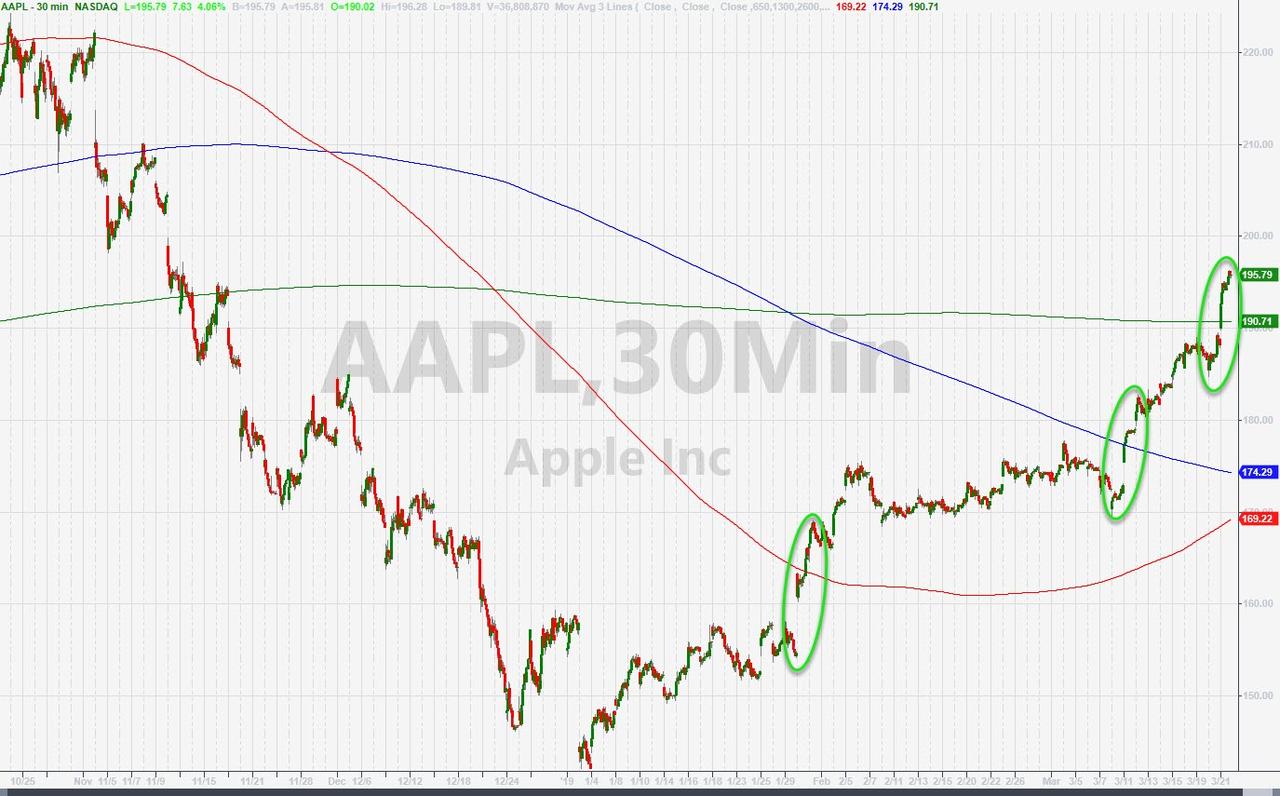
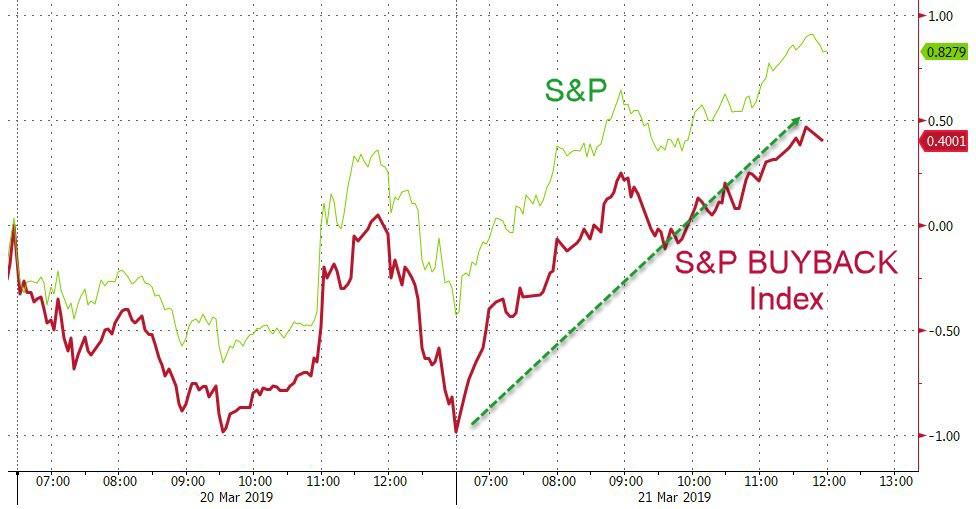
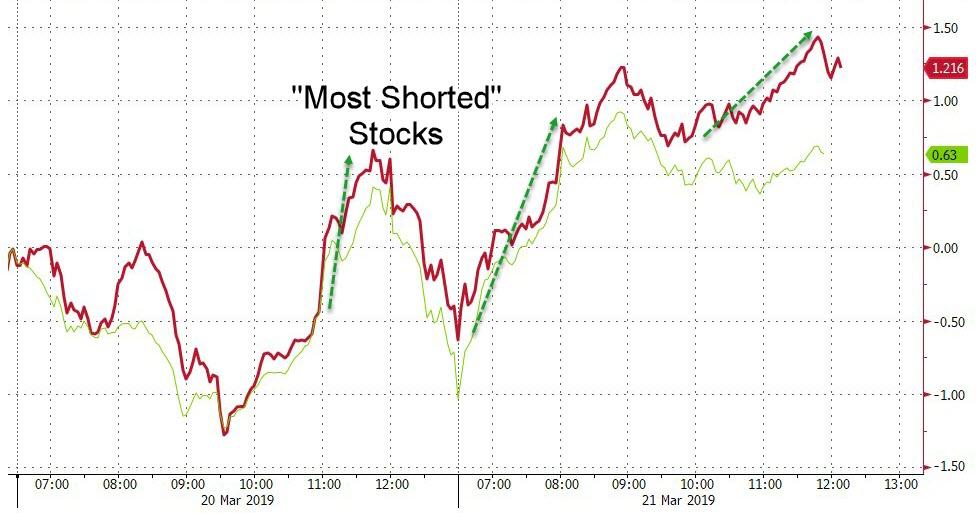
Be that as it may, right now the trend is bullish, and the major indexes, led by the Nasdaq, closed solidly higher. The gains were broad with our sector holdings making nice advances. Powerhouse Apple dominated the indexes by adding +3.68% and reclaiming its 200-day M/A, while buy-backs and short-squeezes combined their efforts to make this a miserable day for the bears.

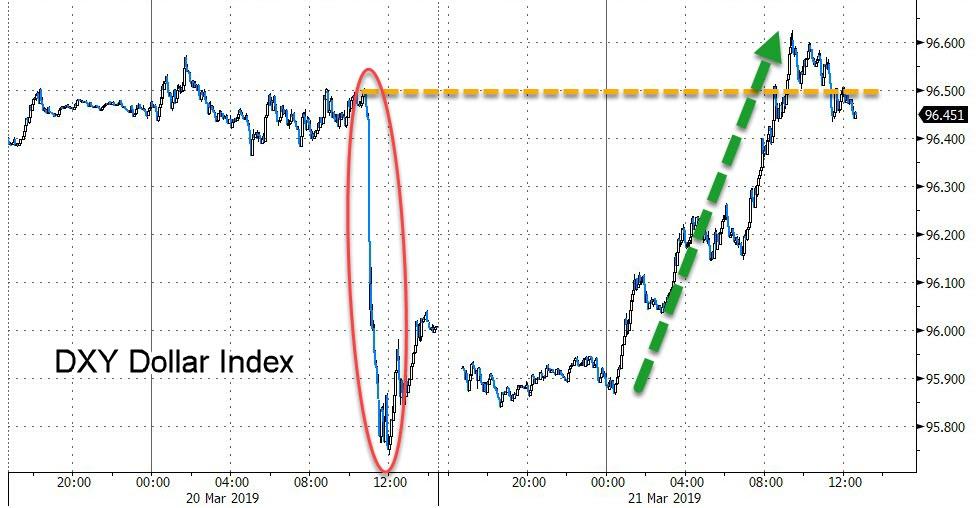
The U.S. Dollar did a complete U-turn and retraced all of yesterday’s losses in one session, while Financials, which are negatively affected by lower rates, kept slipping and sliding.

It was a good day for the bulls, but we need continued steady upward momentum, which possibly could get a boost from the upcoming earnings season.
Read More

Fed Outlook Temporarily Lifts Equities, But Gains Fade Into The Close

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

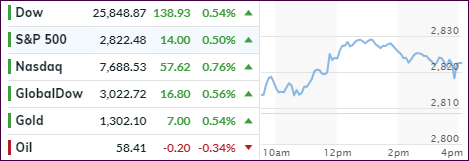
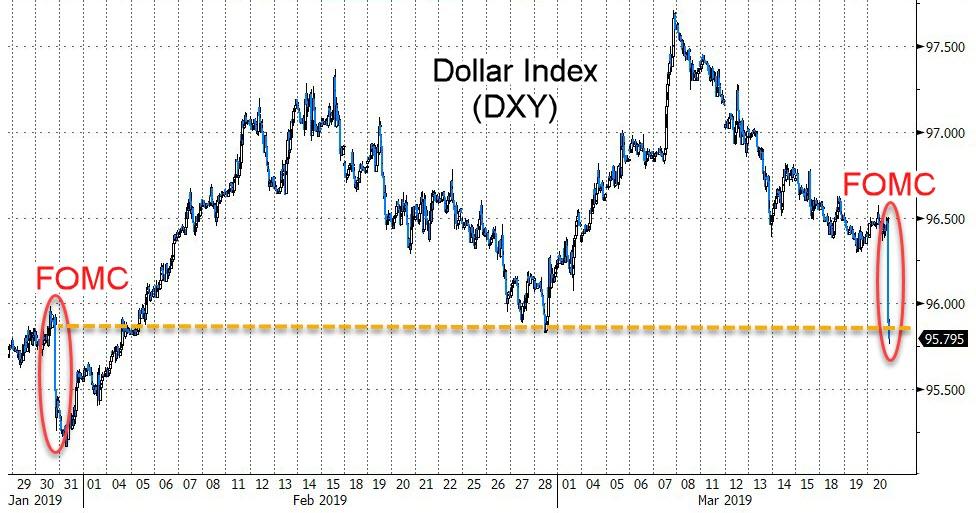
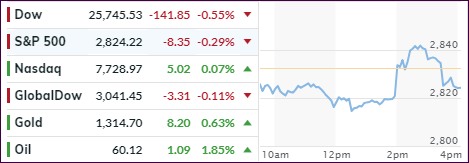
After an early dump, the markets stabilized mid-session, after the Fed softened its rate outlook and opined positively on the state of the economy. Some analysts likened the Fed’s statement to “folding like a cheap lawn chair,” as it dramatically slashed its stance on interest rates.

It seems, at least for the time being, that the Fed will hold rates steady this year before raising it once in 2020. If that pans out, according to ZH, it would be unprecedented:

Since the 1970s, there have been three times when the Fed held rates steady for more than a year after raising them in the precious three months: 2006, 2007 and 1997. Invariably, the next move was a rate cut.

However, as I pointed out yesterday, the market has gotten “greedy” and expects a rate cut of 16 bps in 2019. With that potentially not happening, equities surged at first but then faded quickly into the close leaving only the Nasdaq in the green.

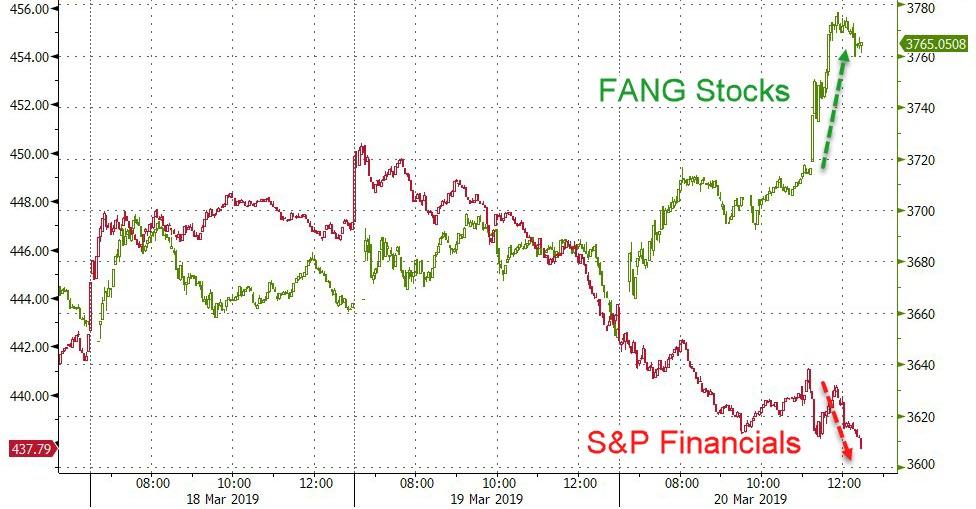
It was a tale of many markets. On one hand, FANG stocks rallied but Financials got clobbered, along with Regional Banks, which comes as no surprise given the Fed’s dovish statement.

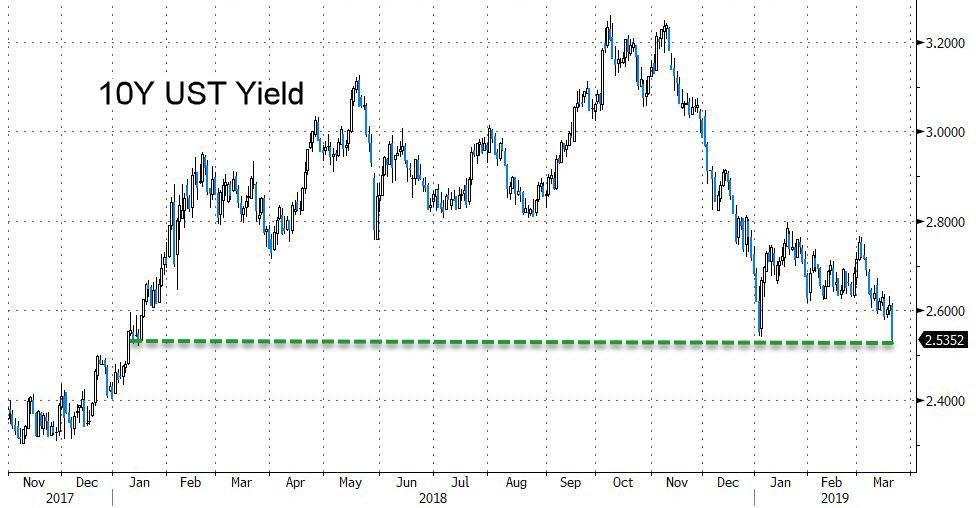
Bond yields got hammered with the 10-year now reaching 2.52%, its lowest since January 2018. The more obvious loser of the day was the U.S. Dollar, which crashed down to a level last seen early February. It has now been down 8 of the last 9 days after being up 7 days in a row. Keep in mind that lower bond yields affect the Dollar negatively.

In my advisor practice, I took advantage of the early pullback to add to our investment positions based on my assumption that the Fed would maintain its dovish bias and therefore pull the indexes out of the doldrums.

Read More

An Early Rally Stumbles

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

An early rally lost steam mid-day when reports (Bloomberg) surfaced that trade negotiations ran into a brick wall, as the Chinese pushed back to get more assurances on tariffs. That story was then rebuffed, as the WSJ offered a different version:

Talks between the two nations are in the final stages, said individuals tracking the negotiations, with a target date for a deal by the end of April. That is about a month later than the two sides had initially planned.

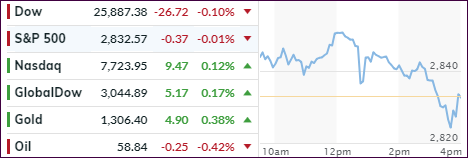
As a result, equities rebounded but momentum continued to slip with the major indexes ending up closing at their respective unchanged lines. Of course, motivation, or lack thereof, in anticipation of tomorrow’s Fed announcement on interest rates, played a role as well in traders’ minds to not make too aggressive of a commitment.

Transportations (IYT) were the ugly duckling of the day by shedding -1.39%, but YTD the index is up solidly. The Dow “lost” its 26k marker but should be able to regain it if the Fed does not disappoint.

And that is the big question du jour. ZH commented that markets have priced in 16 basis points of rate cuts for 2019, which to me means that Fed head Powell must present a very dovish viewpoint tomorrow to even have a chance to “please” the markets.

Read More

Edging Higher Ahead Of The Fed

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

Friday’s quad-witching hour turned into a positive for equities in general while today’s market action ahead of the Fed meeting on interest rates was inconsistent but upward trending.

Most of the action happened at the opening, when a surge pushed stocks higher, which was followed by a lull throughout the session, before buyers stepped back in at the close to push the major indexes back to their morning highs.

Expectations are for the Fed, at their Wednesday meeting, to leave interest rates unchanged, but more importantly, every word presented in their final statement will be dissected and regurgitated. The goal is to analyze and figure out the Fed’s projected path on interest rates, such as one hike this year and anther one in 2020.

The hope is that the dovish and wait-and-see attitude adopted in January still has merit, because it was instrumental in pulling stocks out of the December bear market and creating this incredible rebound of 2019 that rescued the buy-and-hold crowd.

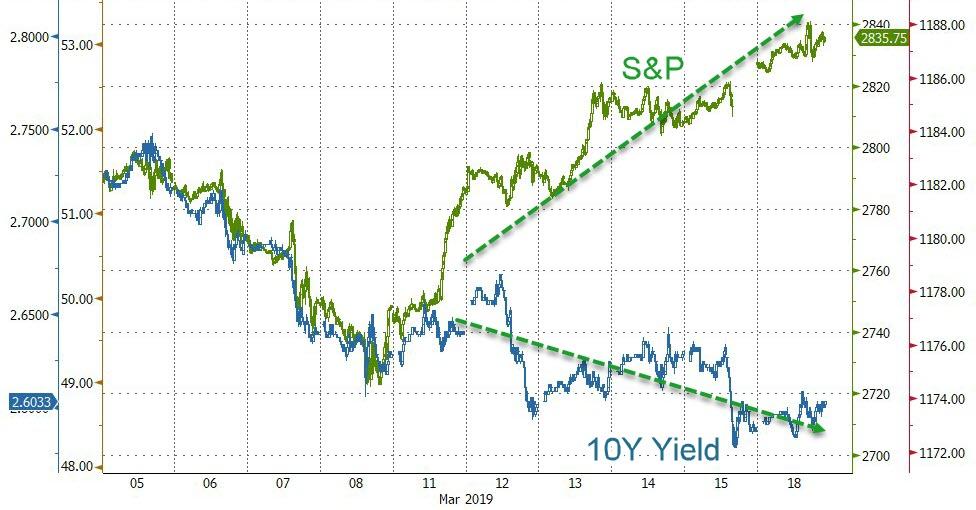
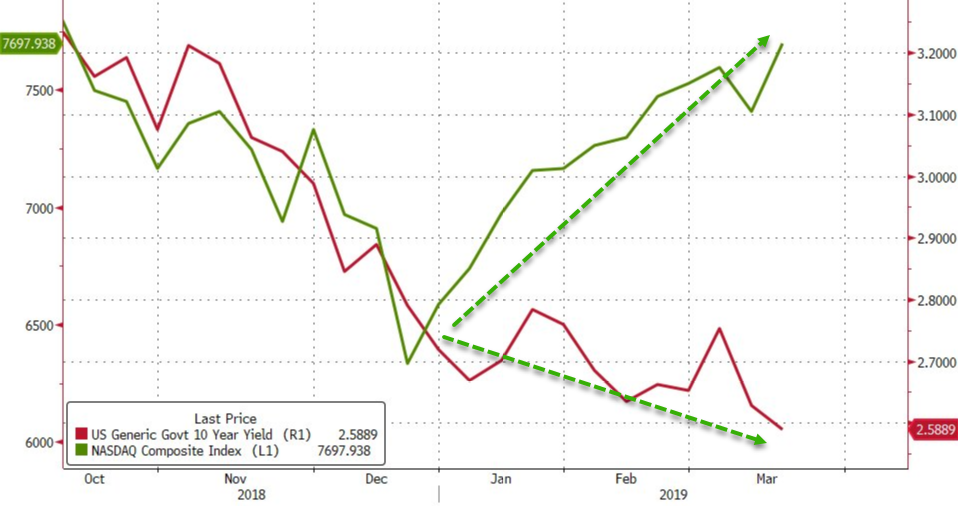
If the Fed maintains that policy, we may see more equity advances. If it doesn’t, we could see a sell-off that might retrace the 2019 gains. It would make sense to think that they will not do another policy U-turn, so the former is more likely than the latter. Still, the gap between stocks and bonds continues to widen and has reached 120 S&P points at this time.

While that may seem large to you, it would only take a ~4.2% correction on the S&P 500 to fall back in sync with the direction of bonds, which is certainly within the range of what’s acceptable.

Read More

ETFs On The Cutline – Updated Through 03/15/2019

Ulli ETFs on the Cutline Contact

Below, please find the latest High-Volume ETF Cutline report, which shows how far above or below their respective long-term trend lines (39-week SMA) my currently tracked ETFs are positioned.

This report covers the HV ETF Master List from Thursday’s StatSheet and includes 322 High Volume ETFs, defined as those with an average daily volume of more than $5 million, of which currently 244 (last week 150) are hovering in bullish territory. The yellow line separates those ETFs that are positioned above their trend line (%M/A) from those that have dropped below it.

Take a look:

The HV ETF Master Cutline Report

In case you are not familiar with some of the terminology used in the reports, please read the Glossary of Terms.

If you missed the original post about the Cutline approach, you can read it here.

ETF Tracker Newsletter For March 15, 2019

Ulli ETF Tracker Contact

ETF Tracker StatSheet

https://theetfbully.com/2019/03/weekly-statsheet-for-the-etf-tracker-newsletter-updated-through-03-14-2019/

ENDING A GOOD WEEK ON A POSITIVE

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

The quadruple witching hour came and went and ended up having a positive effect on equities, which more than made up for last week’s pullback. Along the way, traders ignored the unreliable news reports about the U.S.-China trade negotiations as well as China’s latest data showing that their economic slowdown is alive and well.

To elaborate, today is “quadruple witching” Friday, when contracts for stock-index futures, stock index options, individual stock options and individual stock futures all expire. This can lead to increased volatility, which simply means today’s market direction is not a guarantee of things to come.

As a matter of fact, the opposite is a likely possibility, which ZH explains this way:

The risk is that both prior “witches” took place just ahead of major reversals in the S&P, the first in September, just as the market peaked, the second in December, just before the trough.

 For now, however, it is shaping up as another impressive week for US stocks, which have not only erased all of last week’s losses but are set for their second-best week of the year.

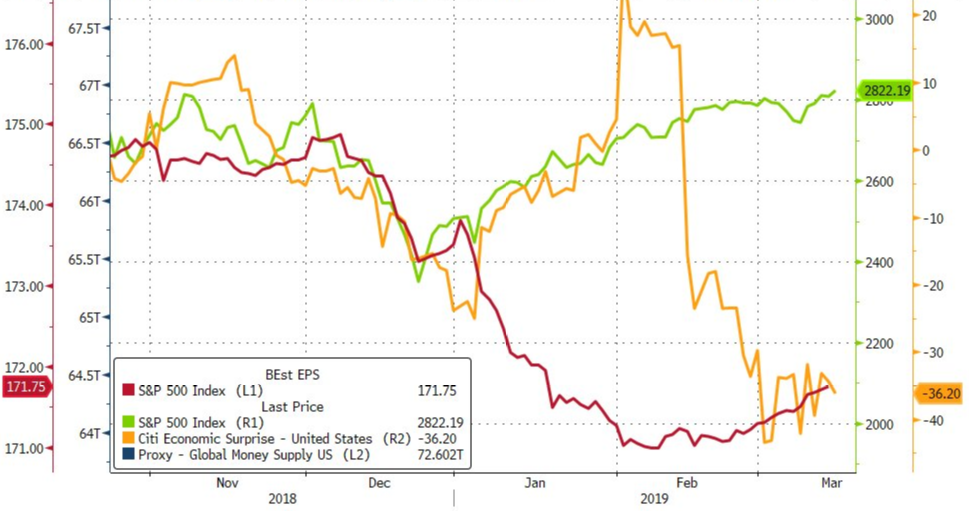
Bond market action surprised with the 10-year yield plummeting and closing at not only 2019 lows but also at the lowest since January 2018, while equities continued their relentless march to loftier heights, as the divergence widened. Even sliding EPS expectations and weakening macro data don’t seem to be able to contain the push to higher levels—at least not yet.

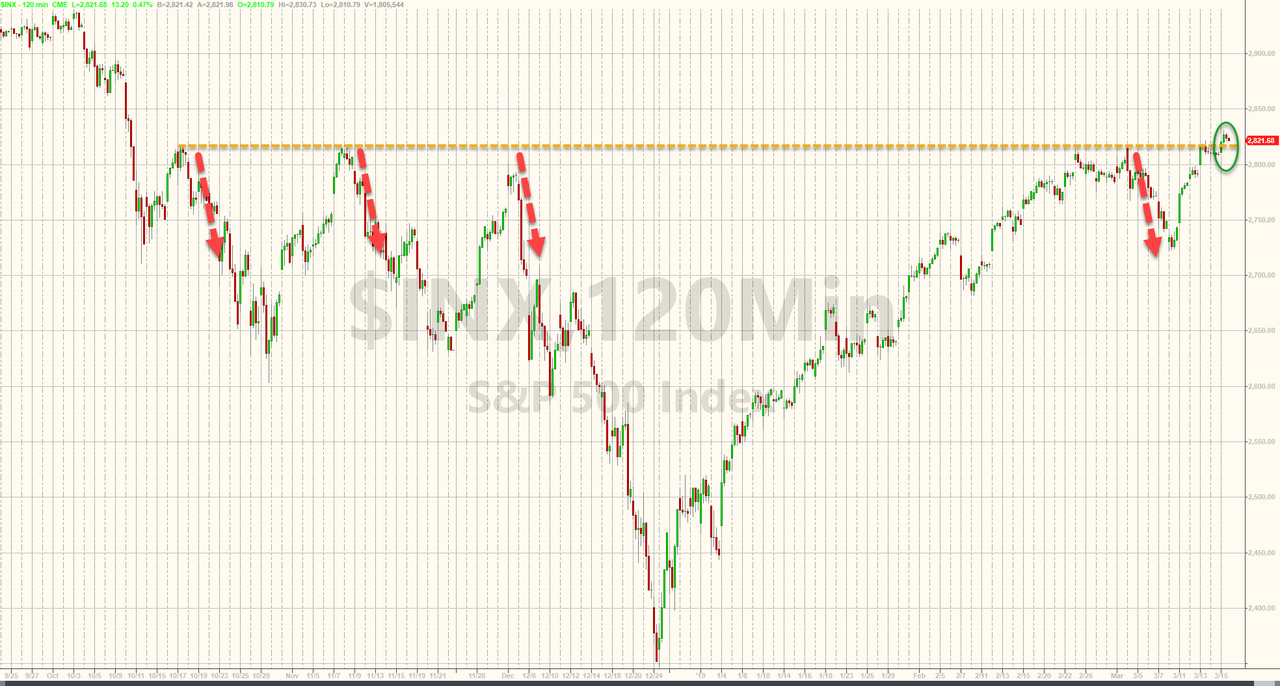
The S&P 500 finally managed to conquer and close above the 2,817 zone at the 5th attempt, but more work is needed in order to close in on the all-time high made  in September 2018.

Our Trend Tracking Indexes (TTIs) rallied along with the major indexes this week and climbed deeper into bullish territory. That does not mean we are complacent, but we are very aware that volatility could return with a vengeance. That is why our exit strategy remains in place, just in case bearish forces suddenly gain the upper hand again.

Read More