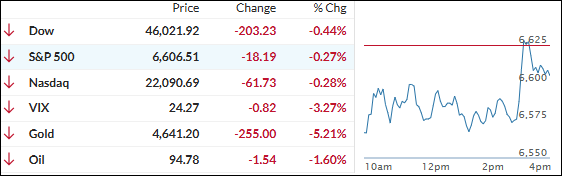
[Chart courtesy of MarketWatch.com]
- Moving the market
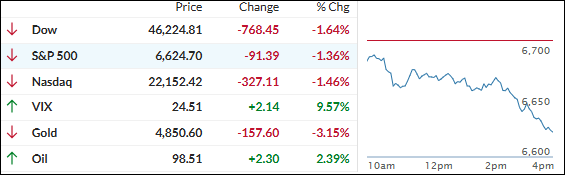
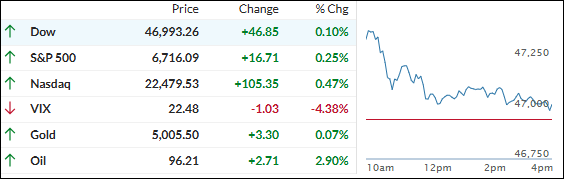
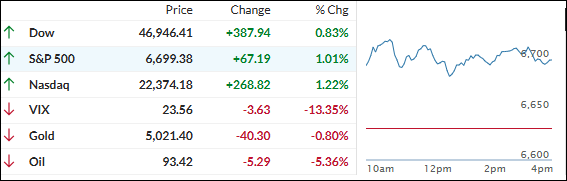
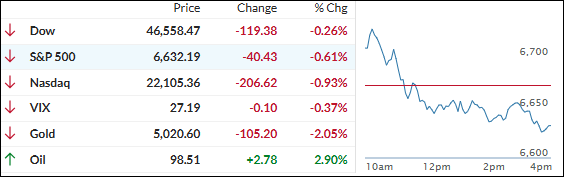
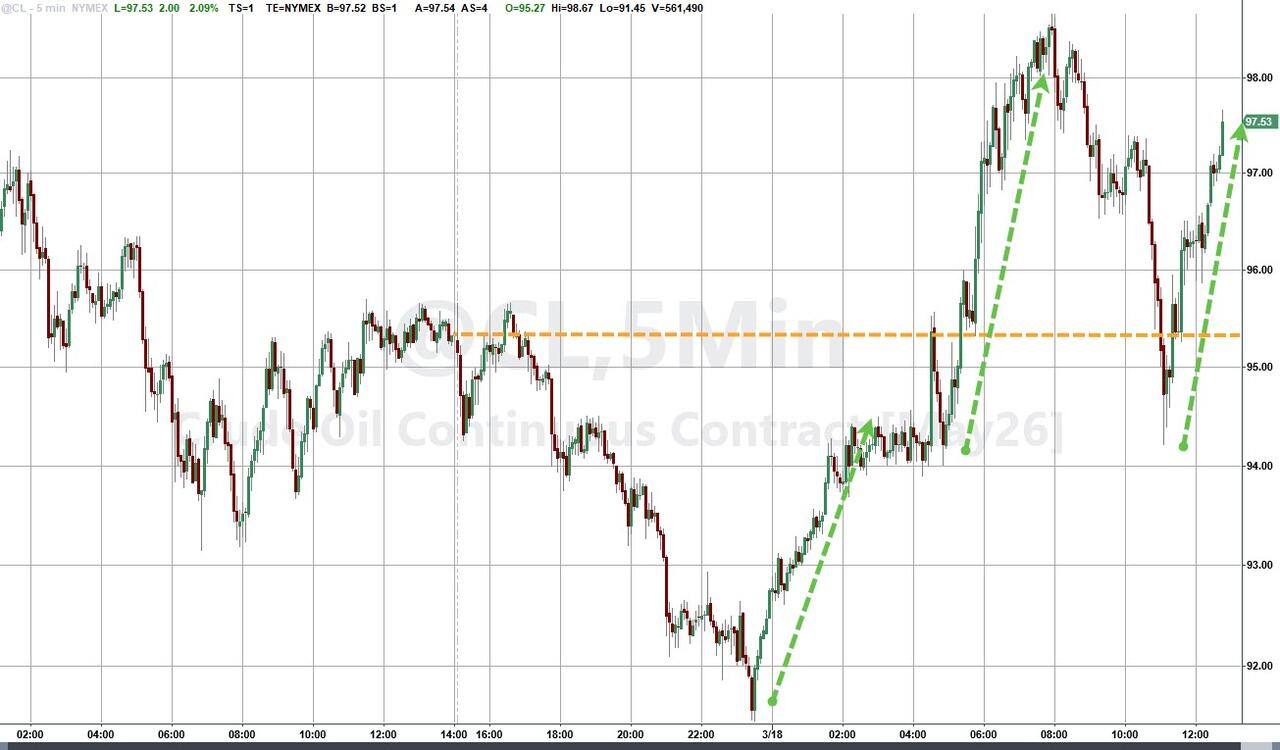
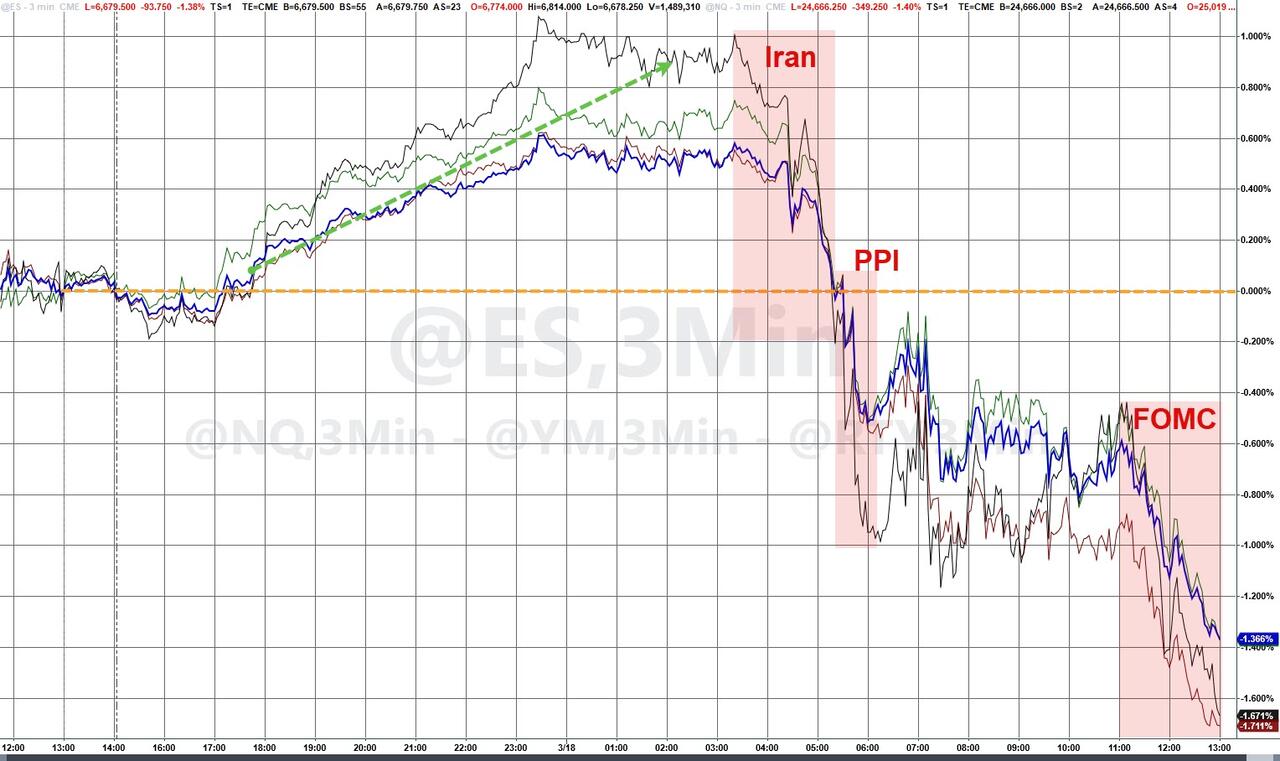
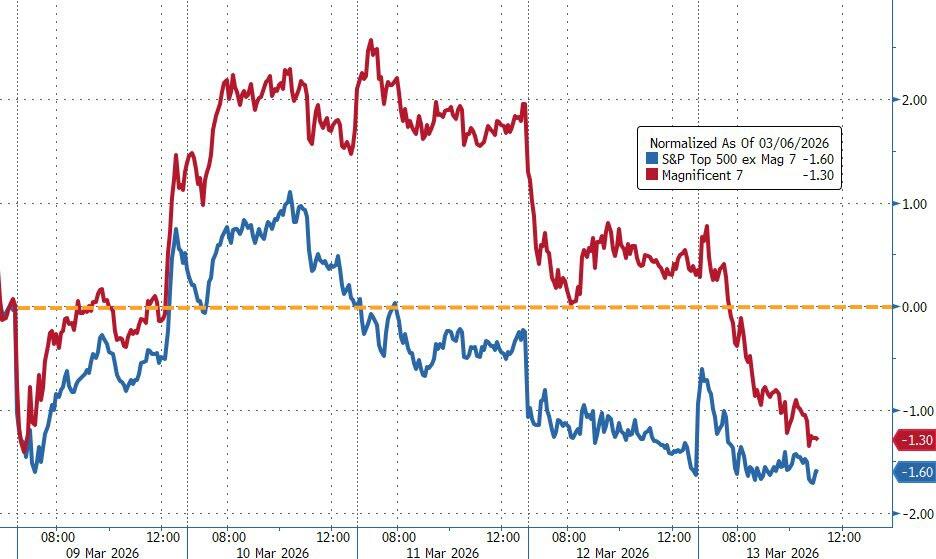
The major indexes opened weak and stayed under pressure for most of the day, as oil prices kept climbing on fresh worries from the U.S.-Iran conflict.
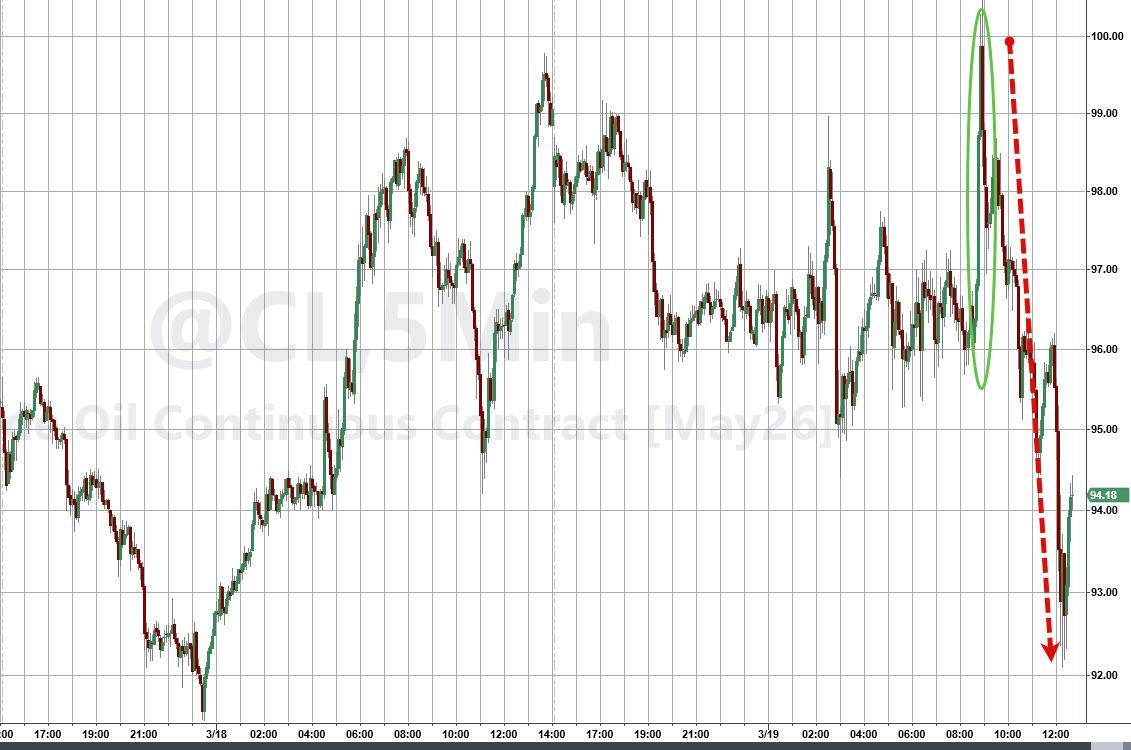
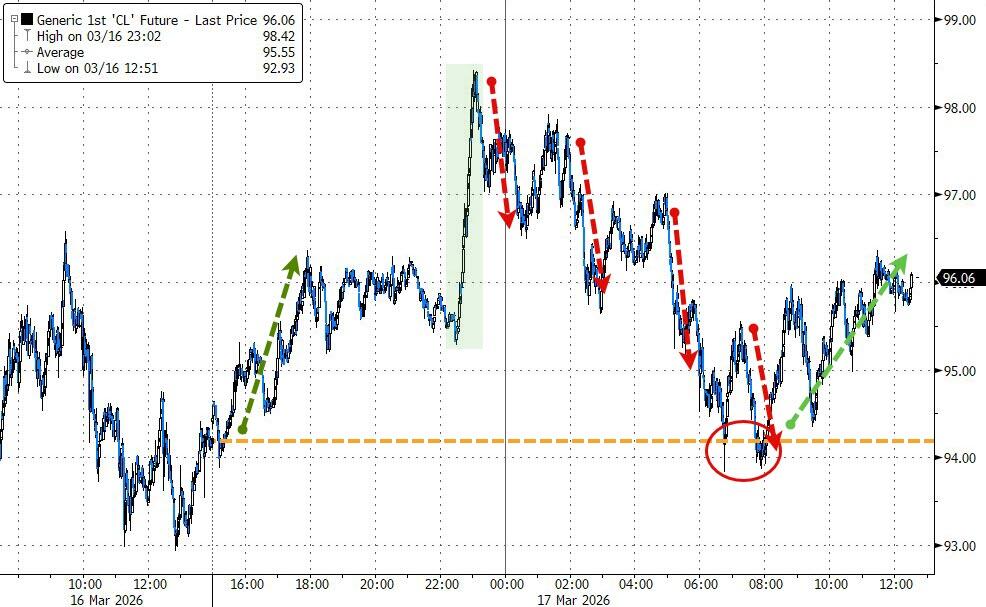
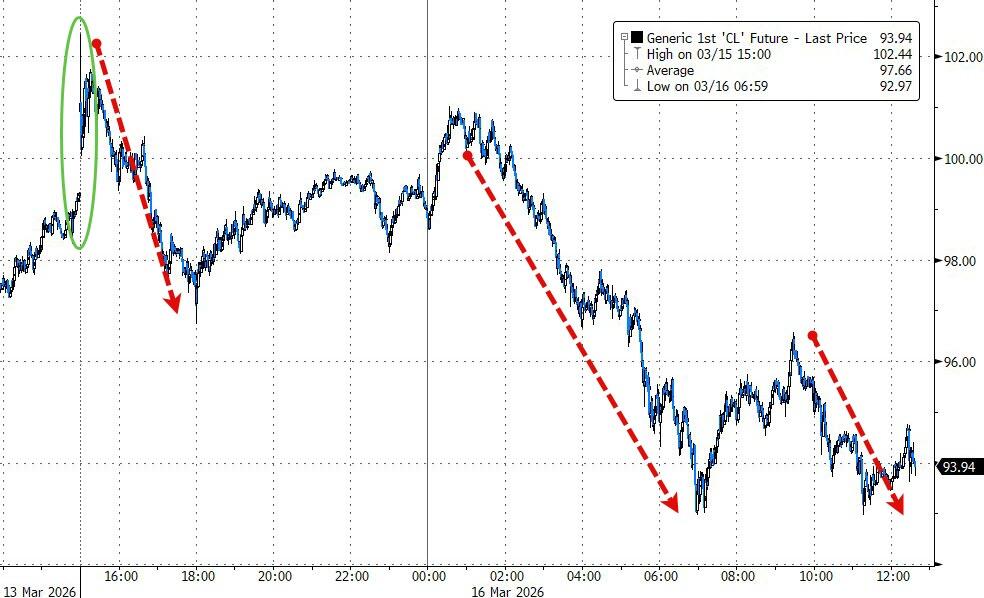
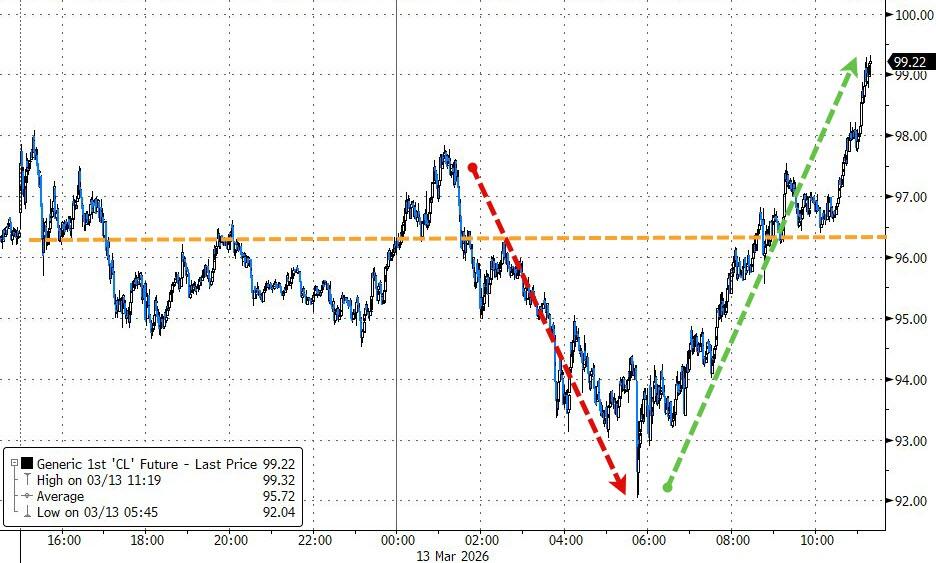
West Texas Intermediate crude swung between $93 and $100 a barrel, while Brent surged 3% to $111 after Iran struck a key LNG export facility in Qatar and Israel hit Iran’s South Pars gas field.
Iran retaliated by targeting Qatari energy sites, and President Trump warned that any more attacks on Qatar would lead to the U.S. “massively blowing up” the South Pars field.
One analyst summed it up: the U.S. and Israel have “won” the conventional war, but there’s no quick military fix for reopening the Strait of Hormuz without ground troops—meaning diplomacy is the only real path back to normal supply.
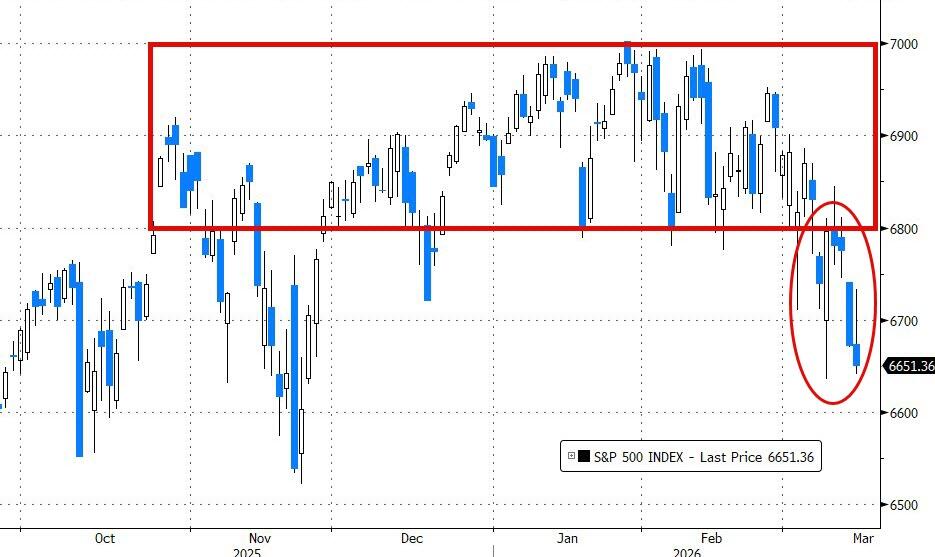
That energy shock kept the risk-off mood alive, with the S&P 500 and Dow closing lower (the S&P almost lost its 200-day moving average). The Nasdaq felt the tech weakness too.
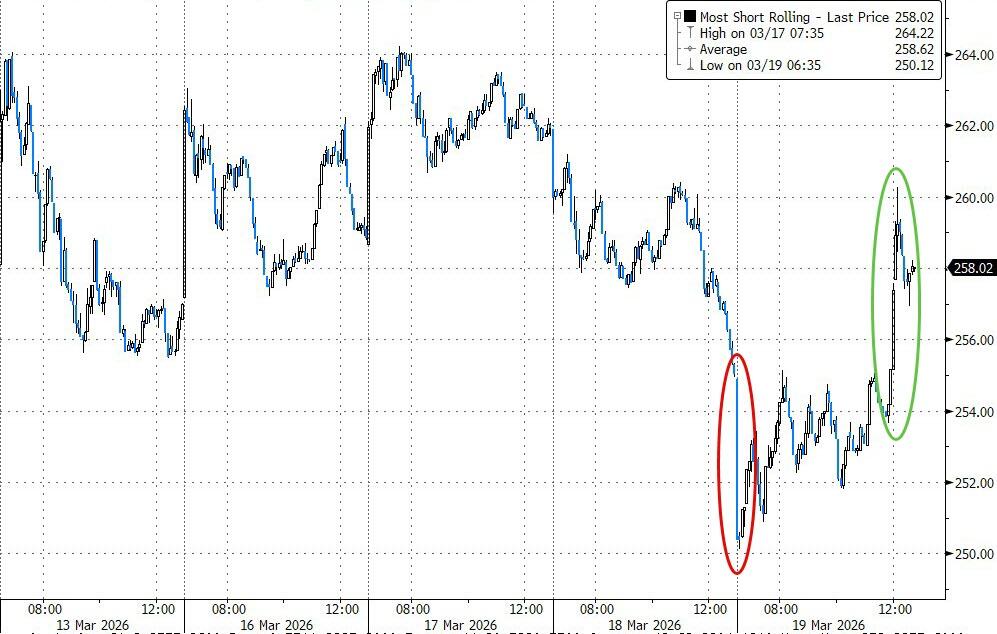
Small caps were the outlier, outperforming thanks to a big short squeeze that pushed them into the green.
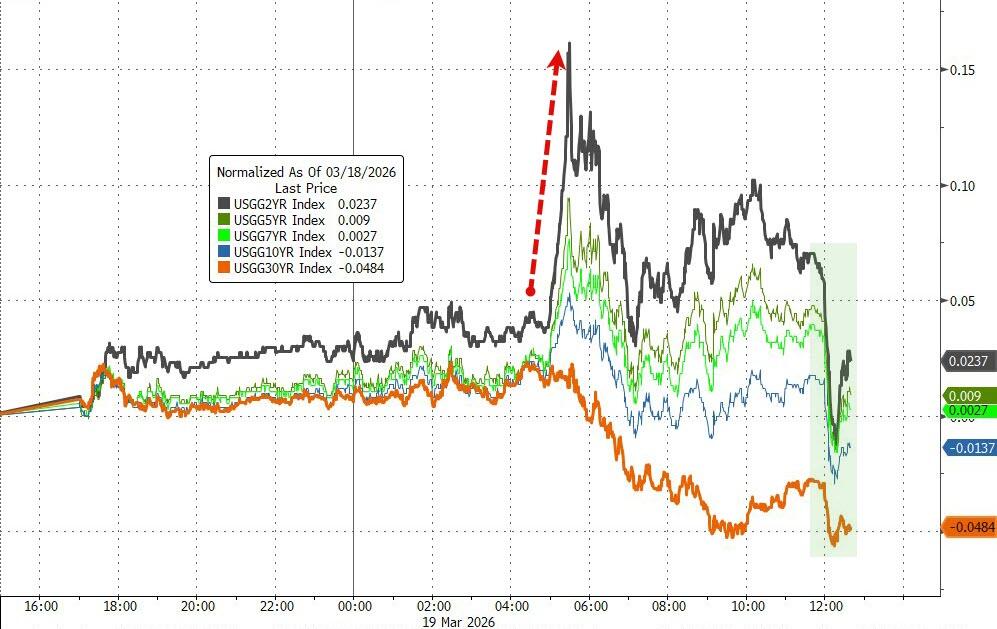
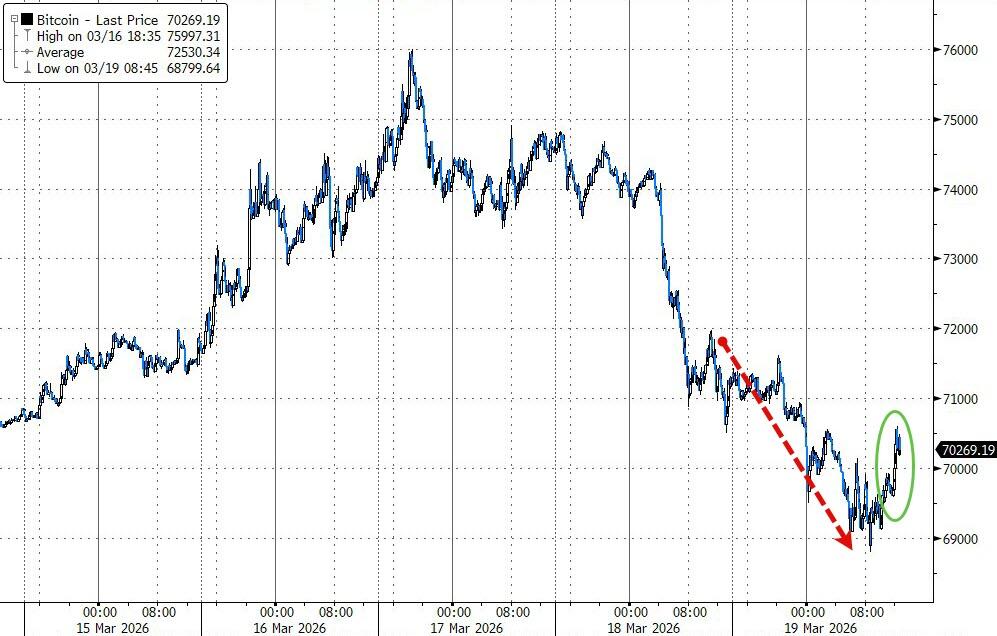
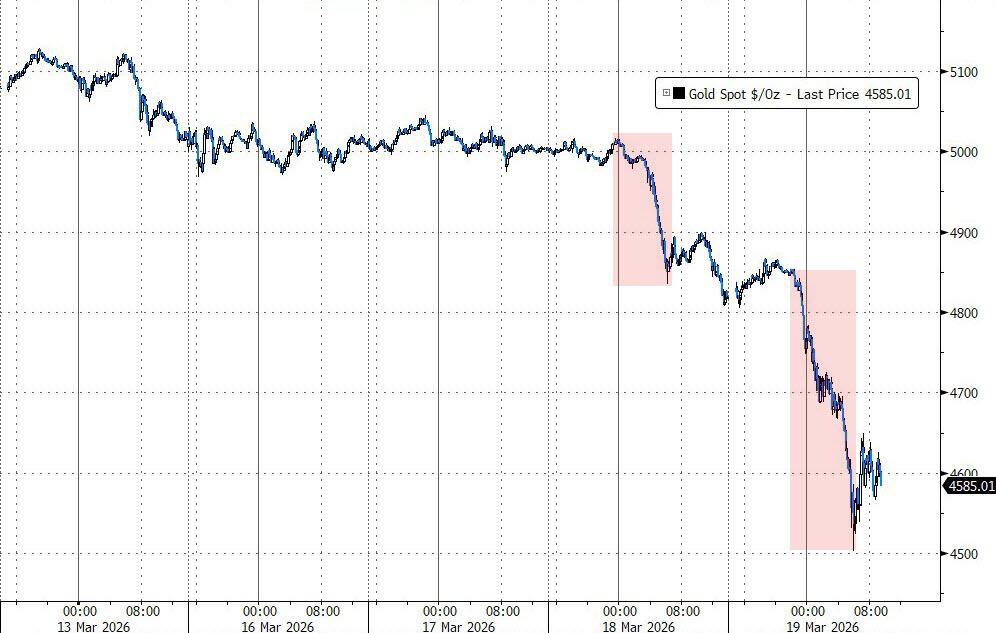
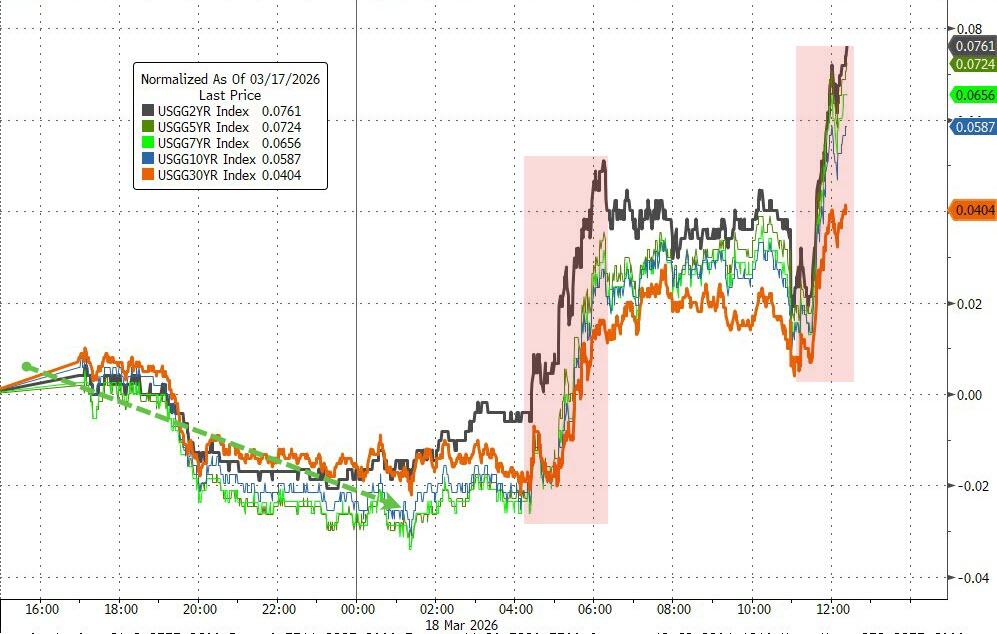
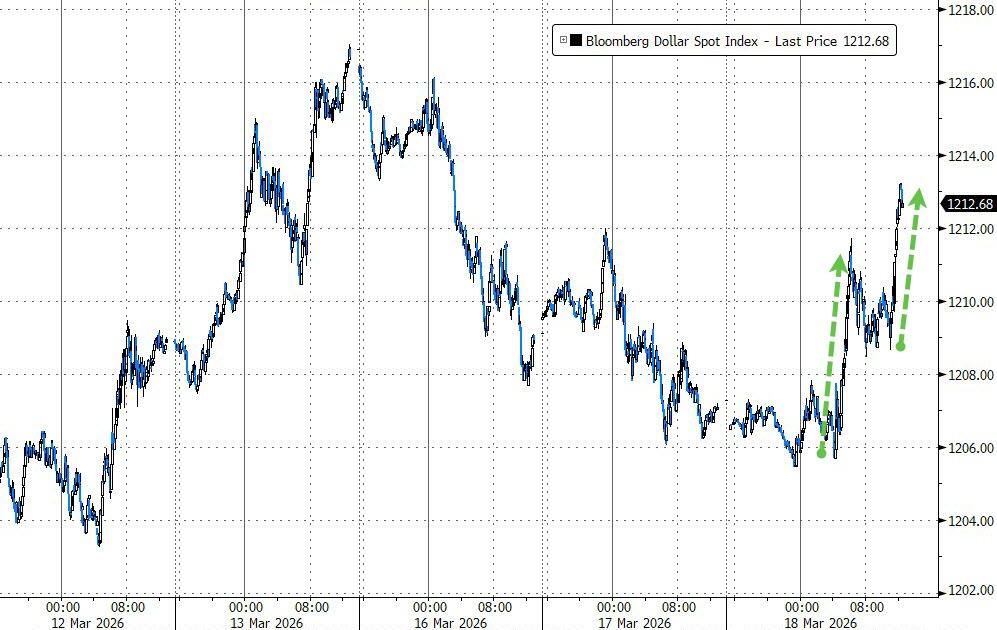
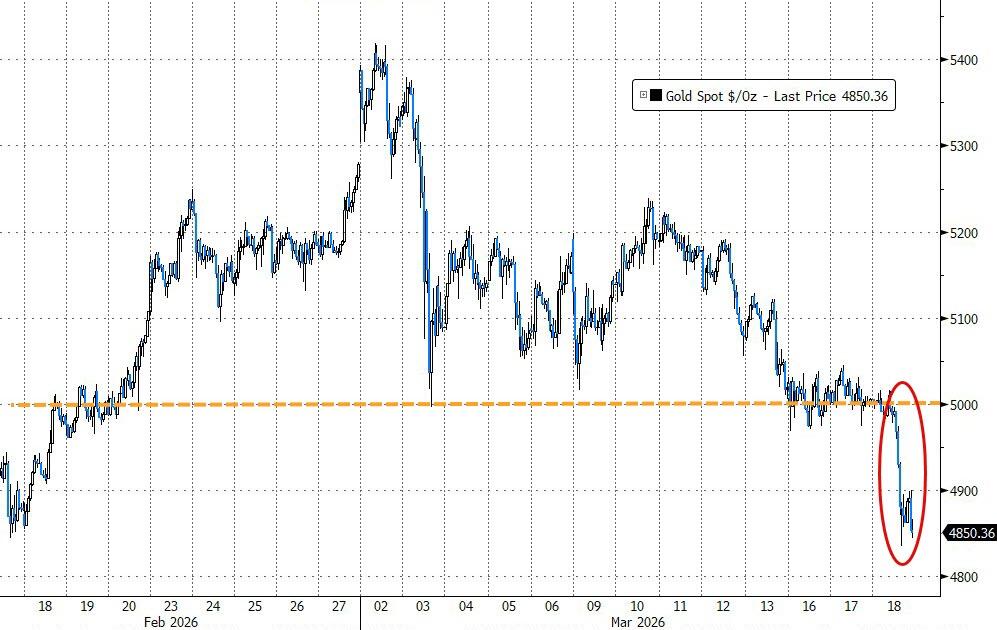
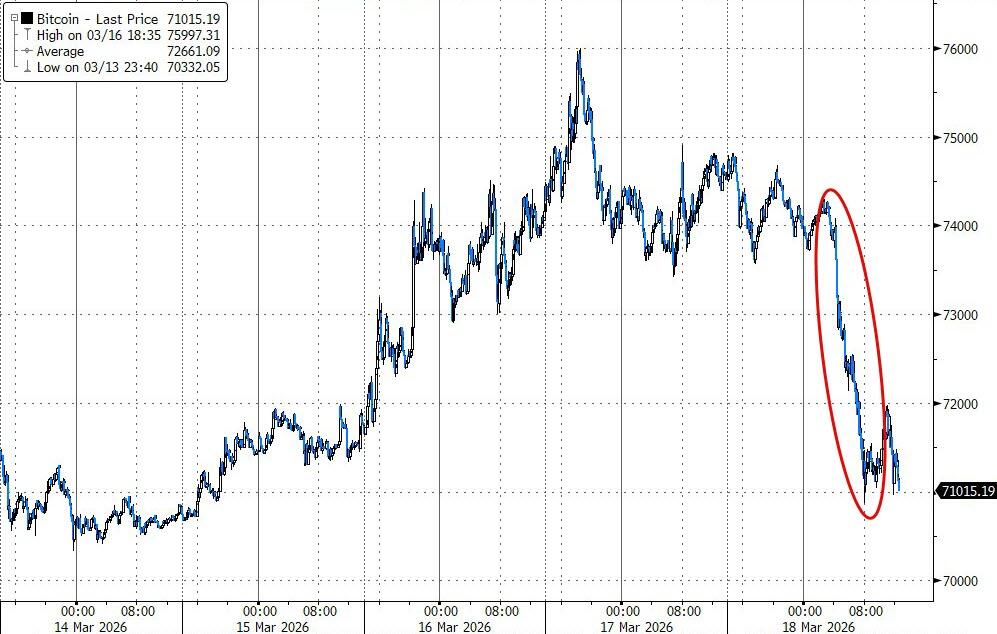
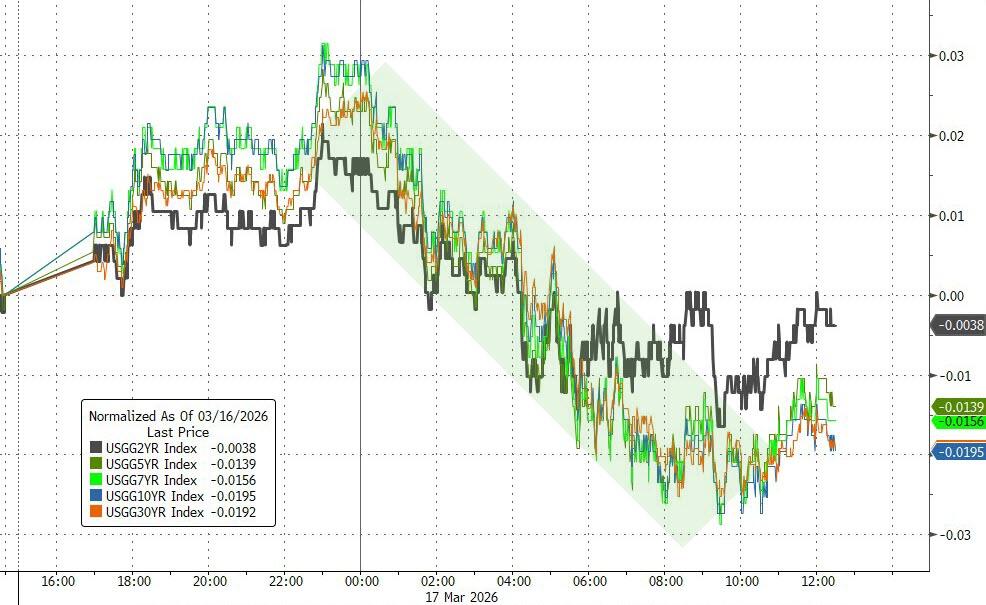
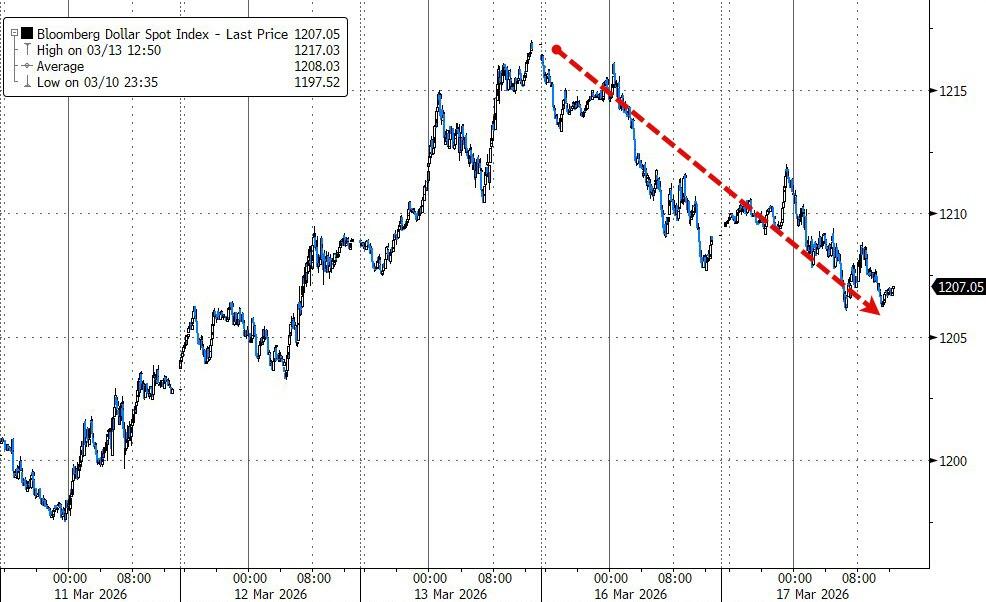
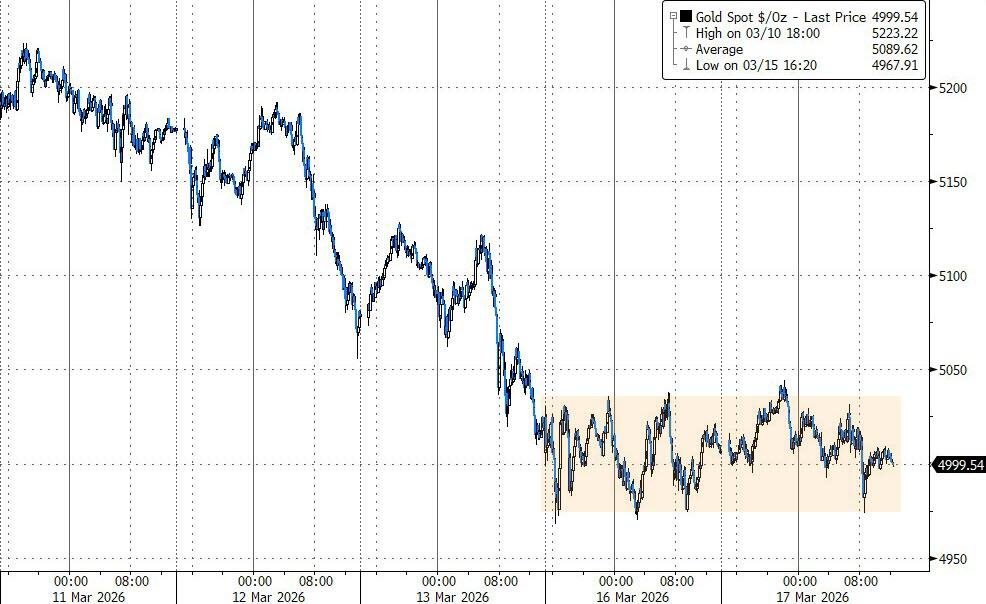
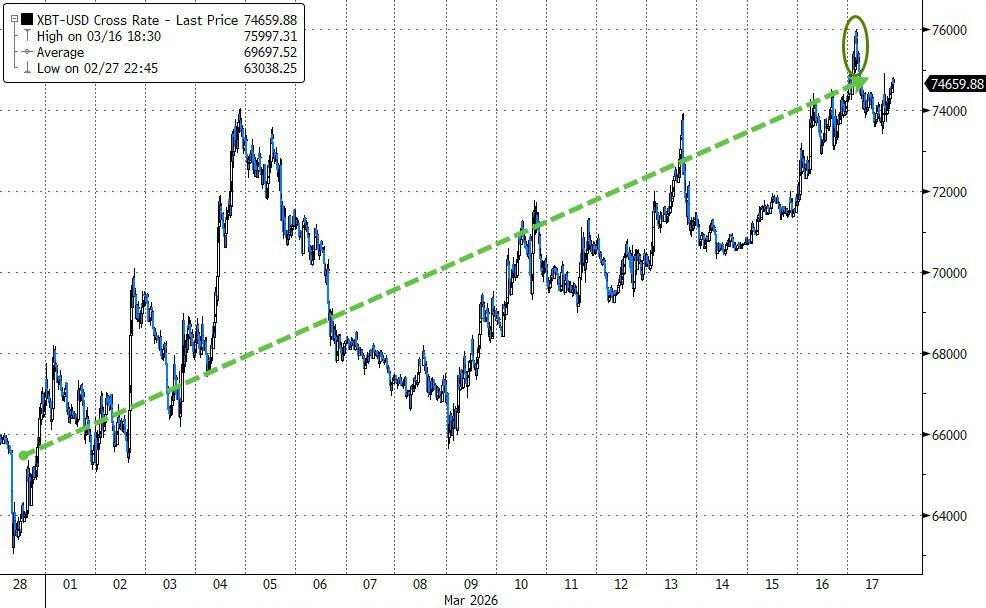
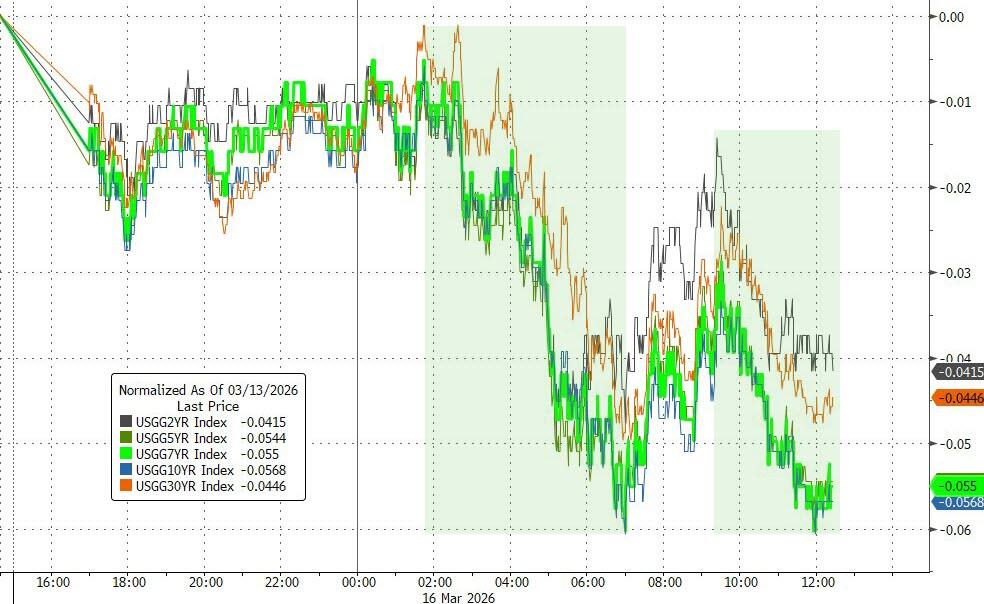
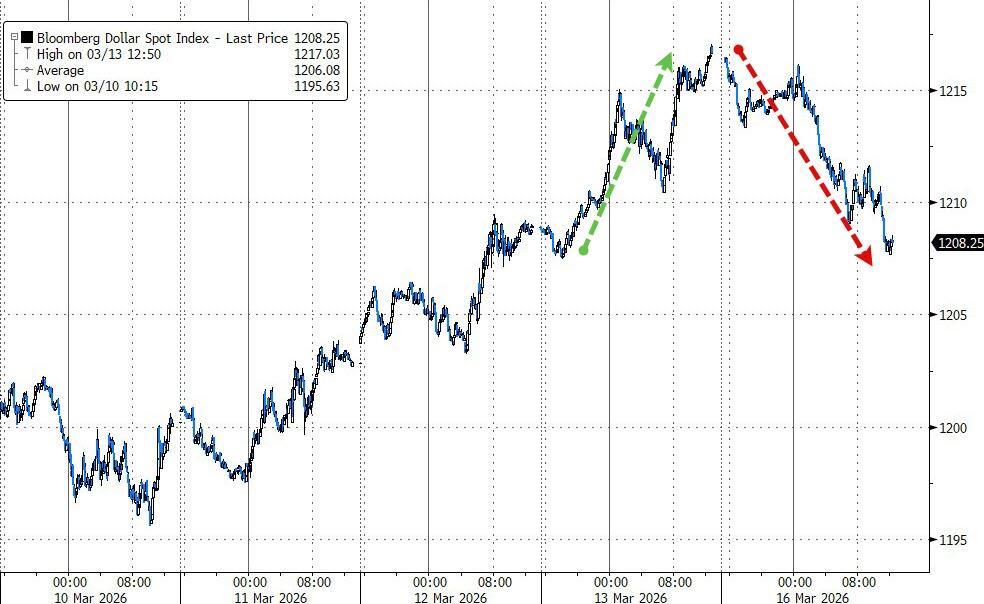
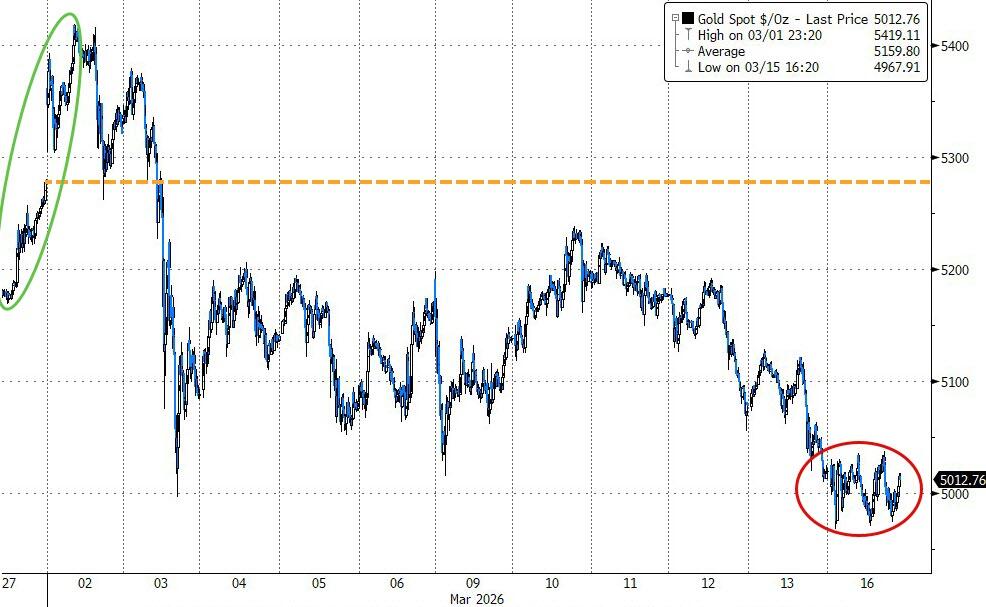
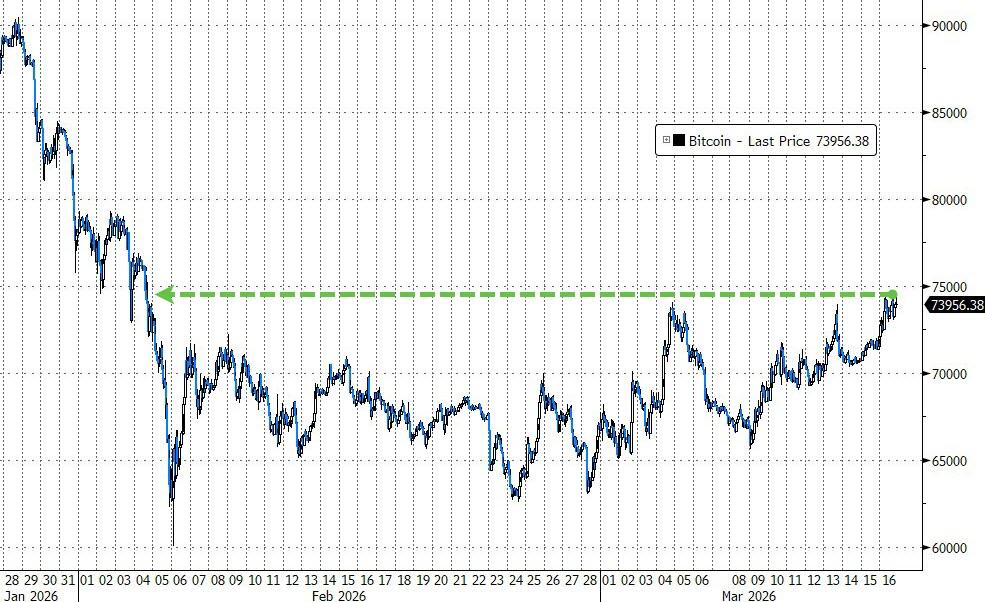
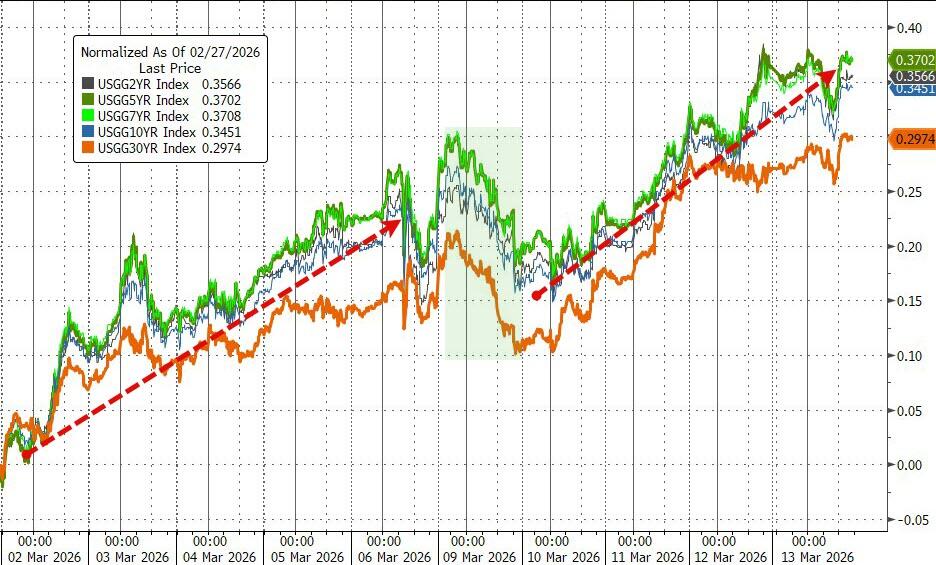
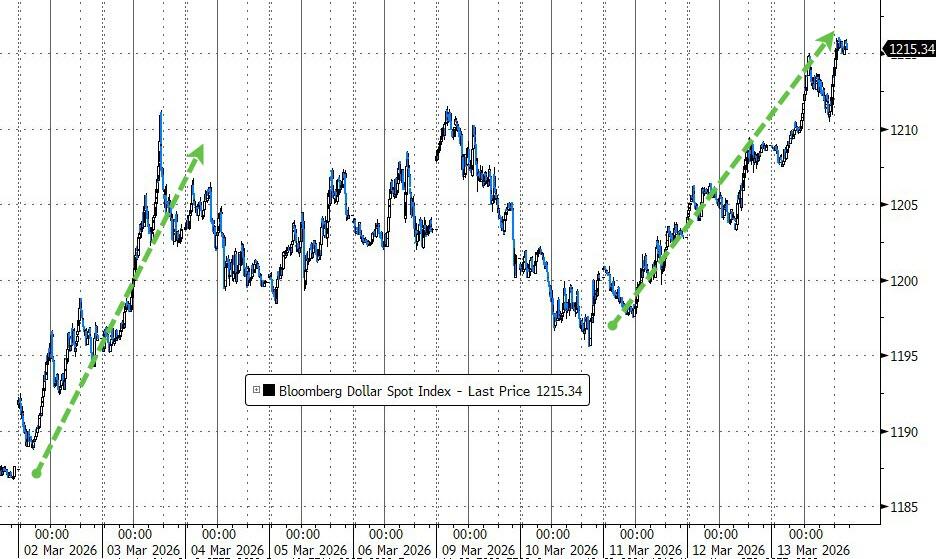
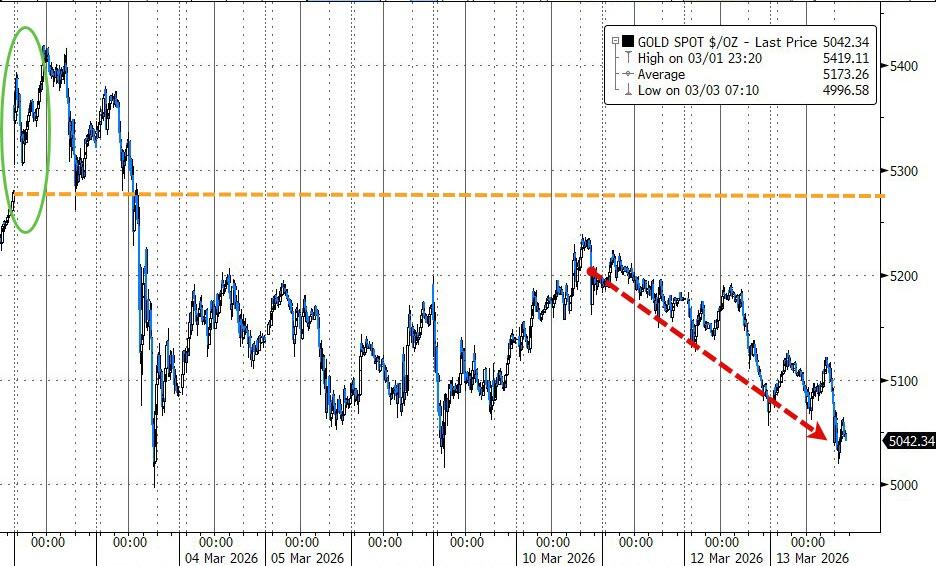
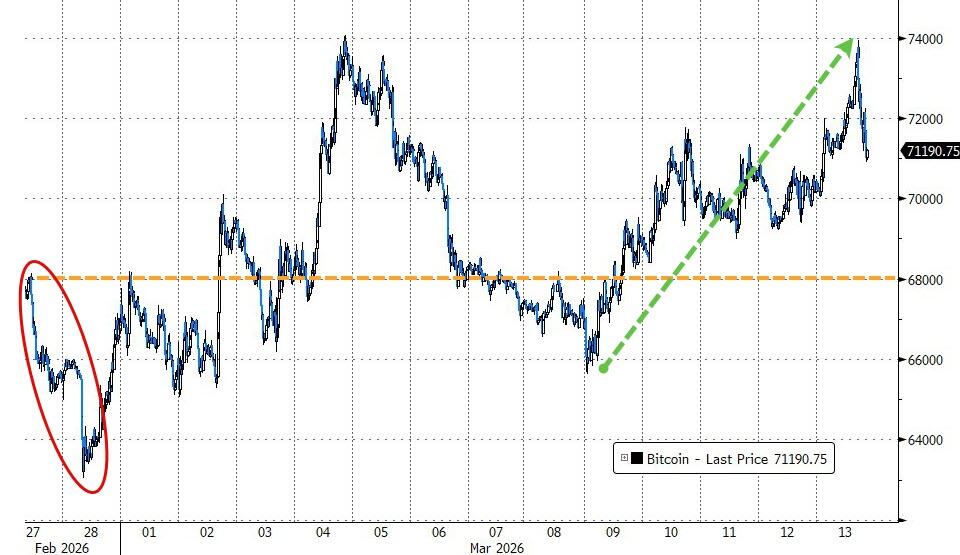
Bond yields surged midday but ended about flat, the dollar had an ugly day, gold got spanked again, and Bitcoin dipped but found support at $69K and popped into the close.
The metals complex is in a long-overdue correction after its huge run-up, but my long-term view remains bullish. The big legs lower in gold this week happened during Asia and Europe sessions, likely tied to strains in global dollar funding—if there’s a dollar shortage, gold gets sold first.
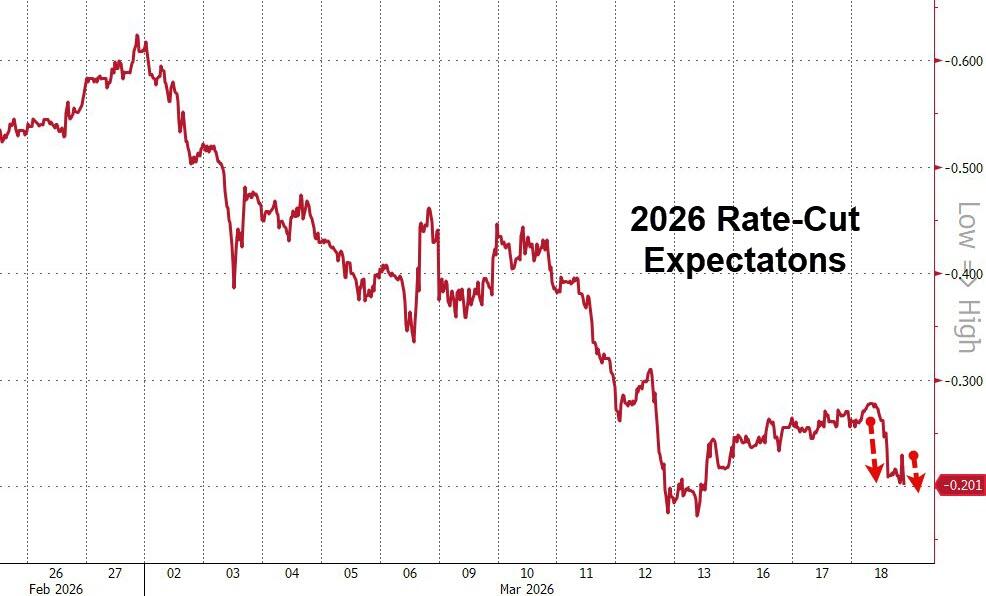
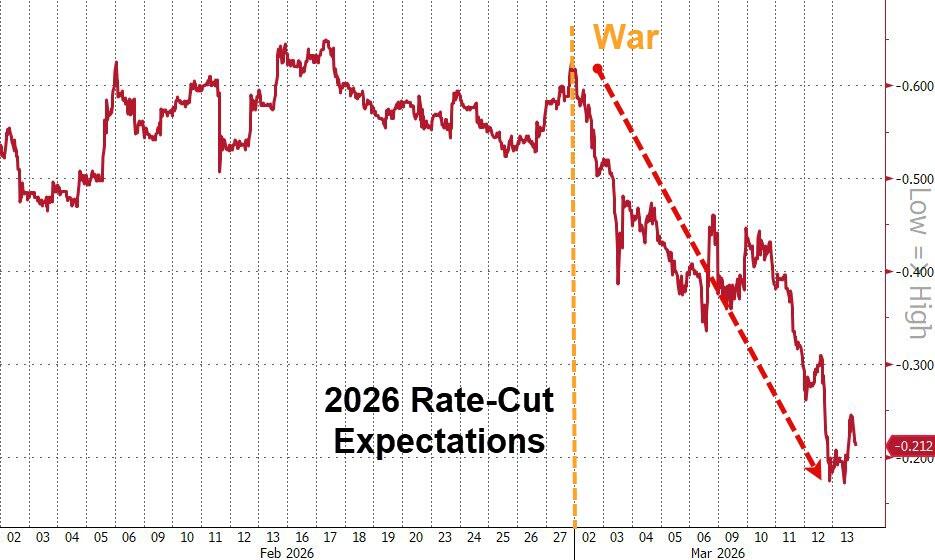
Big picture: the energy shock means higher inflation, slower growth, and a less accommodative Fed—unless a funding crisis forces emergency rate cuts.
Today’s weakness adds to the chop we’ve seen, but the underlying trend hasn’t broken yet.
Read More