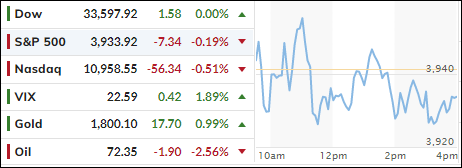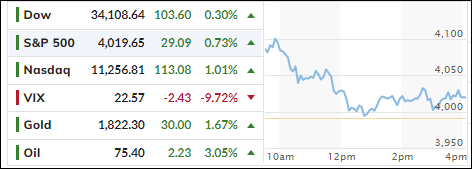
[Chart courtesy of MarketWatch.com]
- Moving the markets
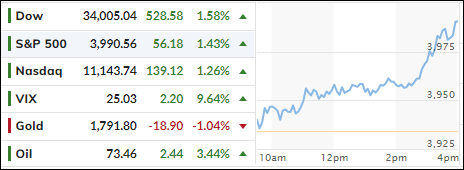
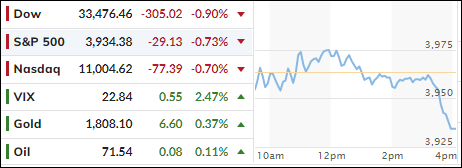
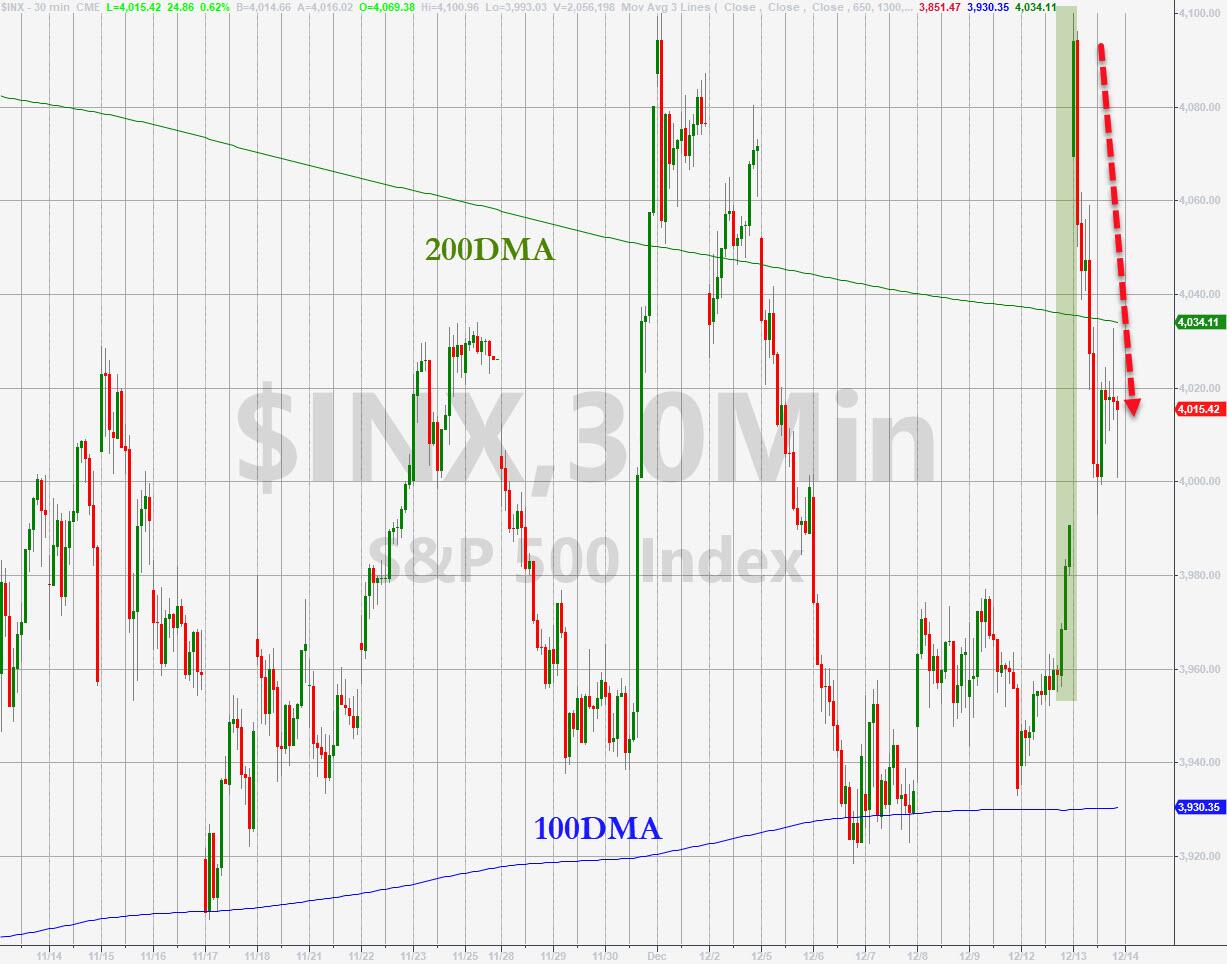
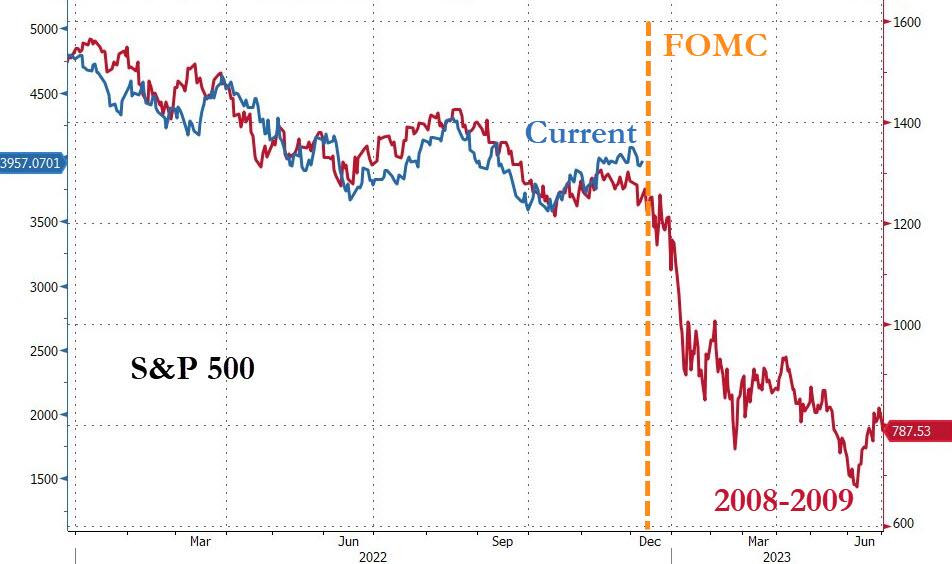
After the release of the highly anticipated CPI report, which came in “cooler” than expected, the major indexes stormed ahead with the Dow scoring a quick 400-point gain. The S&P 500 recouped its 200-day M/A but gave back that “victory” later in the session.
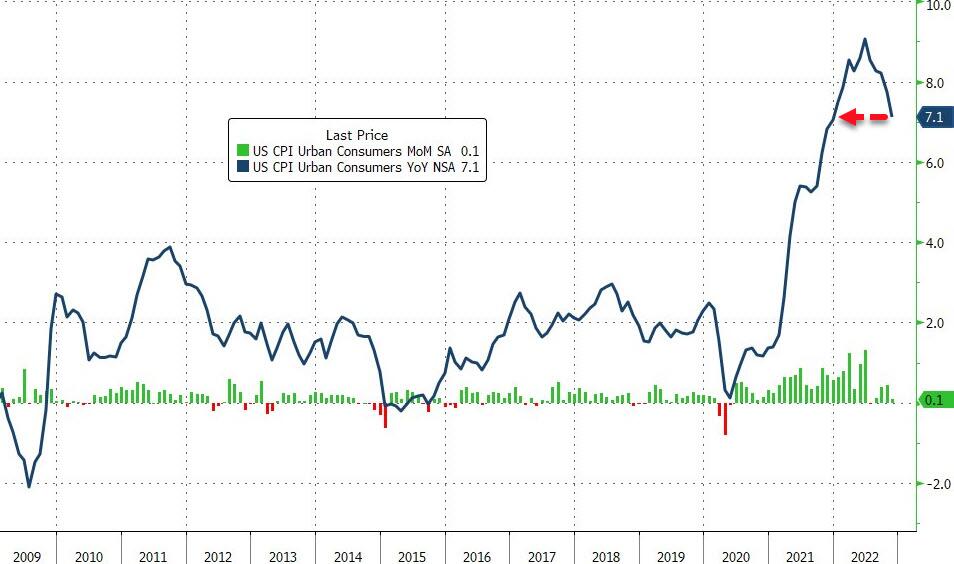
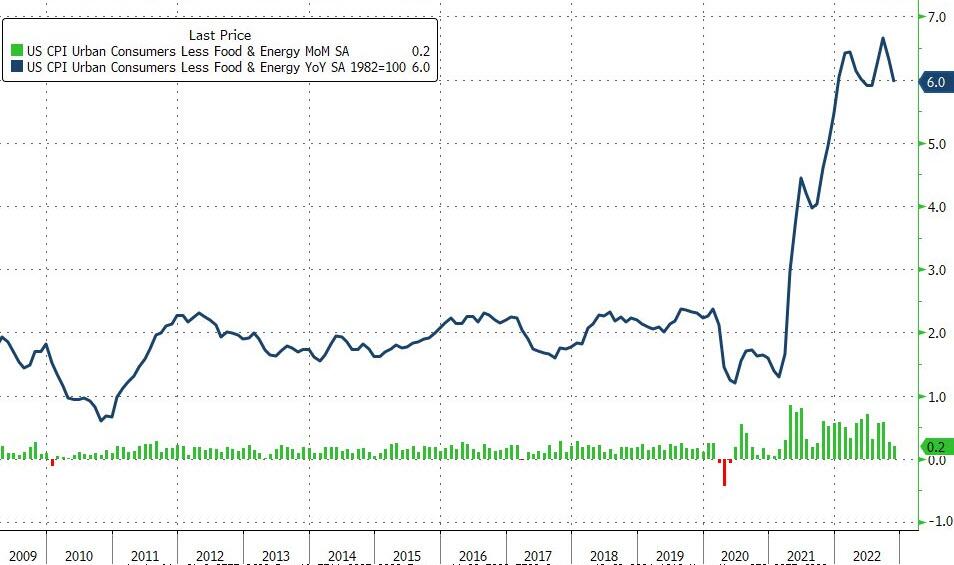
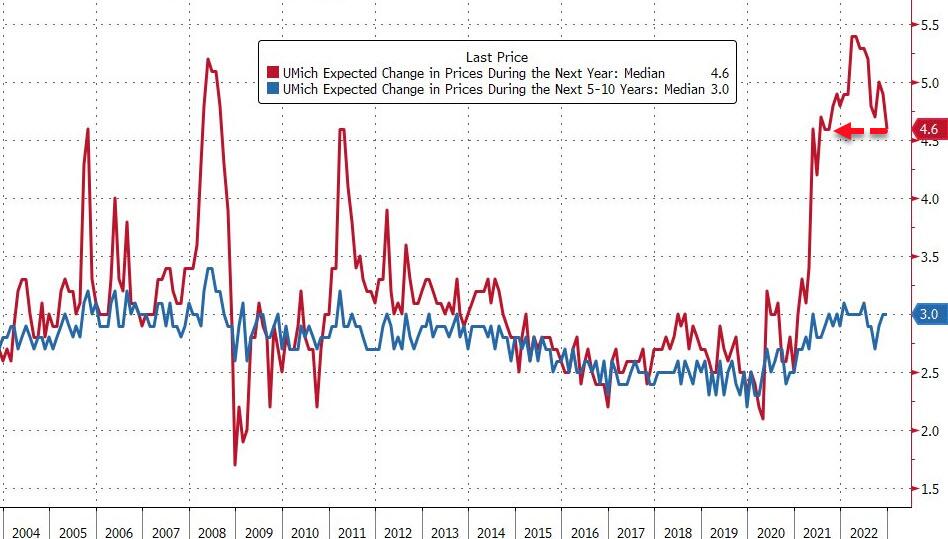
The CPI increased just +0.1% from the prior month and +7.1% YoY vs. expectations of +0.3% and +7.3% respectively. The core-CPI (without food and energy) rose +0.2% MoM and +6.1% YoY.
This are still horrific inflation numbers, but they were good enough for bullish juices to be released. However, early enthusiasm faded fast, as the major indexes dove back to their unchanged lines, and only managed to end the session with a moderate rebound but at least eking out a green close.
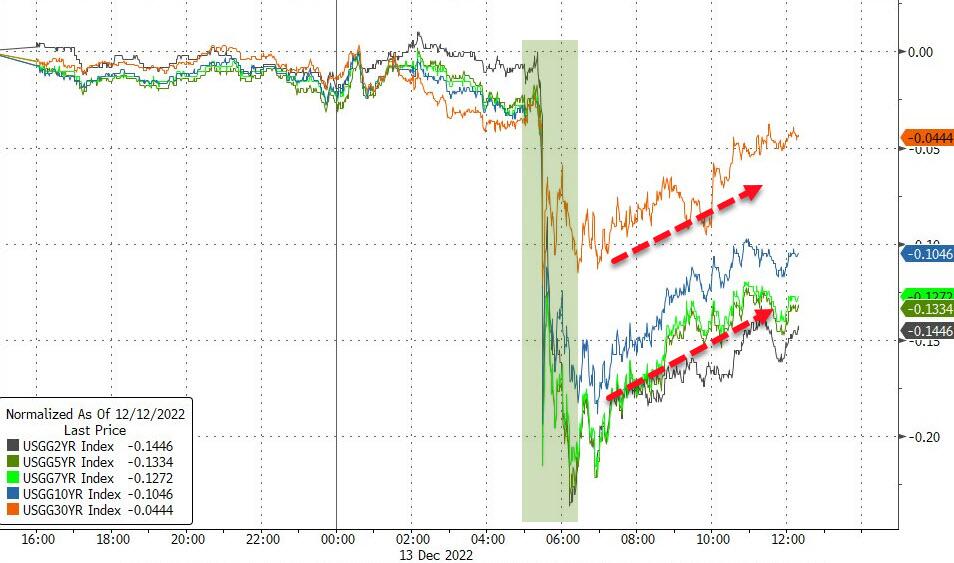
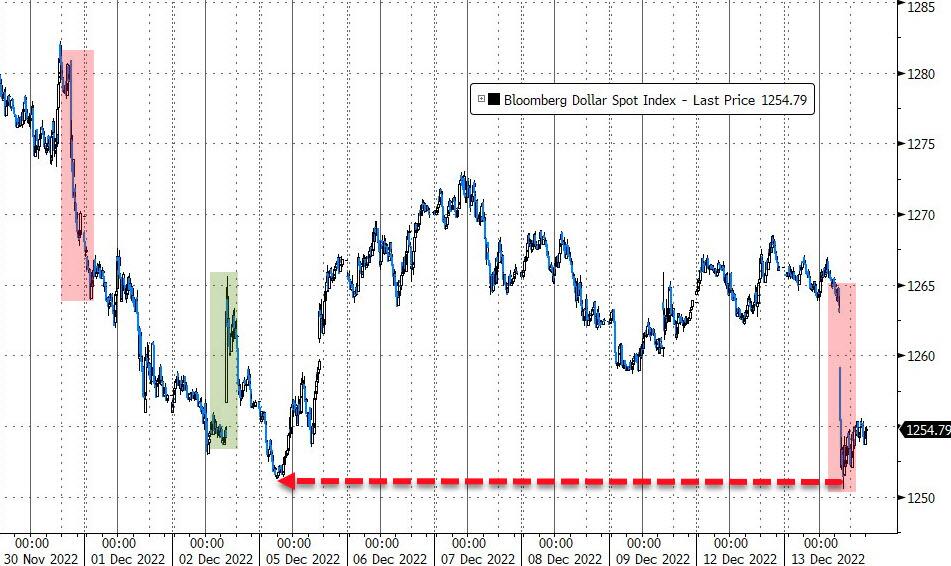
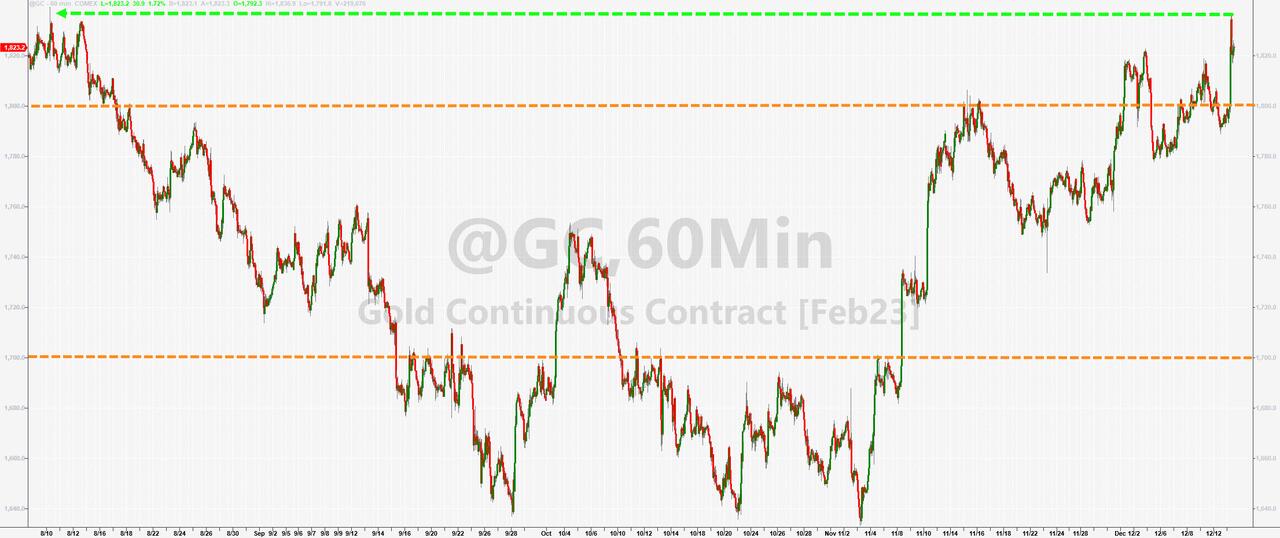
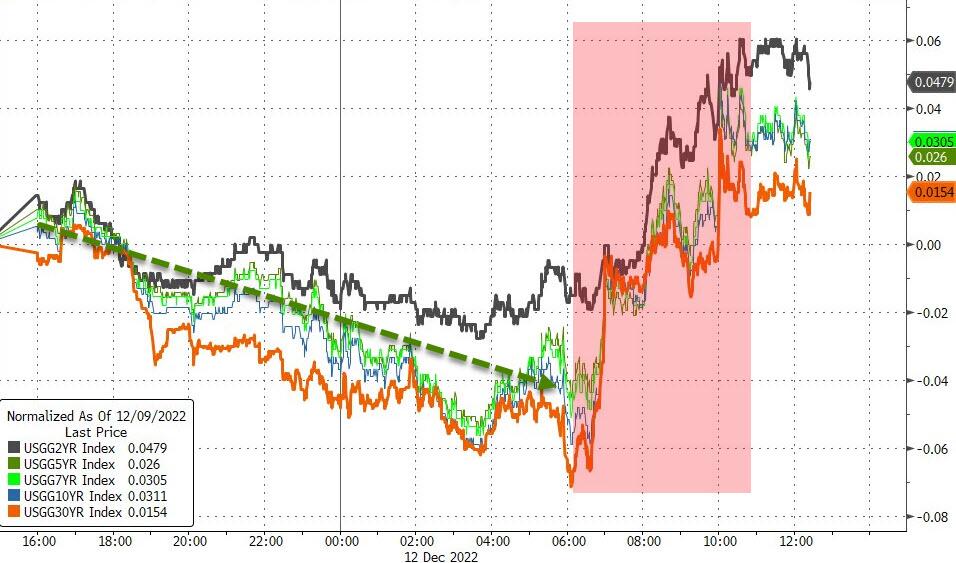
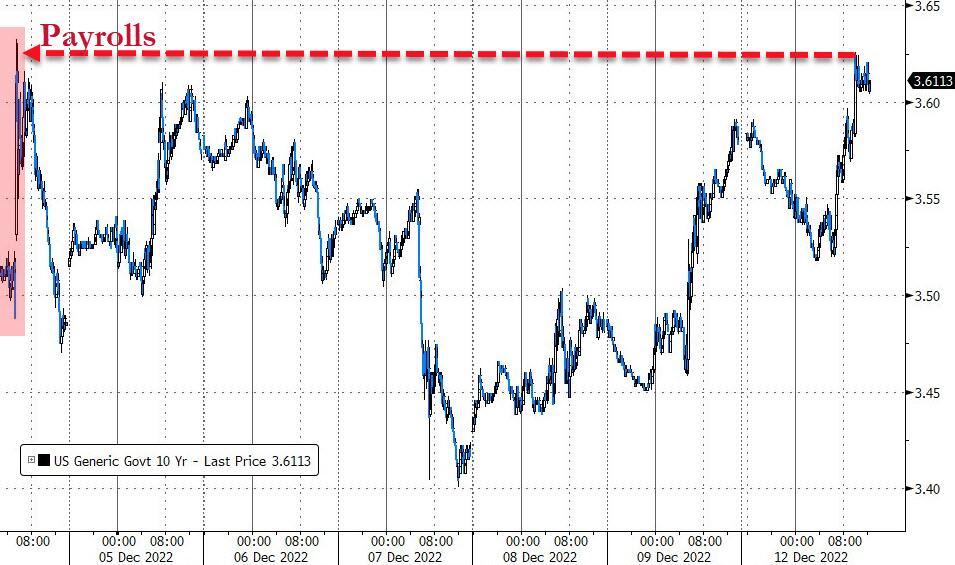
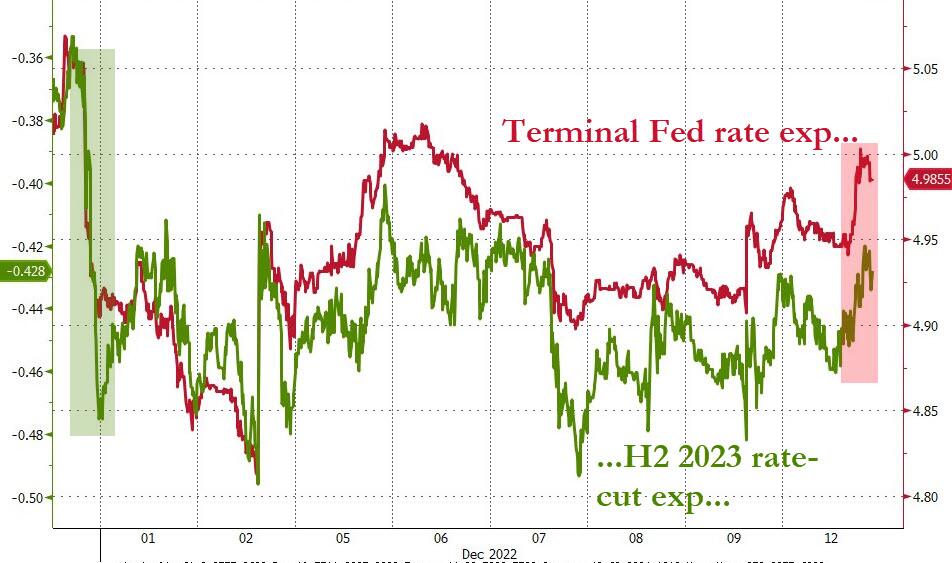
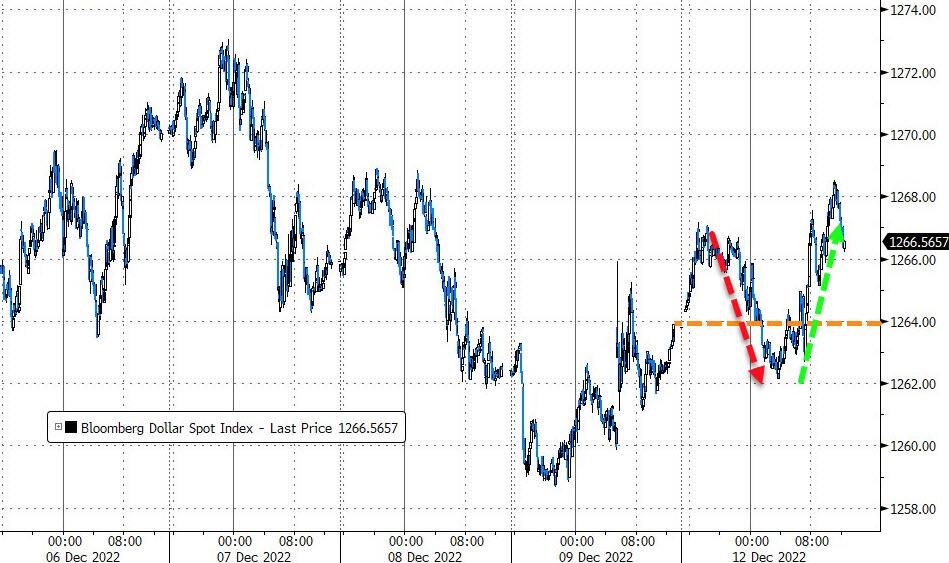
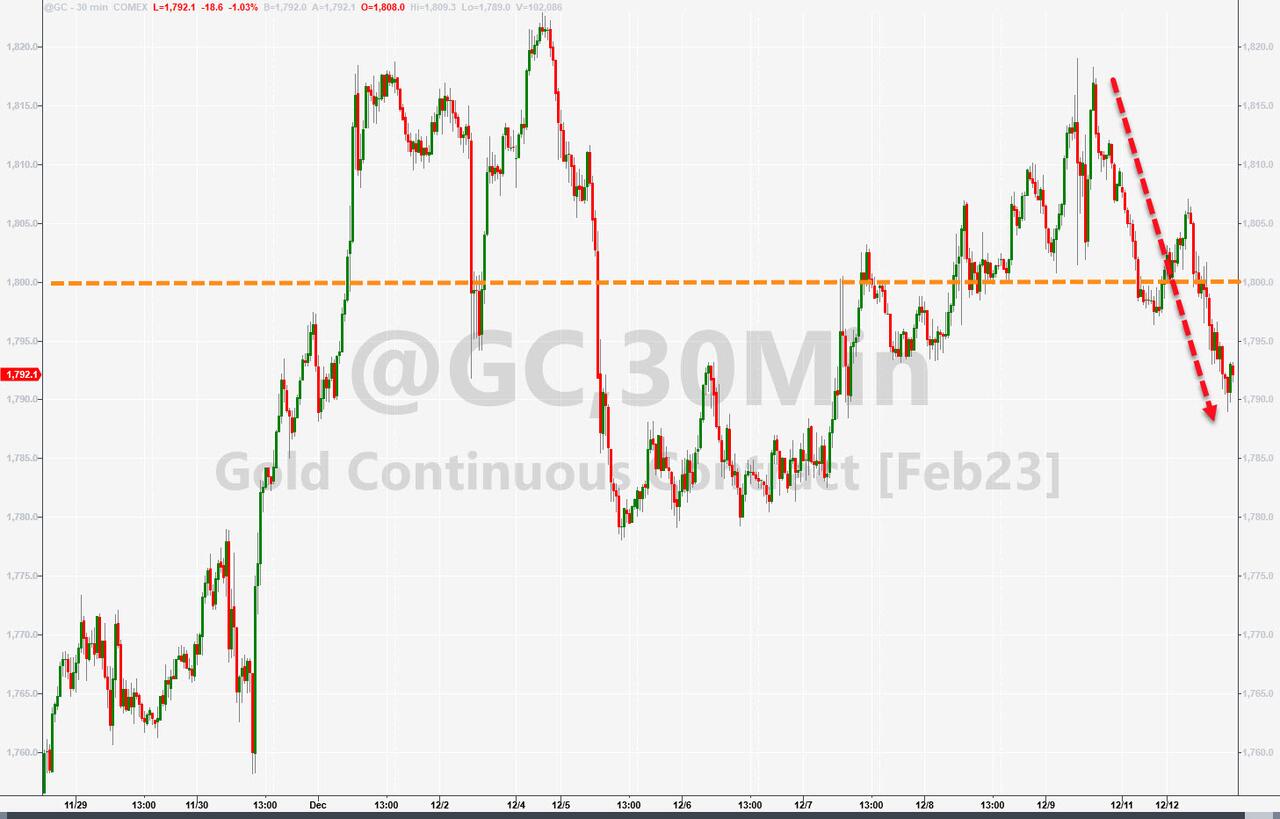
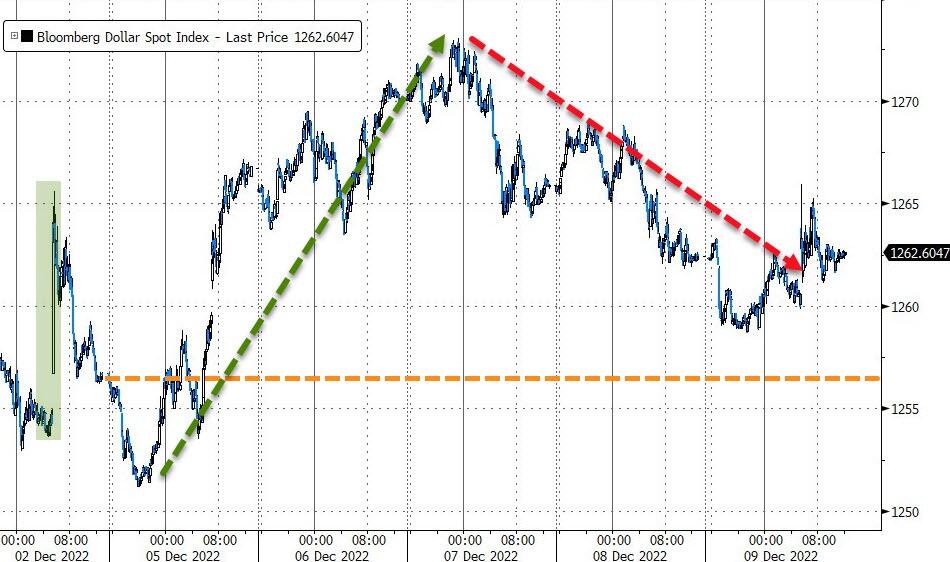
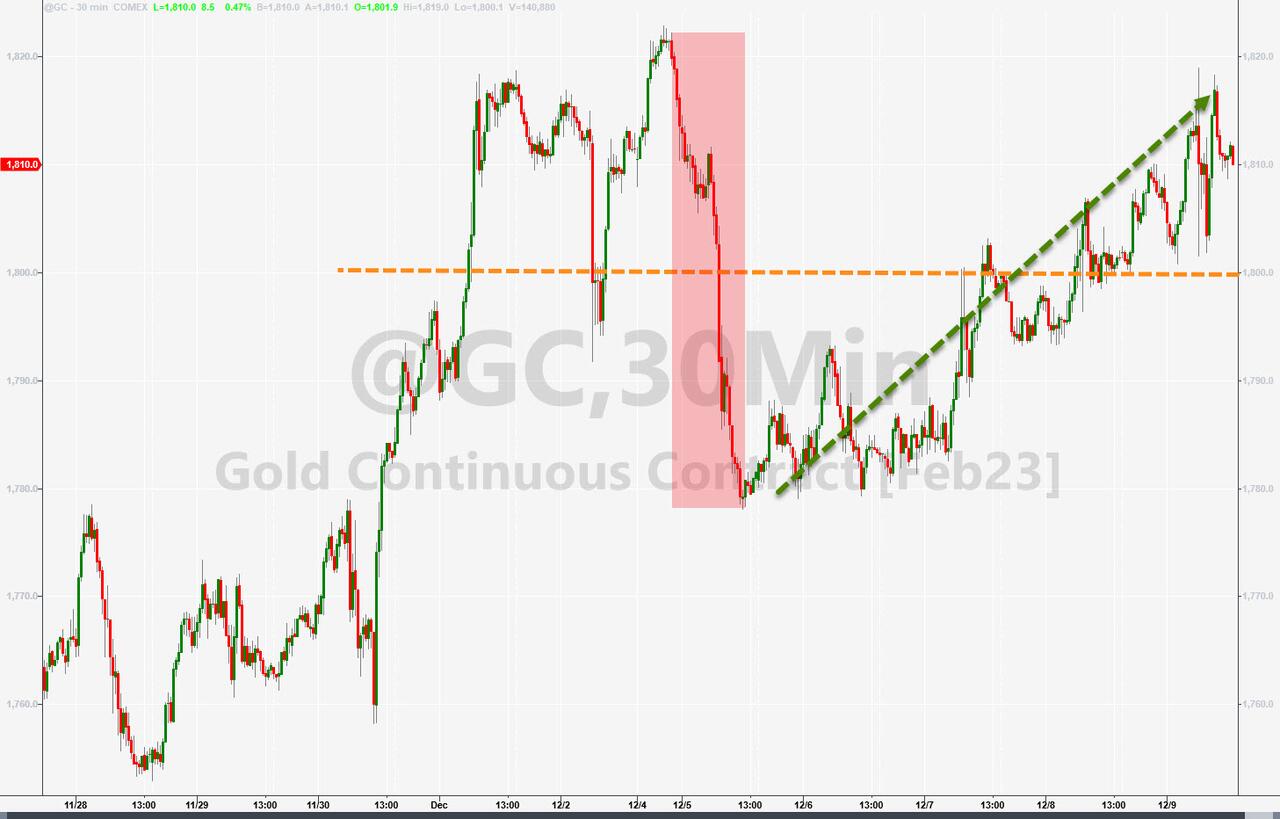
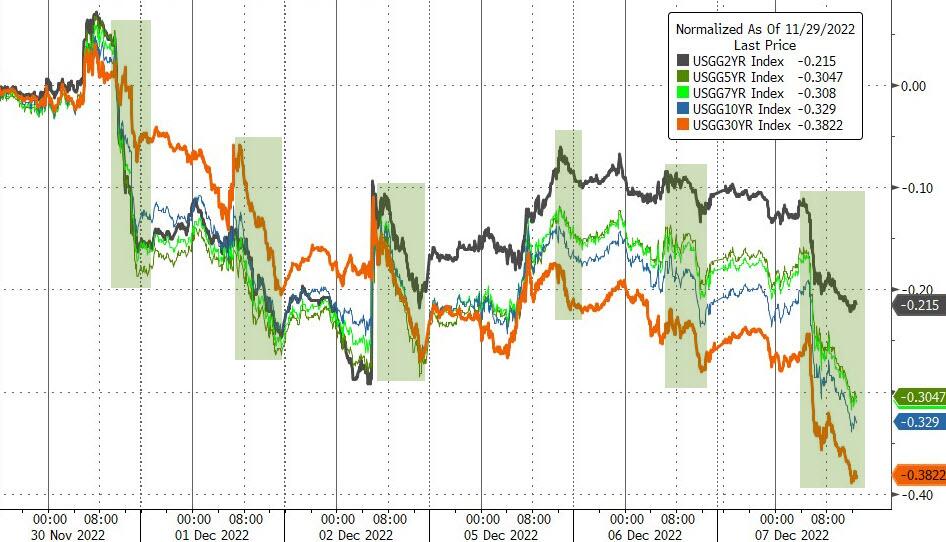
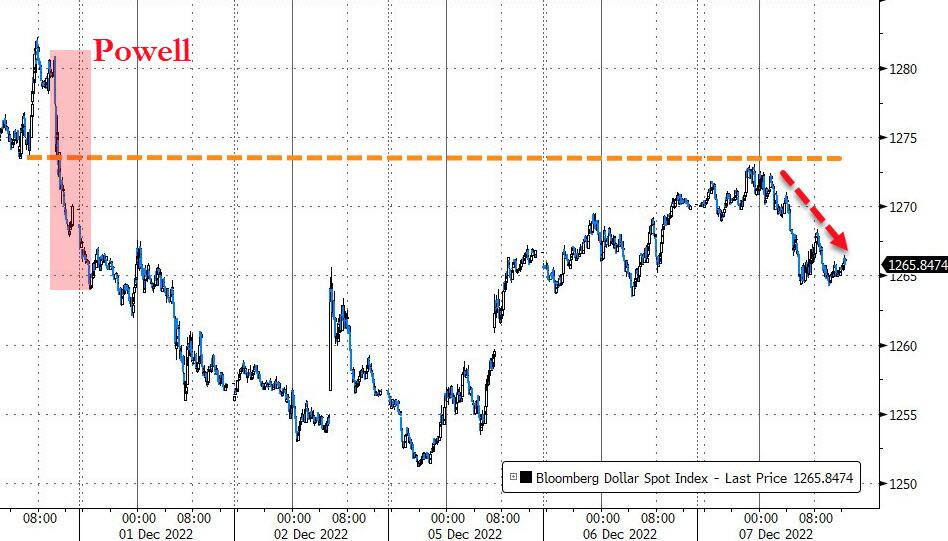
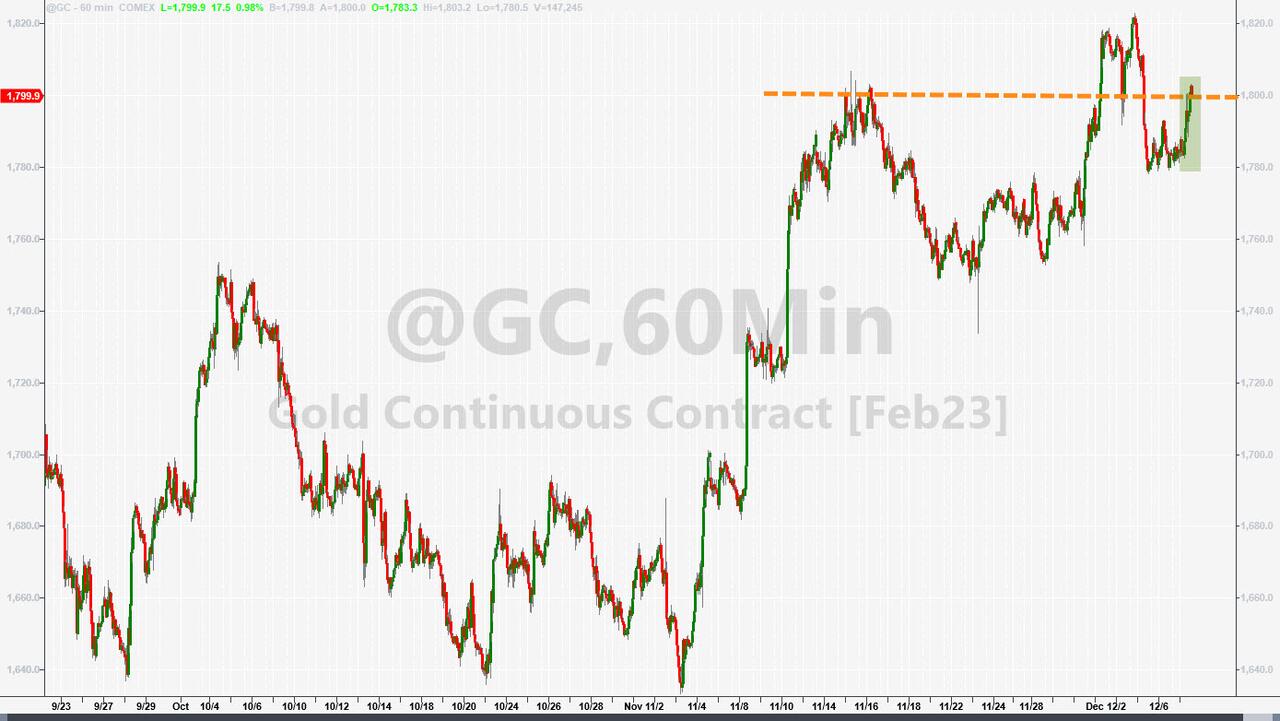
Helping the bullish theme were lower bond yields, the spanking of the US Dollar, and the everlasting hope that the Fed will become less restrictive, when they announce their interest rate changes tomorrow. Gold was the winner, with the precious metal gaining +1.70% and reclaiming its $1,800 level.
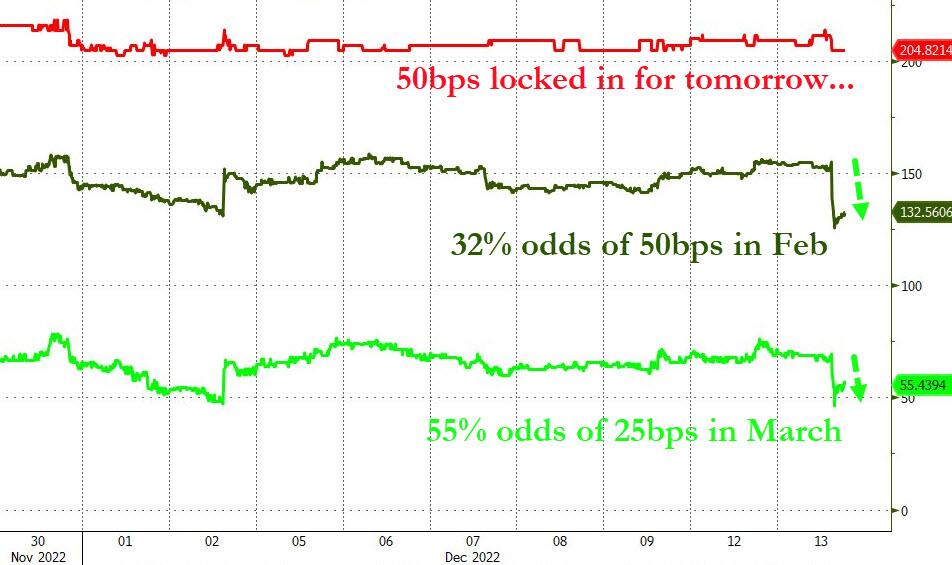
The odds for a 50bps hike tomorrow appears to be a given, but softer readings for next year are expected.
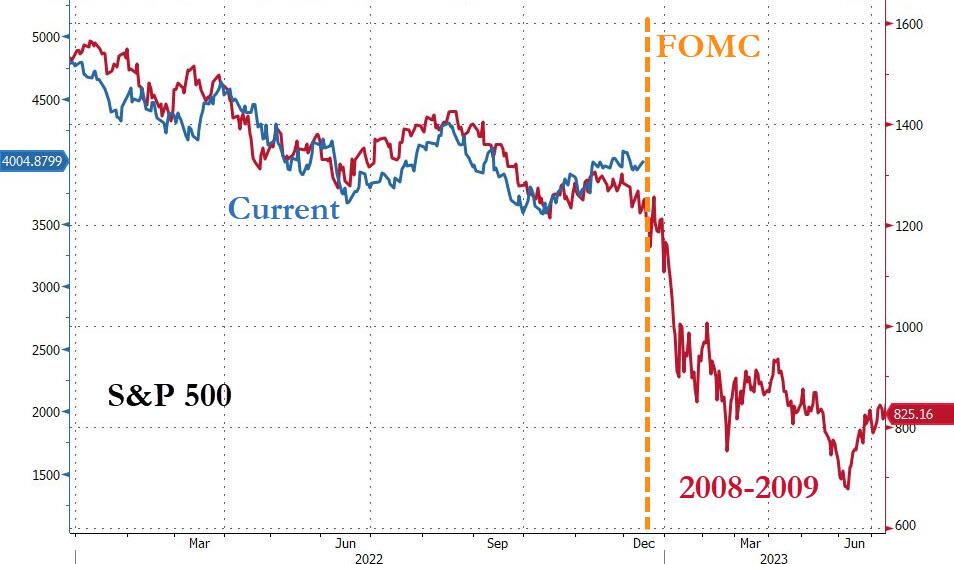
All eyes are now on Fed head Powell causing ZeroHedge to ponder: “Will he spoil the party?
Read More