
05-20-2011

Ulli Newsletter Archives Contact

Friday, May 20, 2011

A BULL IN THE HEADLIGHTS

This past week’s market activity resembled the same theme as we’ve seen lately. An early sell-off followed by a recovery attempt, and then a close within a few points of the unchanged line.

While it was a volatile ride again, the bulls appeared to be frozen and can’t seem to find their bearings thereby yielding the trading floor to the bearish crowd. However, neither bulls nor bears have been making any serious headway, which means we’re stuck in no man’s land.

While first quarter earnings were strong, recent economic data were not exactly a chest pounding event keeping the markets in neutral.

Taking center stage was the European debt crisis, which seems to be on the cusp of a major event taking place. First, new words like “re-profiling” and “soft restructuring” were introduced this week intended to put some lip stick on that pig. Of course, everybody knows that over-indebted countries such as Greece, Ireland and Portugal can’t and won’t pay back the burden the ECB has put on them.

It’s just a matter of time, before the first default takes place. Second, Fitch’s downgrade of Greek debt today pushed the Euro lower against the dollar, while gold rallied sharply with the gold ETF (GLD) adding +1.26% today. Again, gold functions not as much as a hedge against inflation but against uncertainty, of which we are seeing plenty with the euro zone debt crisis. Today’s move in gold makes me wonder what that precious metal will do in terms of rallying once an actual default occurs and how much of that bullishness will affect the dollar. The problems

are not just with the countries mentioned above. As I am writing this, I am watching a live feed from Spain with huge demonstrations, which already have spilled over into Italy.

In regards to our Trend Tracking Indexes (TTIs), the picture remains murky and divided as the domestic TTI stayed about even, while its international counterpart lost. Here are the week ending numbers as they relate to the respective long-term trend lines:

Domestic TTTI: +4.41% (last week +4.58%)
International TTI: +2.59% (last week +3.31%)

Next week, we’ll be facing economic reports about New Home Sales, Durable Orders, GDP and Personal Income, just to name a few. Throw in more unexpected news from the euro zone, and you have a recipe where anything goes.

In case there are any effects on our sell stops, I will update those via a blog post. Be sure to tune in regularly.

Have a great week.

Ulli…

————————————————————-

Back issues of the Fund Tracker are available on the web at:

http://www.successful-investment.com/newsletter-archive.php

Do you have a question regarding your mutual fund investments?

I will always give you my unbiased and honest opinion. How can you be sure?

First, this is a free newsletter and it will not affect my renewal rates.

Second, I am not running for office and do not have to hide my thoughts in evasive language designed to obscure what I really mean.

So, feel free to send your questions to: ulli@successful-investment.com

All Reader Q & A’s for this Buy Cycle are now listed at our web site! Check it out at:

http://www.successful-investment.com/q&a.php

WOULD YOU LIKE TO HAVE YOUR INVESTMENTS PROFESSIONALLY MANAGED?

Do you have the time to follow our investment plans yourself? If you are a busy professional who would like to have his portfolio managed using our methodology, please contact me directly or get more details at:

http://www.successful-investment.com/money_management.htm

We are located at:

18685 A-Main Street, #606
Huntington Beach, CA 92648

Until next week.

Ulli…

Return to Newsletter Archive

=============================
Ulli G. Niemann
Registered Investment Advisor
714.841.5804
http://www.successful-investment.com
=============================
05-13-2011

Ulli Newsletter Archives Contact

Friday, May 13, 2011

BEARISH FOOTPRINTS

Mixed economic data throughout the week kept the markets bouncing around in a trading range with no clear direction. Compared to last Friday’s close, the S&P 500 ended down 2 points.

Expectations for an expanding economy remain widespread, but a continued slowdown has become a distinct possibility, which would limit any upside growth and certainly will impact equity prices. As to when and how much remains the big unknown.

Consumer prices rose 0.4% in April, which was in line with expectations after an increase of 0.5% in March. Excluding the volatile food and energy components, the core rate gained 0.2% and 0.1% respectively.

While the consumer sentiment unexpectedly rose to 71.4 in May, from 69.8 in April, higher food and energy costs seem to put a limit on discretionary spending. Absent any improvement in prices, this too will eventually affect the direction of equities.

Looking across the Atlantic, the Eurozone GDP grew by a better than expected 0.8% in the 1st quarter of 2011. However, concerns about Greece’s unsustainable debt level occupied front page news.

More meetings are scheduled to discuss additional options for Greece. To my way of thinking, it’s now just a matter of time that the heretofore avoided term “restructuring” (translation: partial forgiveness of debt) will have to become part of the vocabulary.

Our Trend Tracking Indexes (TTIs) meandered as well, but more weakness has become apparent in the international arena as the positions relative to the long-term trend lines show:

Domestic TTTI: +4.58% (last week +4.76%)
International TTI: +3.31% (last week +4.72%)

Next week, we’ll be facing an economic calendar that includes Housing Starts, Building Permits, Industrial Production, Initial Claims, Existing Homes Sales and Leading Indicators among others. Any positives might help the major indexes break out of the current sideways pattern.

Despite this week’s bounciness in the market, no trailing sell stops were triggered. Looking at the various holdings, my guess would be that the next one on the chopping block will be energy (VDE), which will definitely head further south should any economic reports showing a slowdown materialize.

I will update any sell stop issues concerning our holdings via a blog post. Stay tuned.

Have a great week.

Ulli…

————————————————————-

Back issues of the Fund Tracker are available on the web at:

http://www.successful-investment.com/newsletter-archive.php

Do you have a question regarding your mutual fund investments?

I will always give you my unbiased and honest opinion. How can you be sure?

First, this is a free newsletter and it will not affect my renewal rates.

Second, I am not running for office and do not have to hide my thoughts in evasive language designed to obscure what I really mean.

So, feel free to send your questions to: ulli@successful-investment.com

All Reader Q & A’s for this Buy Cycle are now listed at our web site! Check it out at:

http://www.successful-investment.com/q&a.php

WOULD YOU LIKE TO HAVE YOUR INVESTMENTS PROFESSIONALLY MANAGED?

Do you have the time to follow our investment plans yourself? If you are a busy professional who would like to have his portfolio managed using our methodology, please contact me directly or get more details at:

http://www.successful-investment.com/money_management.htm

We are located at:

18685 A-Main Street, #606
Huntington Beach, CA 92648

Until next week.

Ulli…

Return to Newsletter Archive

=============================
Ulli G. Niemann
Registered Investment Advisor
714.841.5804
http://www.successful-investment.com
=============================

High Volume ETFs On The Cutline – Updated Through 6/8/2011

Ulli ETFs on the Cutline Contact

With the continued selloff, today’s High Volume ETF Cutline report offers some interesting insights in where the markets might be headed.

To clarify, High Volume (HV) ETFs are defined as those with an average daily volume of $10 million or higher.

These ETFs are generated from my selected list of 90 that I use in my advisor practice. It cuts out the “noise,” which simply means it eliminates those ETFs that I would never buy because of their volume limitations.

We had some major index ETFs showing tremendous weakness by dropping in on our cutline report from a level above the first positive 20 positions listed. That is not a good sign, if you are bullish and have no exit strategy.

Let’s start at the top:

Read More

05-06-2011

Ulli Newsletter Archives Contact

Friday, May 6, 2011

WHACKING THE BULLS

After last week’s strong rally, it was time for the bears to show some muscle and pull the major indexes back into reality territory. After 4 days of selling, euphoria about today’s better than expected jobs report pulled the market out of the doldrums via a sharp opening upside spike.

I am not sure if this was a partial dead cat bounce, but sentiment changed in a hurry on news reports that Greece may abandon the European Union and create its own currency. That took the starch out of the upward momentum and, while we ended up closing in plus territory, we came way off the highs for the day.

Yesterday’s selling pushed one our holdings, the commodities index (DBC), below its trailing sell stop by a slight margin. As is my custom, I watched the market open this morning with DBC making a nice rebound. Upward momentum faded as the session progressed, and I ended up liquidating this position before it headed further south again. None of our other holdings were affected by this past week’s market slide.

Employment growth provided the initial boost with payrolls growing by 244,000, which was far better than the consensus range of 185,000 to 200,000. However, the unemployment rate inched up from 8.9% to 9%.

Gold rebounded today, but crude oil and silver continued to slide with oil having lost 14.7% this week, while silver gave back 27.4%. Interest rates rose along with the dollar index.

Our Trend Tracking Indexes (TTIs) pulled back a little from last Friday’s close but remain in bullish territory by the following percentages:

Domestic TTTI: +4.76% (last week +5.98%)

International TTI: +4.72% (last week +7.10%)

While the better than expected unemployment report took center stage, worries persisted about Thursday’s disappointing jobless claims report, which may affect the jobs picture in May or June.

As a result, and absent any major negative events, we may see the market trade in sideways pattern until a better picture about the true economic strength, or lack thereof, emerges.

Have a great week.

Ulli…

————————————————————-


Back issues of the Fund Tracker are available on the web at:

http://www.successful-investment.com/newsletter-archive.php

Do you have a question regarding your mutual fund investments?

I will always give you my unbiased and honest opinion. How can you be sure?

First, this is a free newsletter and it will not affect my renewal rates.

Second, I am not running for office and do not have to hide my thoughts in evasive language designed to obscure what I really mean.

So, feel free to send your questions to: ulli@successful-investment.com

All Reader Q & A’s for this Buy Cycle are now listed at our web site! Check it out at:

http://www.successful-investment.com/q&a.php

WOULD YOU LIKE TO HAVE YOUR INVESTMENTS PROFESSIONALLY MANAGED?

Do you have the time to follow our investment plans yourself? If you are a busy professional who would like to have his portfolio managed using our methodology, please contact me directly or get more details at:

http://www.successful-investment.com/money_management.htm

We are located at:

18685 A-Main Street, #606

Huntington Beach, CA 92648

Until next week.

Ulli…

=============================

Ulli G. Niemann

Registered Investment Advisor

714.841.5804

http://www.successful-investment.com

=============================

6 ETF Model Portfolios You Can Use – Updated through 6/7/2011

Ulli Model ETF Portfolios Contact

The markets sold off sharply since last week’s portfolio update and, as a result, our trailing sell stop for VB was triggered Monday, and the position was liquidated yesterday. Portfolios #1 and #4 were affected by this sale.

There was a shift in YTD performance as the aggressive portfolio (#3) edged out #5 for the top spot. More importantly is the comparison of all portfolios to the benchmark index S&P 500, which took a beating and is now only up by +2.17% for the year, as opposed to the #3 portfolio, which still sports a gain of +5.48%.

This clearly demonstrates that diversification is important as it has added an element of stability during this market selloff.

To be clear, the idea is not to be invested in the top performer but a portfolio that represents ‘your’ personal risk tolerance – and not someone else’s.

Take a look at this week’s numbers:

Read More

Major Market ETFs Plunge During Last Hour

Ulli Market Commentary Contact

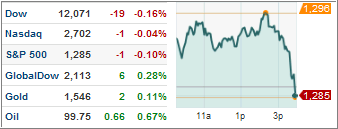
The markets did their best cliff dive imitation during the last hour of trading and surrendered all gains of what appeared to be a nice rebound.

Causing the sudden change in sentiment were comments from Fed chairman Bernanke, during which he saw the recovery as uneven and also warned against a “sudden fiscal contraction” if spending would not be brought under control.

Read More