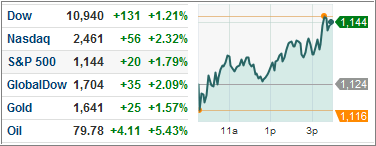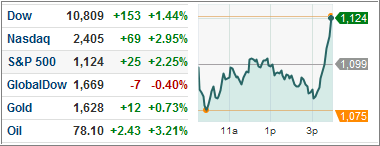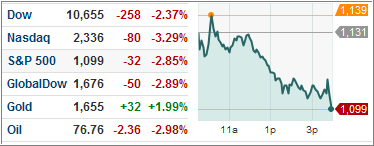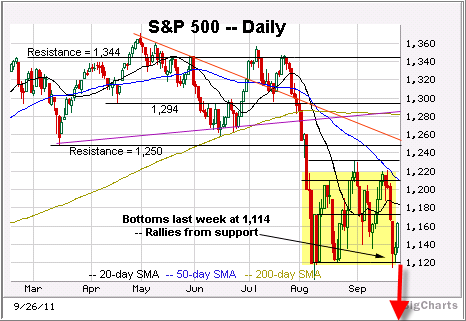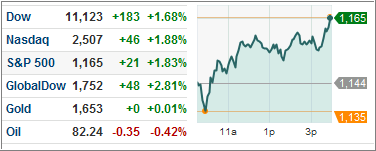
For the third consecutive trading session, markets remained in the green, giving some hope for equities. Once again, major indices and commodities rose with the S&P 500 gaining 1.83%, while the U.S. dollar slightly depreciated to $1.34/euro.
Today’s gains were possibly in part due to strong September sales figures from major U.S. retailers that exceeded expectations, suggesting a potential rebound in consumer spending to lift the economy. Furthermore, talks of European bank aid propelled markets into positive territory.
However, this short-term optimism seems premature especially ahead of Friday’s jobs numbers. Plus, Europe’s uncertain long-term plan on how to deal with mounting debt is worrisome, especially with Germany’s insistence on banks trying to fix their own balance sheets and for European investors to bear more of the burden in the case of a Greek bailout.
At this time, I see no reason to jump back into equities. The position of our Trend Tracking Indexes support that view.