Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 01/05/2012

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, January 5, 2012

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: BUY — since 10/25/2011

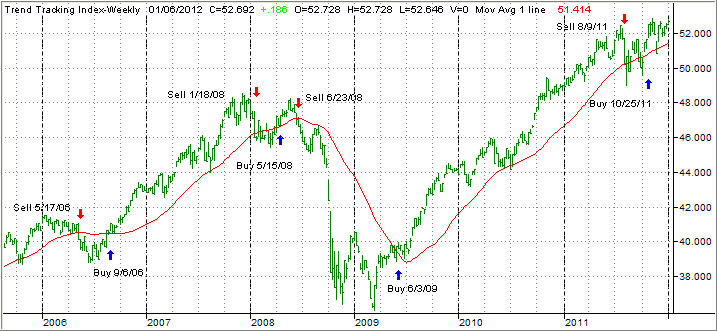
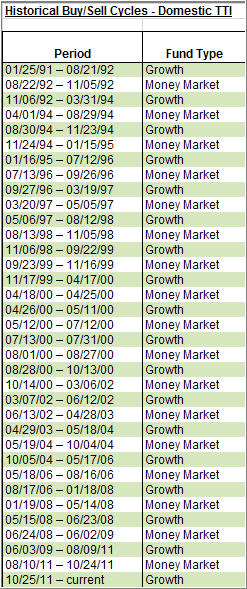
The domestic TTI broke through its long-term trend line generating a Sell for this area effective 8/9/2011. Over the recent past, we’ve seen the TTI hovering slightly below and above this dividing line between bullish and bearish territory. The clear break to the upside occurred on 10/24/11 and, effective 10/25/11, a new Buy signal for domestic equities is in effect.

As of today, our Trend Tracking Index (TTI—green line in above chart) has broken above its long term trend line (red) by +2.61%. Be sure to tune into my blog for the latest updates.

Read More

Still No Clear Direction For ETFs

Ulli Market Review Contact

[Chart courtesy of MarketWatch.com]

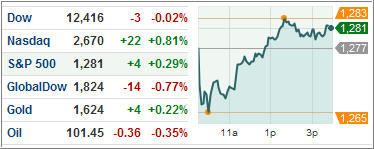
Once again, major market ETFs didn’t move much as the S&P 500 gained 0.29%. But European indices fell once more while the Euro dropped to $1.28/Euro, its lowest level in 15 months.

While markets may not be fully incorporating European uncertainty at the moment, the weak Euro clearly indicates European concern among investors.

Although the VIX is relatively low just above 20, it’s no time to regain a risk appetite and move heavily into equity ETFs with the exception of a very select few. Volatility surely hasn’t faded away.

Widening European bond spreads also show continued financial strain in the region. Italy’s 10-year yield rose above the unsustainable 7% level to 7.07% while Spain’s 10-year yield went up to 5.59%. As borrowing costs remain high, confidence has greatly eroded. One thing’s for sure – I have little confidence that Europe can find a long-term solution without significant outside intervention.

Read More

01-05-2012

Ulli Newsletter Archives Contact

The ETF/No Load Fund Tracker—Monthly Review—December 30, 2011

ETFs Don’t Know Where To Turn

As the holiday season approached, markets were relatively inactive in the last week or so. The S&P 500 gained 0.85% in December although ending flat for the year. However, there wasn’t clear direction in market movements as broad indices swung up and down with no real discernible pattern. The S&P 500 is above its 50-day Moving Average, but that can quickly change.

The underlying current determining investor sentiment continues to be Europe. The Euro dropped to an 11-month low against the dollar, hitting $1.29/Euro at one point. Also, the month of December witnessed a litany of ratings downgrade warnings due to deteriorating finances and burgeoning debt loads. Leading the pack are Italy and Spain, which still not only have higher borrowing costs approaching 7%, but can’t seem to impose enough austerity to balance their budgets, further hurting their economic prospects.

In a drawn out tragedy, Greece still can’t come to compromise with creditors over the extent of the bond haircut or agree to additional bailout conditions, putting its Eurozone survival in great jeopardy. We should err on the safe side and place a high probability on a Greek exit that could rattle markets. Thus, we have positioned ourselves by keeping a low risk portfolio.

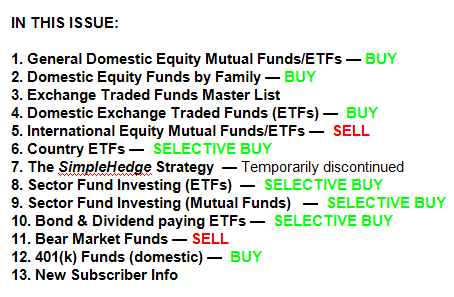
Nevertheless, we are sticking to selective buys on equity/sector ETFs with the exception of international equity ETFs and bear market funds. With the International TTI (Trend Tracking Index) finishing December at -7.65%, the international investment space is fraught with significant volatility. In this uncertain environment, we are keeping a majority bond ETF position and cash.

On home turf, the Domestic TTI finished the month above its long-term trend line at +2.33% as the chart below shows:
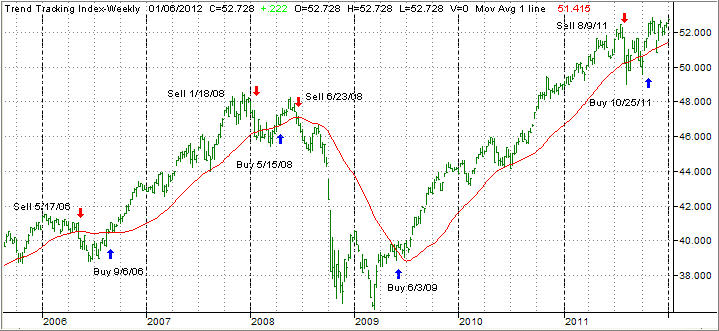
Thus, we still want to retain some minimal equity ETF exposure. Our go-to ETF for this has been Consumer Staples Select SPDR (XLP), which isn’t as susceptible to overall market volatility.

With all eyes on Europe, the uphill battle hasn’t gone away. Although the ECB instituted 3-year LTROs (Long Term Refinancing Options) to inject liquidity into a borderline insolvent banking system, this is merely a short-term solution. European banks are still hesitant to lend as they worry about counterparties fulfilling their loan obligations. In the end, the real economy has to bear the cost as funds meant to spur the economy aren’t channeled out.

Looking at the big picture, talks of a reformed EU treaty have further strained inter-European relations. Disagreements over deficit reduction conditions as well as how much autonomy countries can have over their own financial affairs has caused a rift questioning whether the Eurozone can maintain unity.

Asia’s economic condition is also deteriorating. China must come to the realization that it can’t grow its economy solely on the back of exports. Meanwhile, Japan’s strong Yen has made economic expansion via exports difficult while its domestic demand has been anemic.

In the U.S., December wasn’t a groundbreaking month other than wondering if the Fed will go ahead and enact QE3. Otherwise, investors kept flocking to Treasuries/bonds as global uncertainty remains elevated. The U.S. economic situation hasn’t truly improved, but the bleak overseas picture is enough for investors to seek refuge in U.S. government securities.

While markets slightly edged up in December, I don’t envision a breakout to the upside any time soon. Overall economic fundamentals suggest that we’re in for a long-haul with bulls and bears engaged in a continued tug-of-war.

As 2012 has kicked off, my advice is to continue adhering to a bond ETF tilted portfolio with strict stop loss protection in the event of a major market slide.

ETFs Simmer Off After a Big Day

Ulli Market Review Contact

[Chart courtesy of MarketWatch.com]

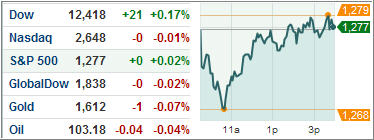
Markets started off the trading week with a roar, but calmed significantly today as the S&P 500 edged out a 0.02% uptick at the last minute. However, major European indices such as the DAX and CAC 40 had down days.

Hovering around the $1.30/Euro mark, the Euro retreated once again, falling to $1.29/Euro, a further sign of European concerns. In fixed income, the 10-year Treasury rose to a yield of 2.00%, still a very low level historically.

There is further concern about capital adequacy among European banks after Italy’s biggest bank, UniCredit, announced it would sell nearly $10 billion shares at a steep discount to raise funds. Although the ECB has taken unprecedented action as of late to ensure stability in the banking system, systemic problems remain ever present.

Read More

7 ETF Model Portfolios You Can Use – Updated through 1/3/2012

Ulli Model ETF Portfolios Contact

As I announced last week, all ETF model portfolios have been rebalanced to their original allocations effective 12/30/11. The only exception is #6, since not all of its portfolio components are positioned above their respective long term trend lines, which is a condition for this particular model.

I want to emphasize that these portfolios are only designed to assist you in your decision making process; they are not a recommendation in this current market environment. They simply allow you to compare a variety of options and observe the effects of various market conditions on my recommended sell stop discipline. If you choose to adapt your personal portfolio to any of these models, you must incorporate my often discussed exit strategy in order to minimize downside risk.

As I have posted, my particular choice at this time, is to be underinvested in equities and have more market exposure via bonds, sectors and cash holdings.

Take a look at the latest update:

Read More

Major Market ETFs Start the New Year With A Bang

Ulli Market Review Contact

[Chart courtesy of MarketWatch.com]

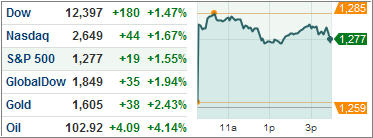
European worries seemed not to have fazed investors as 2012 has kicked off. The S&P 500 posted a gain of 1.55% while major European and Asian indices also rose. Nevertheless, the Euro didn’t move much, finishing the day at $1.31/Euro.

Also, it looks like investors perceive a slightly less risky environment as the 10-year Treasury yield went up to 1.96%. In commodities, gold and oil skyrocketed 2.42% and 4.19%, respectively. Overall, there were big movements across the market and higher trading volume after last week’s lull.

However, the Eurozone’s future doesn’t look promising. Greece has said that it might leave the euro in 3 months if it can’t agree on additional bailout. There is still no resolution regarding the bond haircut while further austerity is needed. A Greece exit, disorderly or not, would be incredibly destabilizing and have a highly adverse impact on global markets. It is the looming possibility of such an event that keeps me sticking to a low risk portfolio.

Read More