ETF/No Load Fund Tracker StatSheet
————————————————————-
THE LINK TO OUR CURRENT ETF/MUTUAL FUND STATSHEET IS:
————————————————————
Market Commentary
Friday, January 27, 2012
ETFs END THE WEEK ON AN UNCERTAIN NOTE
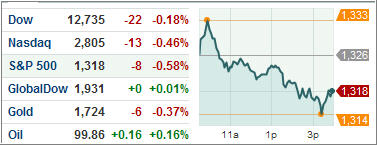
In what’s been a bit of an up and down week, the S&P 500 dropped 0.16% today. However, it’s been the 4th straight positive week for the index. With the spate of European downgrade news, European indices saw plenty of red.
Despite continued negativity in the Eurozone, the Euro once more appreciated against the dollar, hitting $1.32/Euro. Nevertheless, investors sought safety in low risk assets as the 10-year Treasury yield fell to 1.90%.
While it’s difficult to point to one indicator to gauge risk, seeing as the VIX has remained low but demand for Treasuries has been high, the outlook for Europe and the U.S. is pessimistic at the moment. To put it succinctly, we are in risk on mode for the long-term.
Today’s lackluster GDP numbers are proof that the U.S. is still a far way off from recovery. GDP growth was 2.8% in the 4th quarter, lower than expected. It is this anemic growth that supports the Fed’s decision to keep rates near zero through 2014, as credit markets have yet to serve as an effective channel to spur growth over the last few years.
Following in line with Standard and Poor’s, Fitch Ratings docked Spain and Italy down two notches. Although borrowing costs for Spain and Italy didn’t rise following the S&P downgrades, we’ll have to see if the investor outlook darkens now that two major ratings agencies have downgraded them.