Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 03/06/2014

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, March 6, 2014

Table of Content082312

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: BUY — since 10/25/2011

TTI0306

Our main directional indicator, the Domestic Trend Tracking Index (TTI), broke through its long-term trend line generating a Sell for this area effective 8/9/2011. Over the recent past, we’ve seen the TTI hovering slightly below and above this dividing line between bullish and bearish territory. The clear break to the upside occurred on 10/24/11 and, effective 10/25/11, a new Buy signal for domestic equities went into effect.

As of today, our TTI (green line in above chart) has bounced off its long term trend line (red) by +4.69%.

To avoid a potential whip-saw, a Sell signal to move out of all domestic equity positions will be generated once we have clearly pierced the line to the downside. Be sure to tune in for the latest updates.

Read More

Unemployment Claims Drop; Staples To Close 10% Of All Stores

Ulli Market Commentary Contact

Thur pic

[Chart courtesy of MarketWatch.com]

1. Moving The Markets

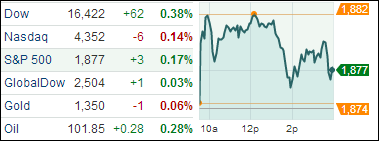
We received some good news regarding unemployment today. A report came in that showed the number of people who filed for unemployment benefits fell last week to the lowest level in three months. This report was one of the first bits of good news investors have received on the economy after weeks of data that showed the U.S. recovery temporarily slowing because of the severe winter. It has been somewhat hard to tell exactly what data has been directly related to the winter storms. This is not the case though with unemployment claims and the market responded positively today with the S&P 500 closing at a new record (again) and the Dow making notable gains.

Do you buy your ink cartridges in-person or online? Well, it seems that the answer is divided 50/50 amongst Staples customers. Staples (SPLS) made headlines today as it announced that it will close 10% of all of its stores due to the fact that now almost half of its sales are generated online. Staples is the second major brick-and-mortar retailer this week to announce widespread closures. Remember that two days ago I wrote about RadioShack announcing it would close as many as 1,100 locations as part of a restructuring effort.

Outside the U.S., investors remained concerned about Ukraine, where tensions have been escalating over Russia’s deployment of troops to Ukraine’s Crimea Peninsula. Moscow-backed Crimean officials said Thursday that the region would hold a referendum to decide whether it should be annexed by Russia. President Barack Obama declared that the referendum would violate international law. I would not be surprised to see continued volatility in the markets as this situation remains unstable.

Our 10 ETFs in the Spotlight vacillated with 6 of them making new highs while 9 of them have now moved to the plus side YTD.

Read More

Stocks Fairly Quiet Today After Big Rally Yesterday

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving The Markets

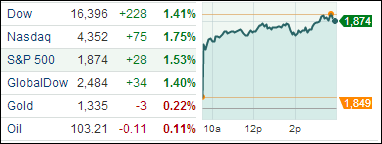
It was a pretty quiet day in the markets today with no index really moving substantially in either direction amidst some uneventful economic news. The Fed, in its Beige Book review of regional conditions, said today the economy in most sectors grew last month despite impediments from the harsh winter weather. However, the Chair of the Federal Reserve did say that the Fed still has much more to do to reach its inflation and unemployment goals.

Biotech stocks on the Nasdaq experienced some nice gains today, with many popping or dropping by more than 20% in a single day. Peregrine (PPHM) was the day’s biggest winner by far, up nearly 50% on the announcement that it would be announcing results for its preclinical immuno-oncology drugs at an upcoming conference next week. Today’s other winner, Arrowhead Research Corp. (ARWR), saw shares shoot up 25% after two Wall Street analysts switched to a “buy” recommendation in addition as they are excited about the company’s hepatitis B drug.

There was not too much exciting happening in international markets today either. U.S. Secretary of State John Kerry met with Russian diplomats today, while Russia held talks with NATO over developments in Ukraine. Key European stocks were a bit lower after strong rallies on Tuesday as the Ukraine-Russian stand-off calmed. The FTSE in London fell 0.71% while Germany’s DAX shed 0.49%. In Asia, the Hang Seng closed down 0.34% while Japan’s Nikkei was up 1.20%. Chinese authorities kept the growth target for the nation unchanged at 7.5%, despite signs of concerns around reaching it.

Our 10 ETFs in the Spotlight meandered but 3 of them made new highs while 8 of them moved to the plus side YTD.

Read More

03-05-2014

Ulli Newsletter Archives Contact

The ETF/No Load Fund Tracker

Monthly Review—February 28, 2014

US Equities Rebound In February; Europe Rallies To A Seven-Month High

US stocks made a strong comeback in February after starting 2014 on a dismal note with all the major indexes recouping January’s losses and the S&P 500 logging its 48th record monthly close in the past 52.

The blue-chip Dow Jones Industrial Average finished up 4 percent for February. That was the largest monthly percentage gain since January 2013.

The benchmark S&P 500 closed at 1,859, capping its monthly gain at 4.3 percent.

The NASDAQ Composite index ended at 4,308, up five percent for the month. The tech-heavy index notched up its biggest monthly gain since September 2013.

A batch of better-than-expected economic reports lifted US stock markets higher. The final reading of the consumer sentiment index for February was revised upwards to 81.6 from an initial estimate of 81.2, indicating improving confidence.

New home sales jumped 9.6 percent in January to a seasonally-adjusted 468,000 annual pace, the most since July 2008, data released by the Commerce Department showed. Separately, data released by the National Association of Realtors showed pending home sales rose 0.1 percent to 95 in January. The gauge slumped to 94.9 in December, the lowest since November 2011, as poor weather, low inventory and declining affordability hit sales. A reading of 100 is equivalent to the average contract activity seen in 2001.

The Chicago PMI for February rose to 59.8 from 59.6, beating analysts’ estimate of a decline to 56.0.

Economic-data firm Markit’s US flash purchasing managers’ index surged to 56.7 in February from 53.7 in the previous month as production rebounded, indicating increasing traction in manufacturing.

On the downside, the government cut its earlier estimate of US growth in the final months of 2013 as consumers apparently didn’t quite spend as much as originally reported. Fourth quarter gross domestic product grew at a 2.4 percent annual rate instead of the previously reported 3.2 percent.

Markit’s initial reading on services sector for February dropped to 52.7 from January’s final reading of 56.7.

The Philadelphia Fed’s manufacturing index slipped to minus 6.3 in February from 9.4 in January.

Across the Atlantic, European stocks rallied with the Stoxx Europe 600 index notching up a 4.8 percent gain for February. That was best performance by the benchmark index since July.

In terms of growth, Germany continued to race ahead of the pack. Gross domestic product expanded by 0.4 percent in the final quarter of last year.

Unemployment rate across the 18-member currency zone remained unchanged in January at 12 percent, the EU’s statistics office Eurostat said in Brussels.

Inflation in the euro region came in at a 0.8 percent annual pace in January, slightly exceeding an earlier estimate of 0.7 percent. That eased pressure on European Central Bank President Mario Draghi to loosen policies further to stave off deflation.

In last month’s issue, I pointed to the weakness in equities and the possibility of a return to bear market territory. However, with the strong rebound during February, that did not come to pass, and we recovered all of January’s losses.

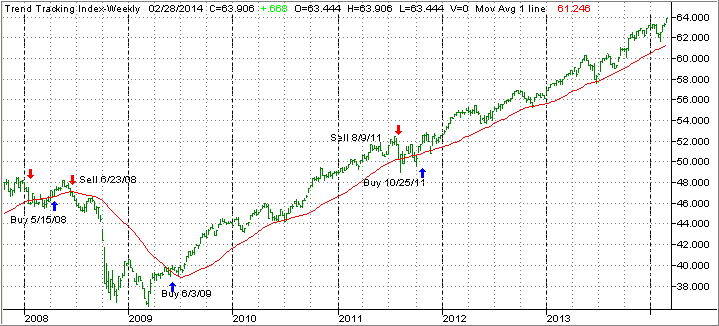
As our Domestic Trend Tracking Index (TTI) below clearly shows, the pullback in January was followed by a V-type recovery in February with the S&P 500 breaking into record territory:
TTI0228

The index itself (green line) now hovers above the trend line (red) by +4.34% (last month +1.15%).

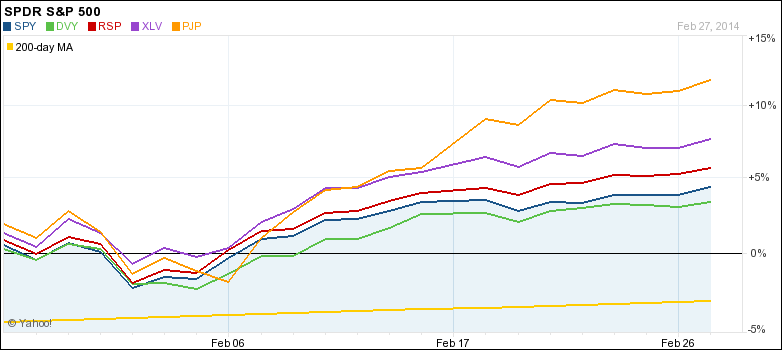
Since we were stopped out of Consumer staples (XLP) and Consumer discretionary (XLY), I replaced these empty spots with more Healthcare (XLV) and some Pharmaceuticals (PJP), while increasing our holdings in the S&P 500 index. That put us on track in joining the upward momentum of the markets to new highs.

Looking back over the past month, here is how our main holdings have fared during this rebound, which started in the second week of February:
MonthlyWrapChart

As you can see, Healthcare and Pharmaceuticals especially have been on a tear continuing where they left off in 2013. While January’s market weakness is now in the rearview mirror, we need to remain alert and not fall into complacency by being ready to adjust our portfolios should market conditions change.

Looking at the the big picture, our above Trend Tracking Index (TTI) will alert us to major changes in market direction, while on a day-to-day basis our trailing sell stops will be the guide to determine the level of our equity exposure.
Stocks Make A Comeback; Radioshack To Close More Stores

Ulli Market Commentary Contact

Tue pic

[Chart courtesy of MarketWatch.com]

1. Moving The Markets

Stocks returned with a bang today and once again we saw the S&P 500 close out the day at a new record high. Yesterday, the Ukraine conflict had investors biting their nails, but as tensions eased today (with Putin saying he would only use force as a last resort) those same investors were all smiles again.

Walt Disney Co (DIS) shares rose 2.8% to a record high of $81.71 intraday after reaching a deal with Dish Network (DISH) that lets the No. 2 satellite TV provider carry Disney-owned networks such as ABC and ESPN, and deliver the content outside of a traditional TV subscription. RadioShack (RSH), a name too often associated with ‘outdated’ announced that it will close up another 1,100 stores across the country after undergoing a massive drop in holiday sales.

As stocks rebounded today, gold fell, of course, as well as treasury prices and the Yen. Oil prices also retreated as Putin’s gesture reduced the chances that energy supply from Russia, the No. 2 world oil exporter, could be disrupted or subject to sanctions. While the markets may have corrected upwards today, do remember that they have been very volatile and reactionary in the short term this year. On the bright side though, they keep trending upwards, which is confirmed by our Trend Tracking Indexes (TTIs).

Our 10 ETFs in the Spotlight joined the rally with 7 of them making new highs and 9 of them moving on the plus side YTD.

Read More

Ukraine In Turmoil, But U.S. Economy Still Looking Good

Ulli Market Commentary Contact

Mon pic

[Chart courtesy of MarketWatch.com]

1. Moving The Markets

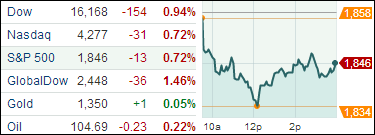
The crisis in Ukraine seems to have investors a bit jittery as the major indexes gave back some of last week’s gains. As escalating military tensions in Ukraine dominated news today, the better-than-expected economic reports we received did little to soften selling across the markets. The Ukraine worries brought about a market sentiment that we haven’t really seen since emerging market worries of Turkey and China more than a month ago.

In economic news, consumers spent more in January, but apparently a good portion of money spent was on utility bills because of the unusually cold winter. We also heard today that the final reading of Markit’s U.S. purchasing managers index accelerated in February and that this final reading for February was the highest level in almost four years. The report basically shows that output and new business picked up sharply. Also, U.S. manufacturers expanded at a faster pace in February and business would have been even better if not for severe winter weather, according to a survey of executives.

Of course, there was a small flight to gold today because of the Ukraine news. Gold futures surged by more than 2% on Monday, lifting prices to their highest level since late October. Gold closed last week in the red as a rise in U.S. consumer sentiment and strength in Chicago’s business barometer helped boost demand for U.S. equities.

Our 10 ETFs in the Spotlight slipped but 6 of them have now turned positive for the year.

Read More