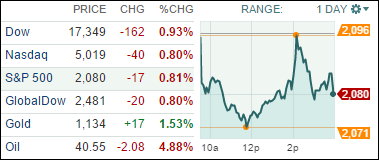
1. Moving the Markets
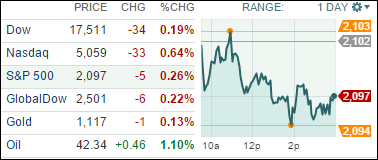
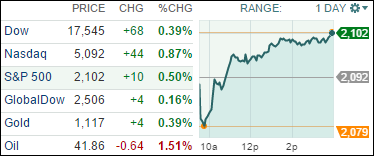
The ticking sounds of the countdown clock to the Fed’s interest rate hike are getting louder it seems. The stock market closed lower today after minutes from the Fed’s last policy meeting showed the central bank was “approaching” its first rate hike in nearly a decade. Rates near 0% and cheap borrowing costs have helped the real estate sector and greater economy heal over the past decade.
However, much of the policy speculation has depended on improvement in the labor markets and inflation moving back to its 2% mandate. The labor market has improved, but inflation remains tame. Consumer price level in July, for example, grew only 0.01%, which was below its forecast. Then there are stumbling oil prices and the devaluation of the Renminbi…
Oil prices have continued to slide, which is deflationary for the USD and China devaluing its currency sent yellow flags up about the state of the world’s second largest economy.
Let’s keep one eye on the domestic housing market indexes as we move towards the end of the week, as well as what the reactions will be on the Fed and China policy over the next couple of trading days. If it any more slippage occurs, we may very well enter bear market territory and exit our equity positions. Please see section 3 below for the current status.
All of our 10 ETFs in the Spotlight headed south today as bearish forces were too strong to overcome. Still, Consumer Discretionaries (XLY) held up the best by surrendering only -0.18%, while the Mid-Cap Value (IWS) fared the worst by giving back -0.93%.