1. Moving the Markets
The Fed announced today that it is too soon to raise interest rates and that it will continue to keep its benchmark interest rate between 0% to 0.25%, despite a continuously improving labor market. The Fed could still raise rates when they meet again in October, but analysts speculate that if a hike were to happen it would likely be in December or Q1 of 2016.
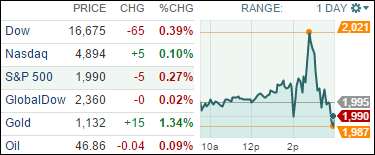
How did today’s decision impact the stock market? Well, it is somewhat hard to tell. Markets have been performing consistently well this week ahead of the decision, however, today both the S&P 500 and Dow dropped slightly, while the Nasdaq gained. Obviously, the lack of clarity on interest rates will send markets back into the “will they or won’t they” mode that has produced much of the volatility we’ve observed throughout 2015.
Crude closed down 25 cents at $46.90 a barrel after surging 5.7% yesterday. The good news for consumers perhaps is that, according to OPEC sources, OPEC forecasts oil prices will allegedly grow by no more than $5 per barrel a year to reach $80 by 2020.
Our 10 ETFs in the Spotlight ended up mixed today with 5 of them gaining and 5 of them losing. On the winning side, Healthcare (XLV) took top billing with +0.91%, while the loser of the day turned out to be the Financials (IYF) with -1.04%.