1. Moving the Markets
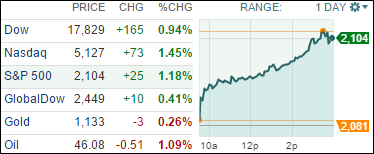
U.S. stocks kicked off November with nice rally as investors reacted to a batch of corporate deals, fresh economic data and anticipate another big week of corporate earnings. For first time since Aug. 18 the S&P 500 closed above 2100. The index is now at 2104.05 nearing its all-time closing high of 2130.82.
In earnings news, shares of Mexican chain Chipotle Mexican Grill (CMG) ended down 2.5% after the company closed some restaurants out West in response to reports of suspected E-coli infection traced to its restaurants in Washington and Oregon.
After watching our Domestic Trend Tracking Index (TTI) hover slightly above its long-term trend line for 6 consecutive days, today’s breakout confirms the newly developed trend, which makes a new Buy signal for “broadly diversified domestic equity funds/ETFs” effective as of tomorrow. As the rally gained steam, I took the opportunity early this morning to add to some of our sector positions, which I established last week. For more details, please see section 3 below.
Equities were mixed around the globe. Shares in China and Hong Kong were dragged down by the weak manufacturing data out of mainland China, with its so-called PMI coming in line with forecasts at 49.8, which signals a contraction.
All of our 10 ETFs in the Spotlight joined the rally and closed higher led by Healthcare (XLV) with +2.04%, while Consumer Discretionaries (XLY) lagged with +0.46%.