1. Moving the Markets
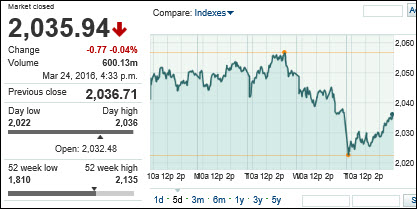
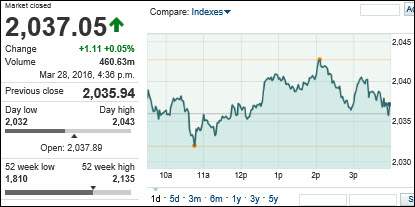
The major indexes closed moderately higher after a day with little volatility. Perhaps the hesitance in markets today was the fact that investors are waiting to react to more economic news this week that will provide further insight into the state of the slumping domestic economy.
Today, we received reports on personal income, consumer spending and pending home sales. Personal income data showed a slight 0.2% gain. Consumer spending was in line with expectations and pending home sales rose 3.5%, which topped expectations and signaled that the real estate recovery continues.
On Tuesday, we’ll hear March’s consumer confidence survey, but the big data point comes in on Friday when the government will issue its March jobs report. If the report comes in strong, it could signal a sooner than expected rate hike in April.
In M&A news today, General Motors (GM) received a solid regulatory approval to acquire Cruise Automation, a 3 year old startup company that has developed an autopilot system that GM is drooling over. Cruise has a device that will enable drivers to give complete control of the accelerator, brakes and steering to the car. The purchase price of the company was not reported, but rumors allege that GM paid around $1 billion.
 While recent GDP readings have showed inconsistency repeatedly, investors should not ignore GDP readings totally, said IHS chief economist Nariman Behravesh.
 Institutional investors have been selling or writing put options for many years to boost income when markets are placid and trend sideways.