Back To “Normal”

Ulli Uncategorized Contact


After the modest sell-off last week, M&A; was yesterday’s buzzword, and the markets rallied higher in “normal” fashion. These days, that can be interpreted that a slight pullback is always followed by a rally sufficient to make up the small losses; that is until it no longer works and the trend ends.

Some readers have commented that they exited the market as weakness surfaced last week. Again, my mode of operation is not to make emotional decisions but let the market tell me when it’s time to get out.

There is no harm in taking profits early, and your comfort level should determine if you have reached this point. There is no sense in following any strategy if you don’t have the stomach for it.

As a point of reference, last week’s drop pulled some of our holdings only 2.5% off their highs. In other words, more downside action is needed before our trailing sell stops kick in.

We’ll sit tight and let the stops be our guide as to when to exit knowing that a trend reversal appears to be likely at that time.

Tips For TIPS

Ulli Uncategorized Contact

The WSJ reports that “Investors Seek Inflation Haven in TIPS Funds.” Here are some highlights:

Rising fears of inflation are fueling an investor rush into mutual funds and exchange-traded funds holding Treasury inflation-protected securities.

So far this year, more than $17 billion has poured into funds that invest in TIPS, government-issued bonds whose principal grows with rising inflation, according to estimates from research firm Morningstar Inc. That compares with estimated net cash inflows of almost $10 billion for 2008.

Their popularity reflects worries that massive U.S. government spending will eventually lead to high inflation, which could erode the value of stocks and ordinary bonds. But if inflation stays at current low levels longer than some investors expect, TIPS may not add much juice to a portfolio—and could even drop in value.

Sure, common sense dictates current government policies will lead to inflation–eventually. However, as I have pointed out before, all industrialized nations more or less are following the same inflationary policies, which makes me wonder what the ultimate effects will be. In the past, only isolated countries have inflated their currencies with the effect that they lost in value relative to all others.

This time around, everyone is trying to inflate to get out from under the deflationary forces. I think we are in unchartered territory with the outcome being a total unknown.

That said, many investors aren’t in it for the yields, but for the protection they hope the bonds will provide if inflation suddenly surges. For now, TIPS buyers are brushing aside the prospect that the bonds won’t do well if that much-feared inflation doesn’t materialize. Indeed, many TIPS have been bid up to prices exceeding their face value.
….
But inflation alone doesn’t determine how well TIPS perform. Supply and demand also play a role. And demand for TIPS is driven by inflation expectations, rather than actual inflation. Such expectations could drive TIPS prices higher, thereby shrinking yields, since price and yield move inversely.

“There has been a ton of money flowing into TIPS year to date, yet there’s no inflation,” says Lawrence Glazer, managing partner at Mayflower Advisors in Boston.

Instead, money keeps pouring into the investments based on the expectation that inflation is ahead.

If the break-even rate widens, that would imply investors foresee higher inflation. But once the Federal Reserve begins to address inflation, it will raise short-term interest rates, and that would push down the value of existing bonds.

In that case, there would be two counterforces acting on TIPS: rising inflation or expectations of inflation pushing up demand and thereby pushing up prices; and rising short-term rates driving down prices. If the Fed pushes rates up faster than inflation rises or raises rates before inflation picks up, TIPS could rack up losses for their owners. They could also decline if inflation turns out milder than investors’ original expectations.

I agree that supply and demand plays a major role. In fact, it may have been that imbalance of more investors “expecting” inflation that has caused TIP to break out above its long-term trend line. Take a look at a 2-year chart:
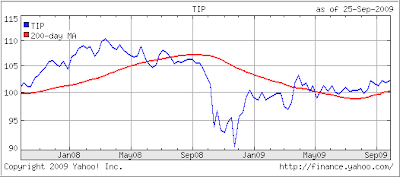


If this inflation expectation is not met, we could very well see a drop below the trend line again. If you own TIP in your portfolio, be sure to use the trailing sell stop discipline here as well; just in case the future does not turn out the way many investors expect.

Disclosure: My clients currently have holdings in the ETF discussed above.

Sunday Musings: Whose Money Is It Anyway?

Ulli Uncategorized Contact

At first, I couldn’t believe it. But as more calls and emails came in over the past few months, a pattern seemed to emerge. Apparently, there really was some truth to it.

What am I talking about? I am referring to many investors’ disenchantment (too nice a word, really) with their brokers who kept them in the market during last year’s meltdown.

Phrases like “XYZ Company lost me so much money” are common. Anger still seems to run high and upon my question “why did you not tell your broker to sell” I have been getting this most stunning answer “they refused to sell my positions.”

What?

These are not isolated comments but have come from dozens of readers and new clients, who had conversations with their advisors/brokers during various times of the 2008 crash and reported that they were refused to have their holdings liquidated.

To me, that’s an absolute shocker and underscores the total arrogance so pervasive in the financial services industry along with total disregard for a client’s wishes. That begs the question “whose money is it anyway?”

It seems to be a conveniently forgotten fact that the client owns the money and as advisors we’re here to serve him and act in his best interest. If a client wishes to temporarily go with his gut and against the convoluted asset allocation scheme, because he can’t stand losing any more money, should we not oblige?

Of course we should; a client’s comfort level with whatever an advisor/broker does should be priority one, and not adherence to an outdated model that does not take into consideration any bear market scenarios.

Having had this discussion with a new client, I was informed that he had to sign a statement when using Fidelity’s management services that would not allow him to place any trades himself. In other words, he was stuck with the advisor’s allocation plan until the agreement was cancelled.

I find this unacceptable. If you are the owner of an investment account, you should always have the right to supersede the advisor’s authority and be able to place trades. If you have a good relationship with your advisor, and are in agreement with his approach, there is not need to use that right, but you should always have it. At least that’s how it’s done in my advisor practice.

Lack of respect for a client’s wishes seems to be a common denominator in the financial services industry, especially when large commissions are at stake. While earning commissions is an honorable way to make a living in most industries, it has failed miserably in the financial arena. The prevailing thought with many (not all) commissioned brokers is how to generate sales at all costs, and not what might be in the best interest of a client.

The old adage that “(commissioned) brokers are like pigs at a trough; the pigs may change, but the food is always the same” still holds true today.

Sell Stops For Ultra ETFs

Ulli Uncategorized Contact

For most of the past week, I have discussed sells stops and responded to various reader questions. Here’s David’s comment:

I enjoy reading your blog and have three ETF questions for you.

I got totally out of the market before it hit bottom. As the market began to recover I began reinvesting a set amount each month in three ultra ETFs: QLD, UWM and UYD. Needless to say the results have been spectacular so far. My questions are:

1. Since these funds are twice as volatile as the indexes they track, should my stops be 7% or 14%? (At this point I would make over 35% on all three at 14%).

2. Since I invested in several lots should I sell all at my stop point or have several different stops, perhaps tied somehow to the price of each lot and number of shares?

3. If your answer to question 2 is sell all and I get whip-sawed, should I get back in incrementally when a new high is reached or reinvest the entire amount from the stop sale and then get back on my monthly investment program?

I do not use Ultra ETFs personally or in my advisor practice. The reason is the added volatility, which makes it more difficult to apply the concept of trend tracking along with trailing sell stops. However, since you asked, here’s my response to your questions:

1. You have a nice profit built up and are obviously aware that it can evaporate in a hurry if the market turns. A common belief says that the higher your unrealized gains, the further back you can trail your stop loss points. That may apply to some but not to others. Your risk tolerance definitely comes into play here. If you’re comfortable giving up 14%, then that’s what you should do. If not, use 7%; you only can make that decision.

2. Since all of your positions have rallied, there is only one high price from which to measure the drawdown to your eventual sell point. When a sell stop gets triggered, I liquidate all holdings of that ETF.

3. Since you are using leveraged ETFs, I personally would use the incremental buying process and ease back into the market in 1/3 increments or whatever percentage you are comfortable with.

You have experienced how leverage can work in your favor. Do not become complacent thinking it will always work this way, because it won’t. Nevertheless, you took advantage by using the tools available to maximize your returns during this bullish rebound. Congratulations!

No Load Fund/ETF Tracker updated through 9/24/2009

Ulli Uncategorized Contact

My latest No Load Fund/ETF Tracker has been posted at:

http://www.successful-investment.com/newsletter-archive.php

Sloppy and choppy was this week’s theme as the major indexes lost around 2%.

Our Trend Tracking Index (TTI) for domestic funds/ETFs has now crossed its trend line (red) to the upside by +7.74% keeping the current buy signal intact. The effective date was June 3, 2009.


The international index has now broken above its long-term trend line by +14.69%. A Buy signal was triggered effective May 11, 2009. We are holding our positions subject to a trailing stop loss.


[Click on charts to enlarge]

For more details, and the latest market commentary, as well as the updated No load Fund/ETF StatSheet, please see the above link.

Against The Wind

Ulli Uncategorized Contact

Yesterday turned into one of those classic “buy the rumor, sell the fact” situations as the Fed’s unchanged stance on interest rates failed to inspire the buyers.

Actually, the bears took over, and the major indexes headed straight south, although the losses were moderate given the size of the rally since the March 09 lows.

The initial reaction after the Fed announcement was positive, as the chart shows, but disappointment over lack of bullishness in the language disappointed traders and off the highs we went.

Our Trend Tracking Indexes (TTIs) retreated slightly but remain firmly in bullish territory:

Domestic TTI: +8.30%
International TTI: +16.82%
Hedge TTI: +3.32%

We will now have to see if the pattern of the past few months repeats itself, meaning that the moment the indexes give back about 1%, buying sets in, and we’re on our way to higher highs.

Sooner or later this trend will come to an end and reverse. Be prepared by having your trailing sell stops in place so that you can exit at a moments notice, should market behavior dictate such action.