Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 10/27/2011

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, October 27, 2011

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: BUY — since 10/25/2011

The domestic TTI broke through its long-term trend line generating a Sell for this area effective 8/9/2011. Over the recent past, we’ve seen the TTI hovering slightly below and above this dividing line between bullish and bearish territory. The clear break to the upside occurred on 10/24/11 and, effective 10/25/11, a new Buy signal for domestic equities is in effect.

As of today, our Trend Tracking Index (TTI—green line in above chart) has broken back above its long term trend line (red) by +3.31%.
Read More

Equity ETFs Surge, But Don’t Get Too Excited

Ulli Market Review Contact

[Chart courtesy of MarketWatch.com]

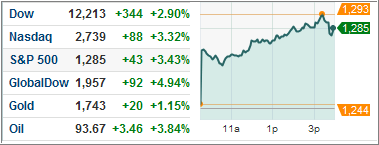
With the perception that Europe has perhaps now avoided disaster, markets responded with jubilation. The S&P 500 rose 3.43% while other indices such as the FTSE, Nikkei, and Shanghai Composite also rose.

Meanwhile, oil got a 4.00% pop while the 10-year Treasury climbed up to 2.40%, its highest yield since early August. Also, the dollar depreciated almost 3 cents against the Euro, falling to $1.42/Euro. And most noteworthy, the VIX dropped a staggering 14.57% to 25.51.

So, you might ask, are we back into risk off mode where we can regain our equities appetite? I wouldn’t fully say yes, but an entry point for some equity exposure is certainly becoming clearer, as confirmed by our recent domestic Buy signal. Additionally, the S&P 500 is now well above its 50-day MA and has now crossed above its 200-day MA as of today.

Read More

The Pendulum Swings Up Again for Equity ETFs

Ulli Market Review Contact

[Chart courtesy of MarketWatch.com]

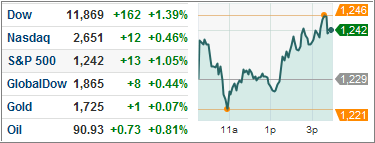
Markets returned to positive territory as Europe appeared to make some progress at its financial summit, sending the S&P up 1.05%, although nothing is set in stone yet regarding a solution.

In commodities, oil took a backseat after two big days, falling 2.47%. Furthermore, the dollar remained at $1.39/Euro. The VIX also dropped 7.32% to fall below 30. As market volatility wavers significantly, I’m still skeptical about an entry point for equity exposure until there’s a more affirmative European game plan.

A sign that the EFSF funding situation has gotten more desperate than seemingly indicated, Sarkozy is planning to ask the Chinese premier for financial aid despite previous statements from China that it wants no part in the debt crisis. The Europeans are still seeking outside assistance given expanded powers of the EFSF that now expand to buying sovereign bonds. And that’s not the only issue at hand.

Read More

7 ETF Model Portfolios You Can Use – Updated through 10/25/2011

Ulli Model ETF Portfolios Contact

The markets stayed fairly even since last week’s ETF Model Portfolio report as measured by the S&P 500. Yesterday’s pullback was a result of mixed earnings and the never ending European debt saga, which helped bond ETFs. That affected the conservative portfolio (#2) the most due to its 40% exposure in that asset class.

Other than that, the changes were minor due to our high cash exposure.

Take a look at this week’s numbers:

Read More

ETFs Caught in a Firefight Between U.S. and Europe Problems

Ulli Market Review Contact

[Chart courtesy of MarketWatch.com]

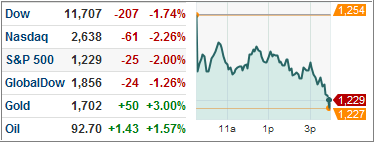
After yesterday’s gains, markets took a step back today as the S&P 500 dropped 2.00% in the wake of weak U.S. corporate earnings and nervous anticipation ahead of tomorrow’s European summit meeting. In commodities, oil and gold rose 1.73% and 2.99%, respectively. The dollar remained relatively flat against the Euro, sticking to $1.39/Euro, while volatility took a big leap today, spiking 10.12%.

Anemic earnings today suggest mixed economic signals, making it difficult to determine where the U.S. economy is heading. Barring the Netflix debacle, large firms such as 3M and Amazon came in below estimates, with the latter dropping 15%.

Meanwhile, economic indicators appear to indicate we are in a trough. For instance, consumer confidence is now at a 2-year low while the August S&P/Case-Schiller index figure indicated that for 20 major cities, property values fell 3.8% from one year earlier. The continued beleaguered state of the housing market still doesn’t look sit well for the economy with the prospect of more homes heading underwater. If you think the U.S. is bad though, take a look at Europe.

Read More

Equity ETFs Seem To Be Ignoring Europe – Domestic Buy Signal Generated

Ulli Market Review Contact

[Chart courtesy of MarketWatch.com]

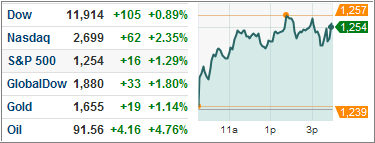
Political deadlock in the wake of yesterday’s Eurozone meetings that failed to produce a definitive plan on how to deal with the continent’s mounting debt didn’t seem to faze markets in today’s trading session as the S&P 500 rose 1.29%. On the international front, the Nikkei, Shanghai Composite, FTSE, and DAX also posted gains.

In relation to earnings, Caterpillar’s above consensus performance provided some hope for the U.S. economy with regards to manufacturing, helping markets see some green. Also, there was a boost in M&A activity that was promising. Yet, the big story is still Europe.

While it appears that markets aren’t heavily taking European uncertainty into account right now, there’s no denying that Europe’s house is not in order. Member nations and Greek debt holders still can’t decide on the size of the haircut although 60% has been suggested as a minimum to help Greece stave off default given that it will need $350 billion in aid through the end of the decade. But it gets worse than that.

Read More