[Chart courtesy of MarketWatch.com]
- Moving the market
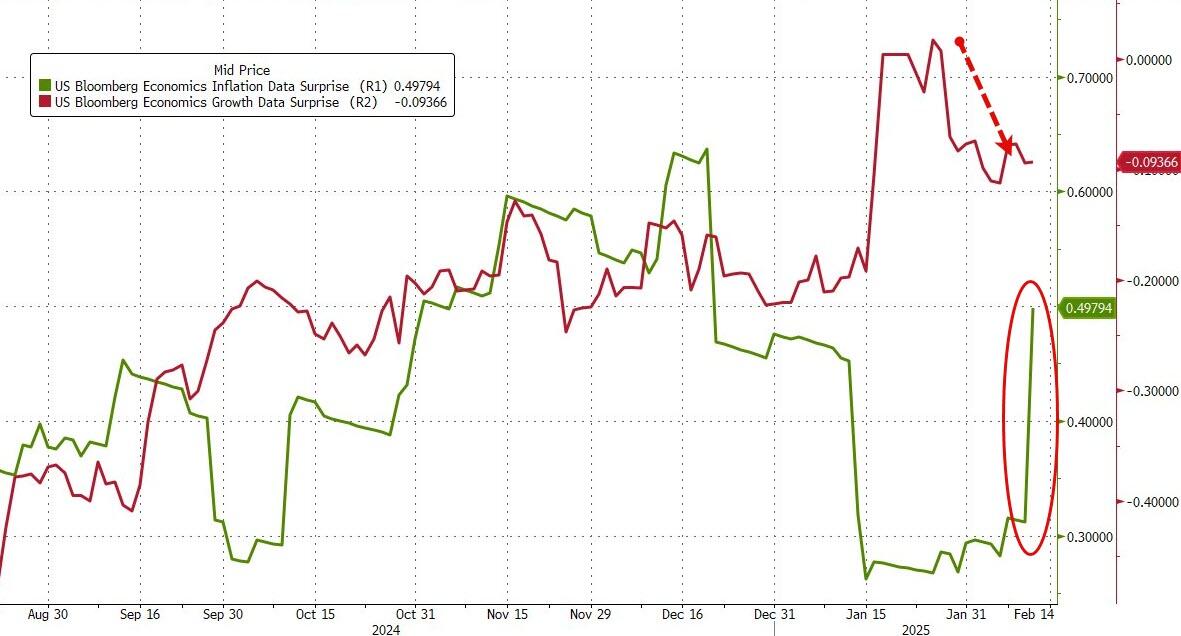
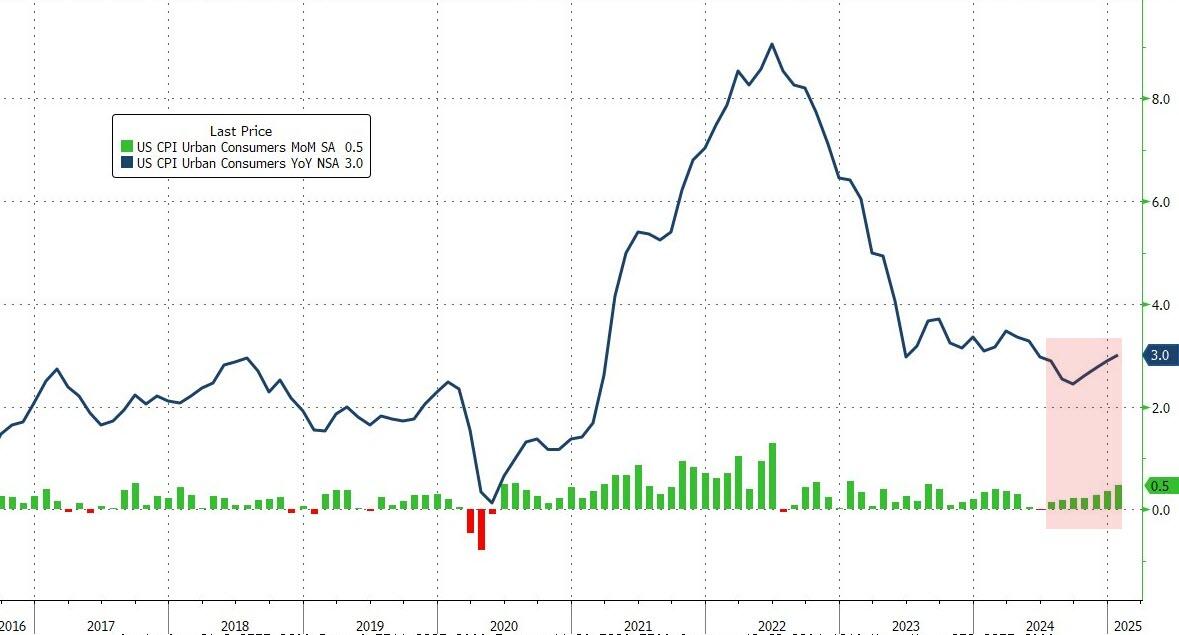
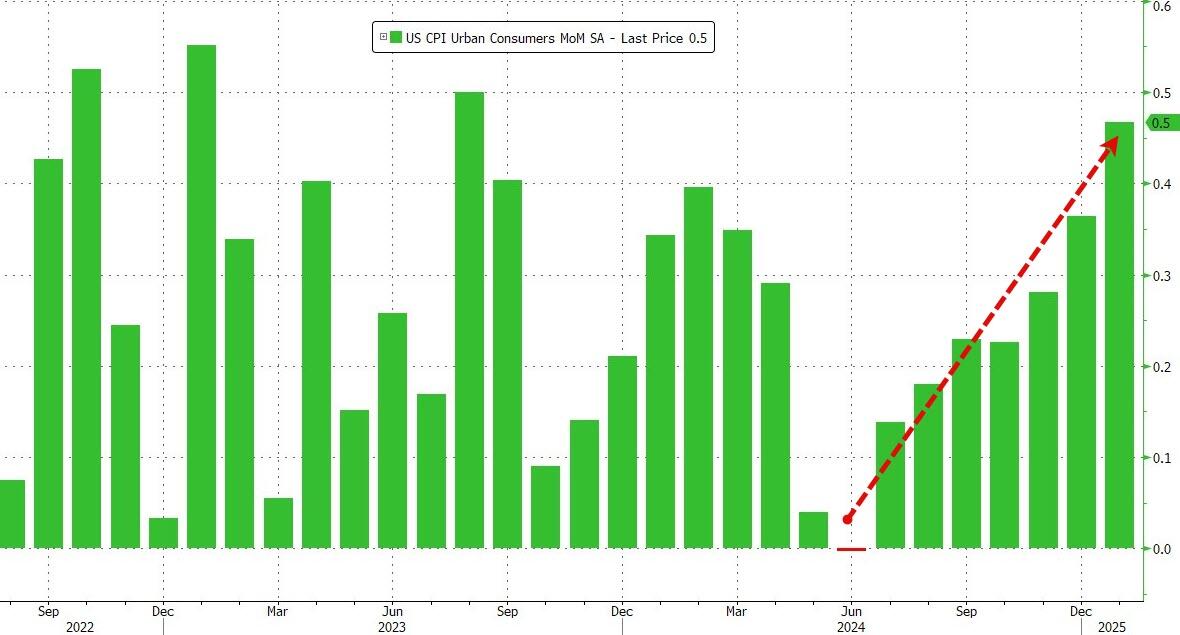
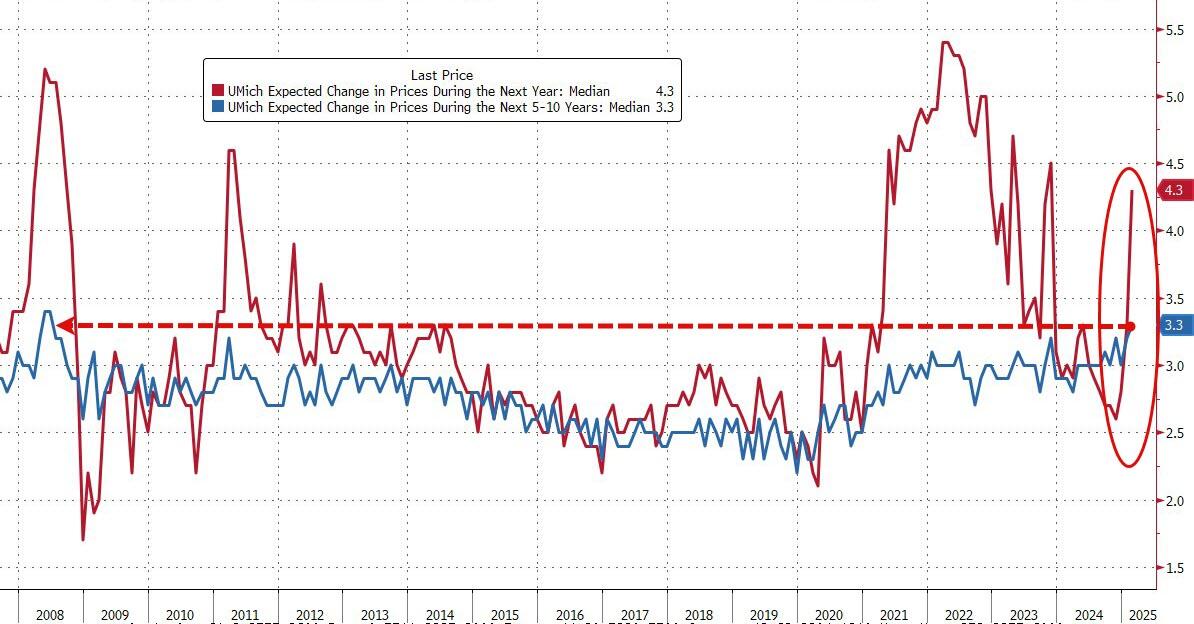
Following yesterday’s hotter-than-expected Consumer Price Index (CPI) report, today’s Producer Price Index (PPI) numbers also exceeded expectations. The January PPI showed a 0.4% increase, surpassing the consensus of 0.3%. The core PPI, which excludes food and energy, rose by 0.3%, aligning with estimates.
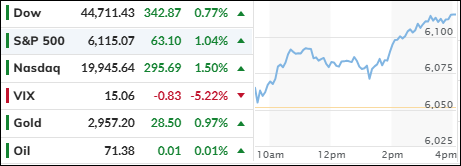
Despite these increases, traders pushed equities higher, reasoning that these latest figures suggest a softer Personal Consumption Expenditures (PCE) price index than feared. The PCE, closely monitored by the Federal Reserve, is set to be updated tomorrow.
Global trade tensions remain a focal point as Trump announced reciprocal tariffs on imported goods from any country that imposes duties on U.S. imports. With India being a significant offender, this will make for an interesting meeting when Trump meets with India’s Prime Minister Modi.
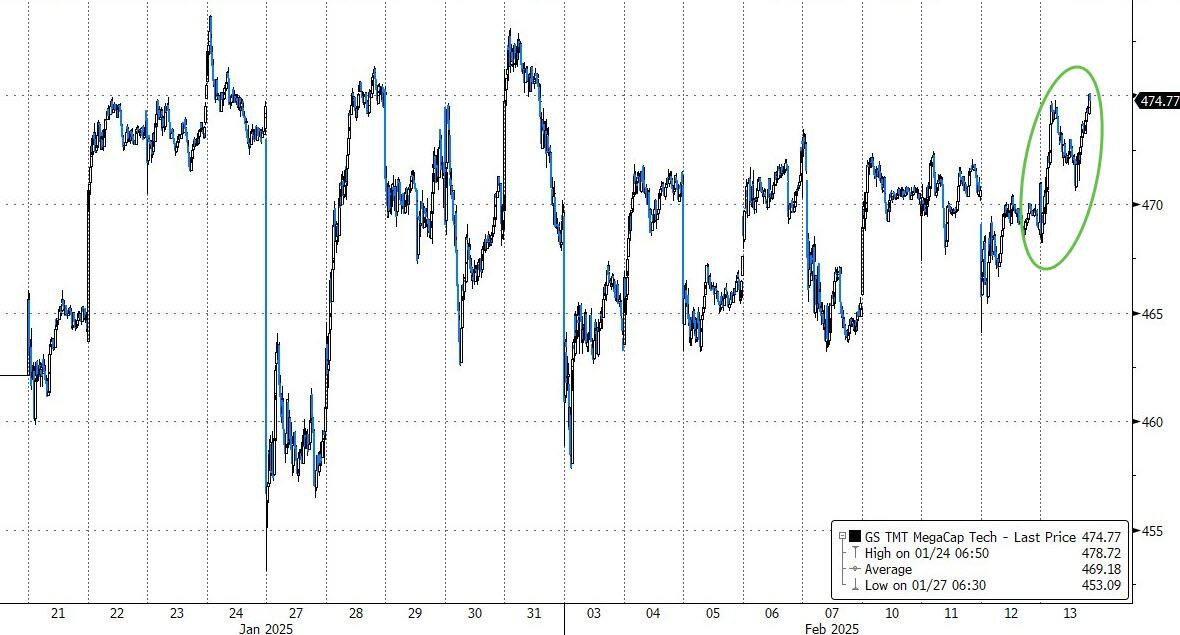
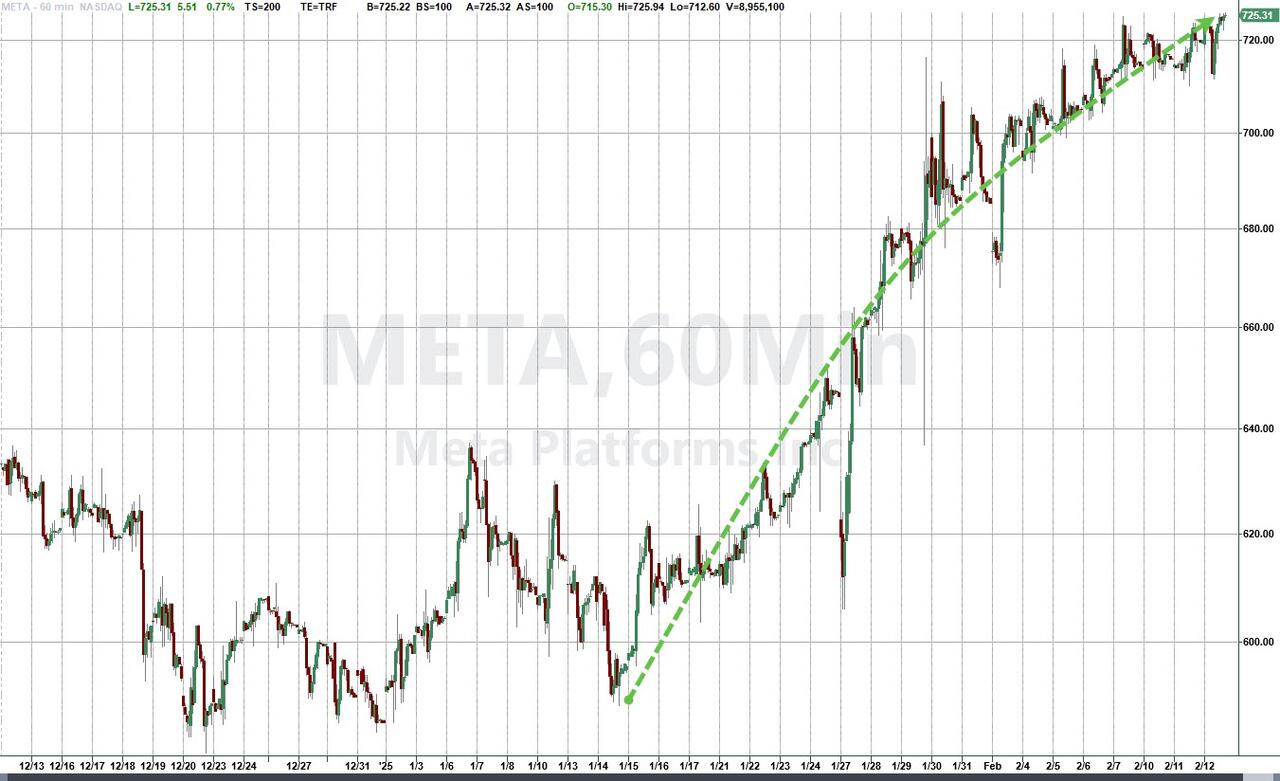
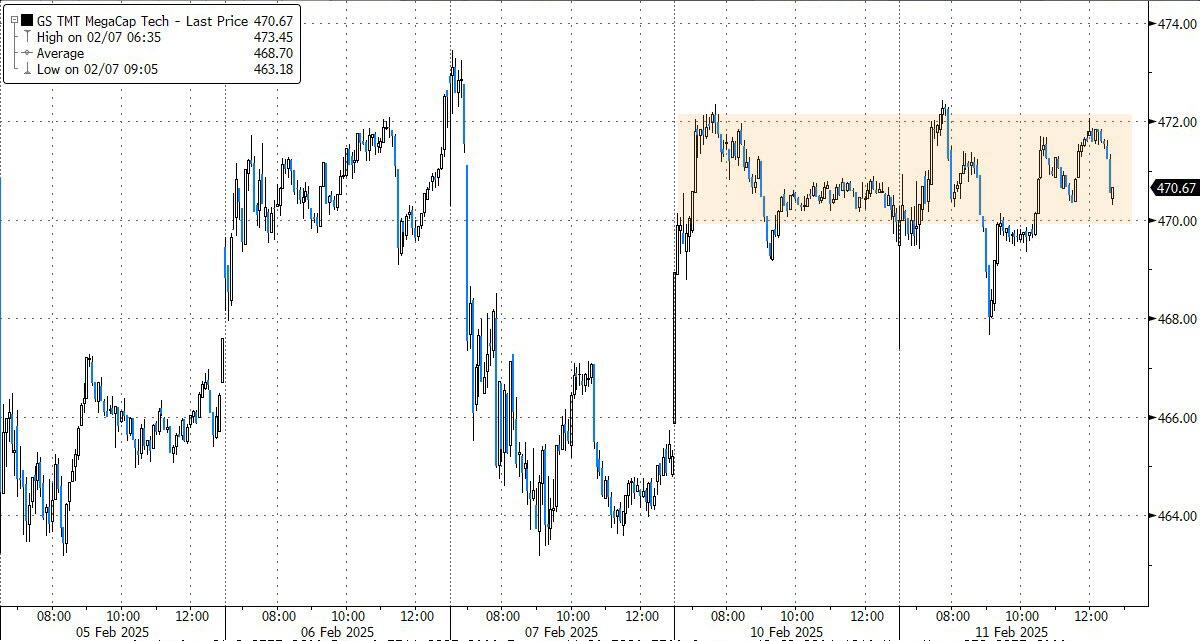
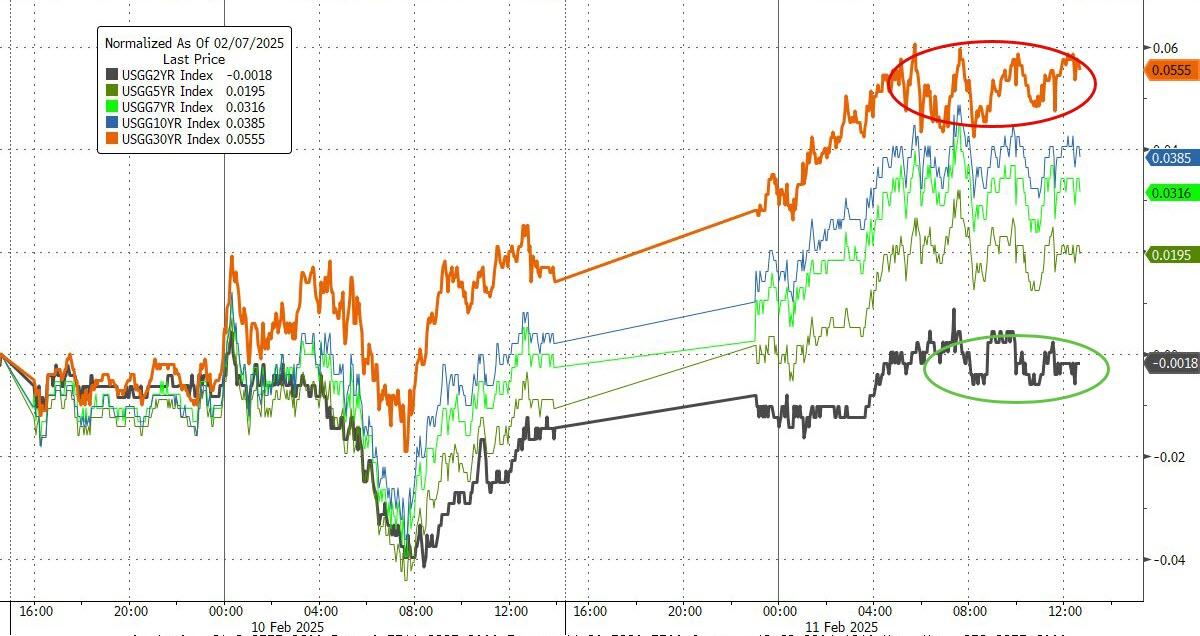
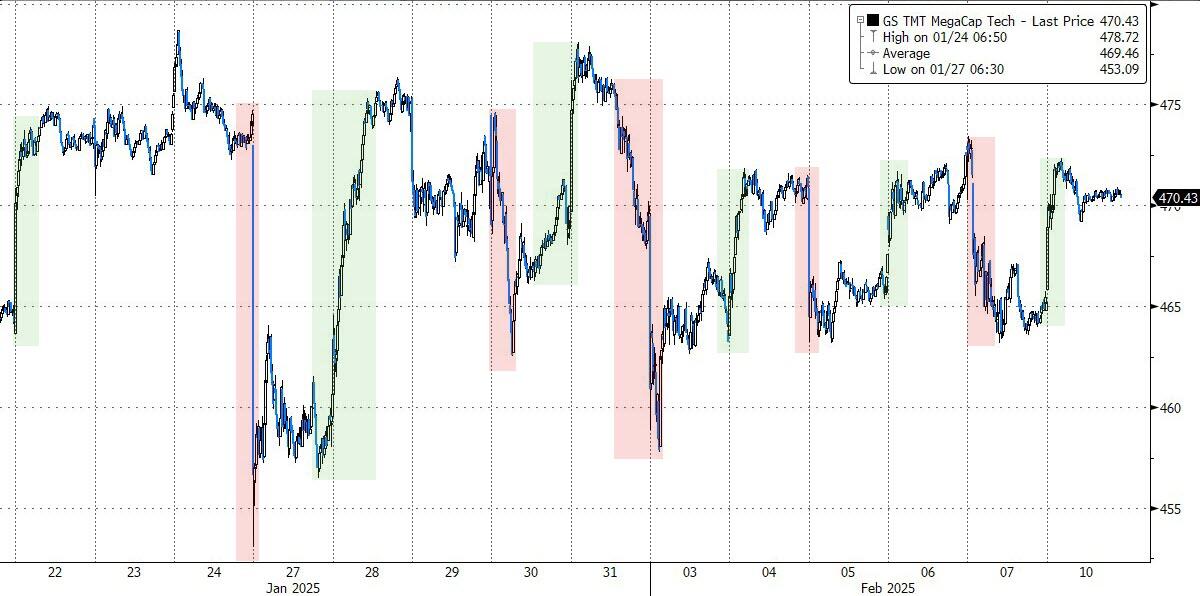
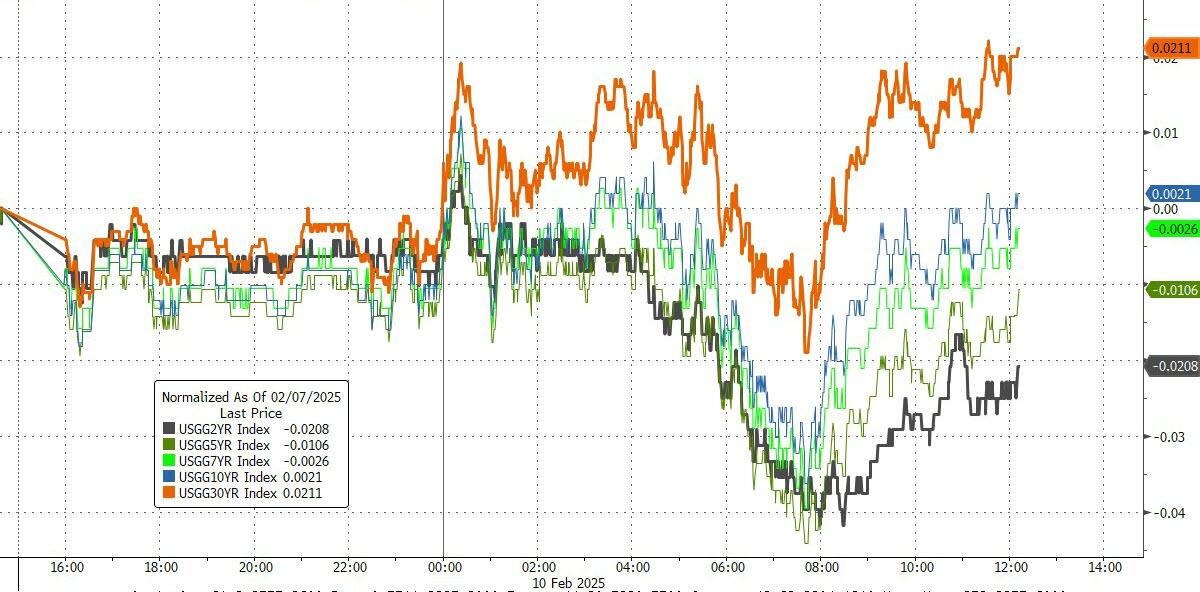
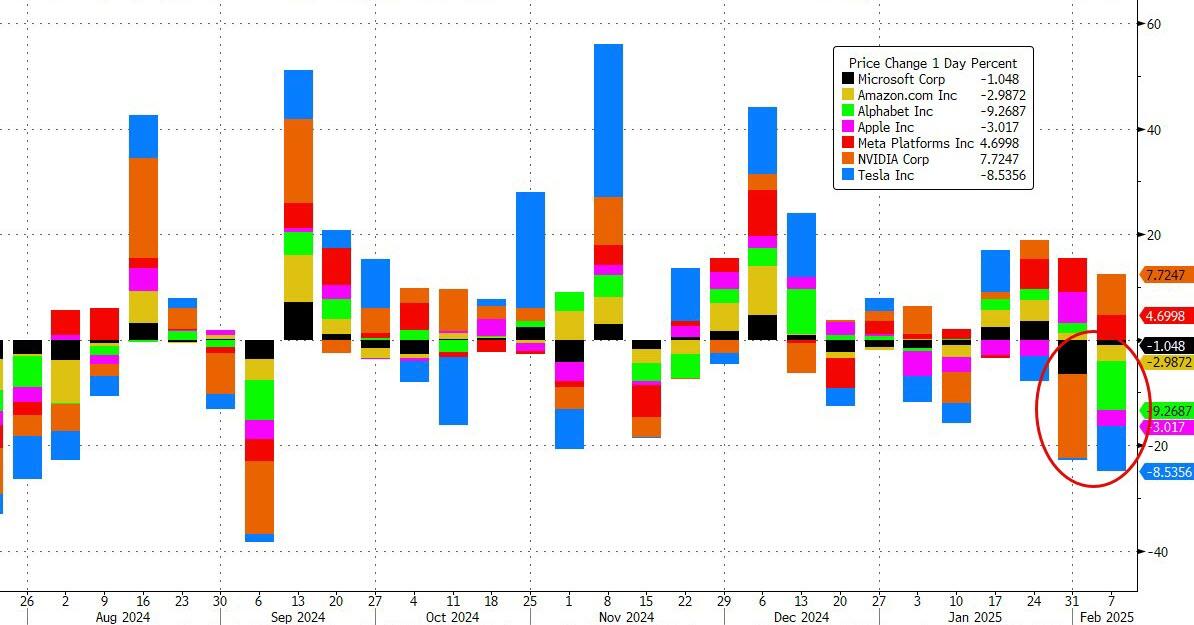
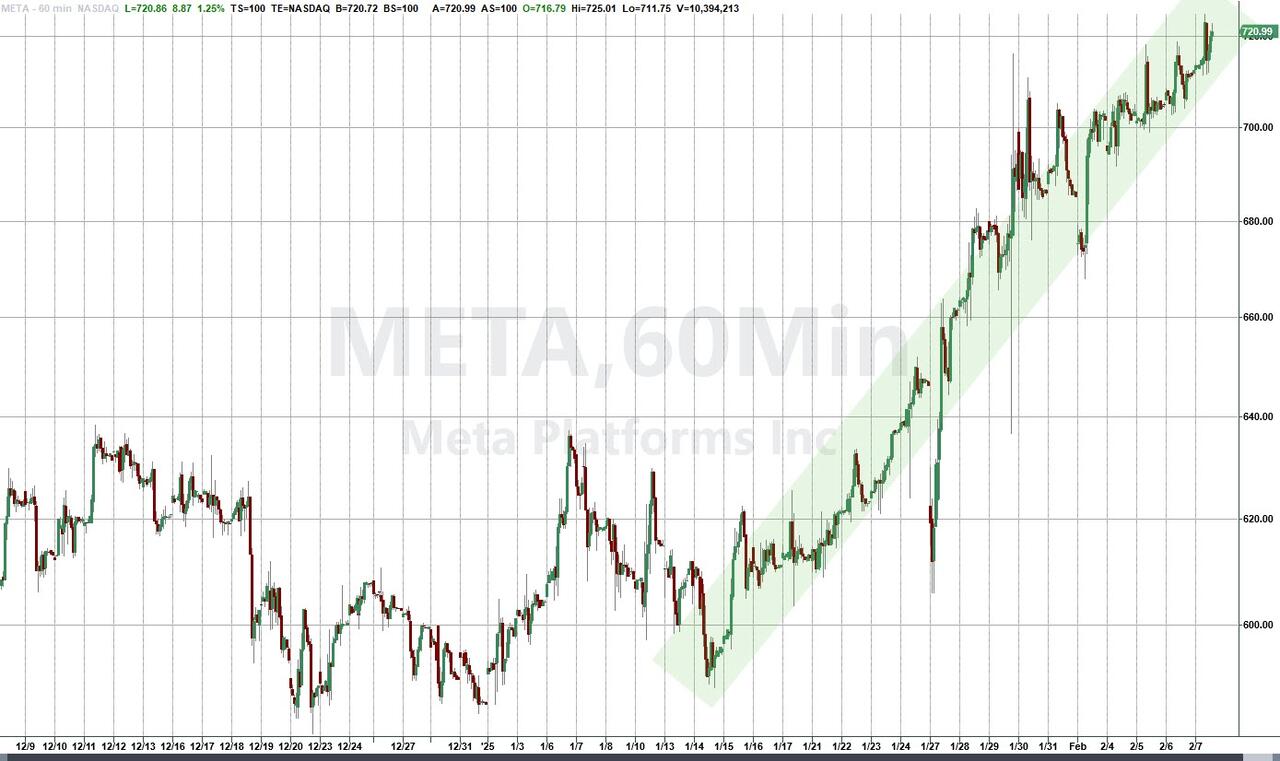
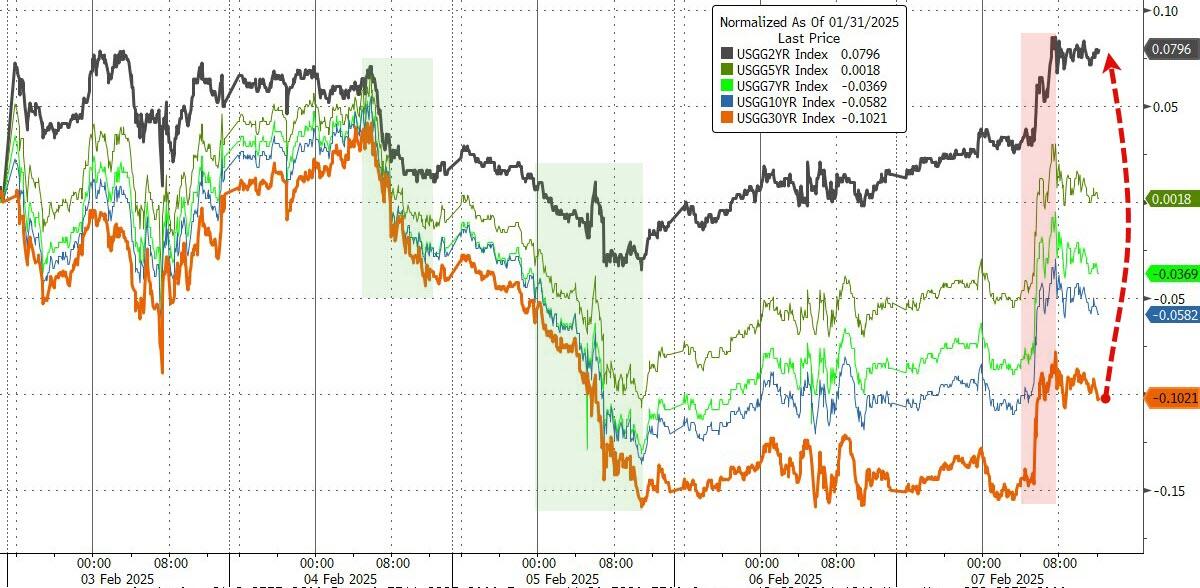
In the end, bond yields tumbled, helping equities to rally, with the Mega-cap sector participating. However, U.S. Defense stocks declined following Trump’s comments about halving the defense budget.
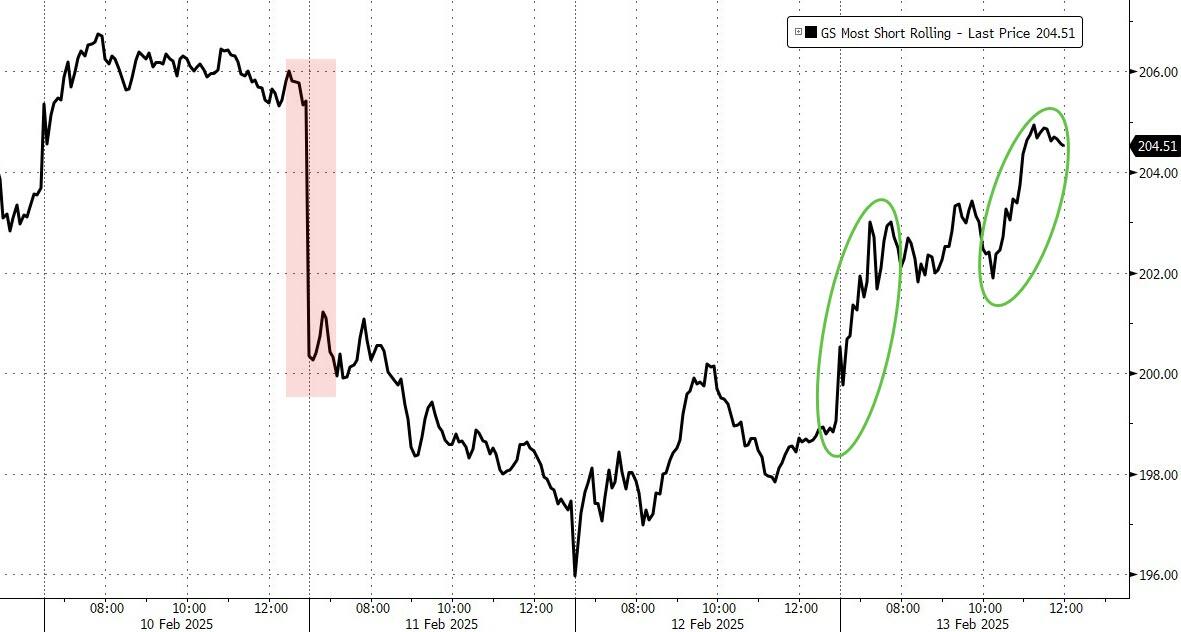
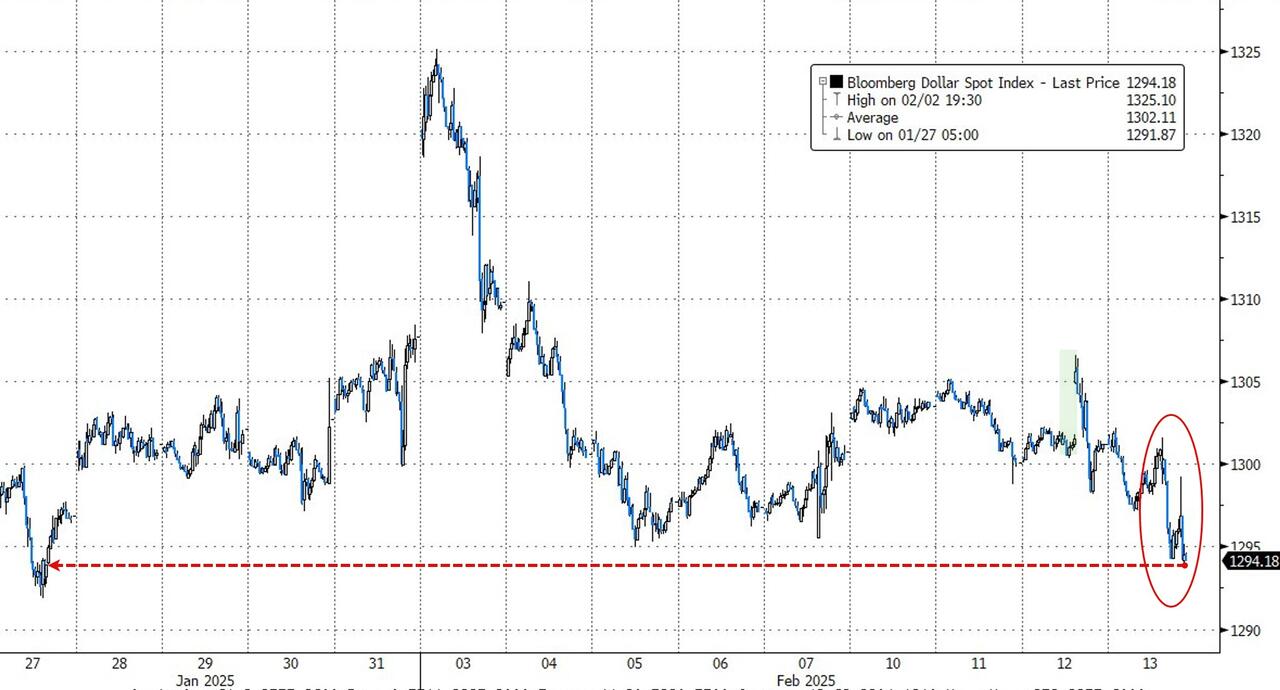
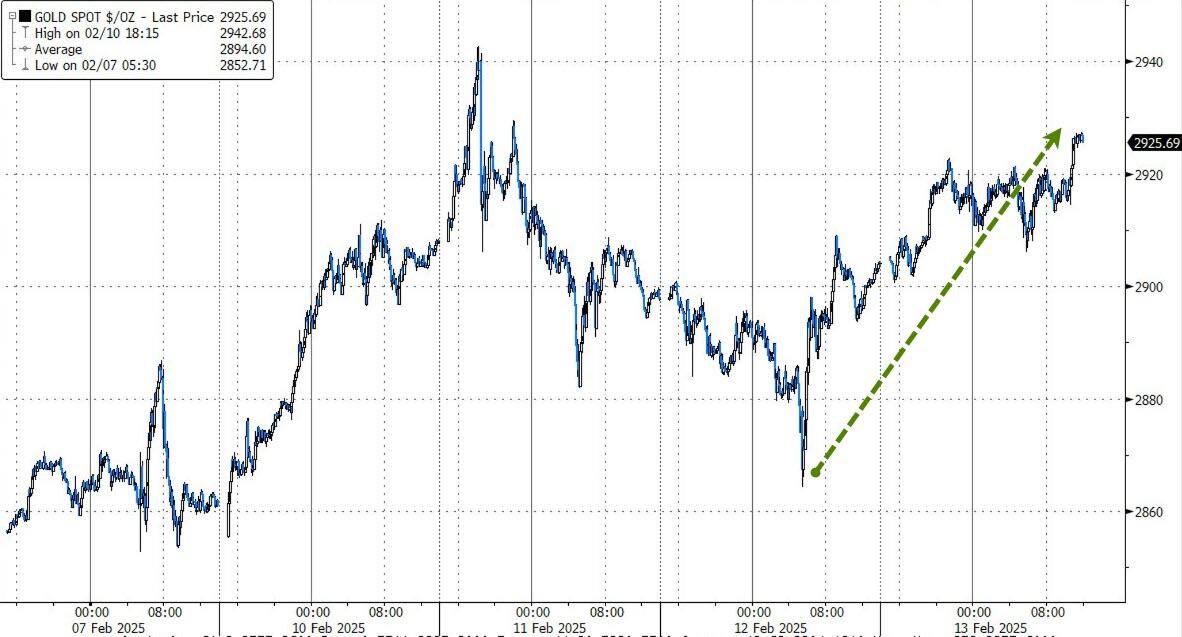
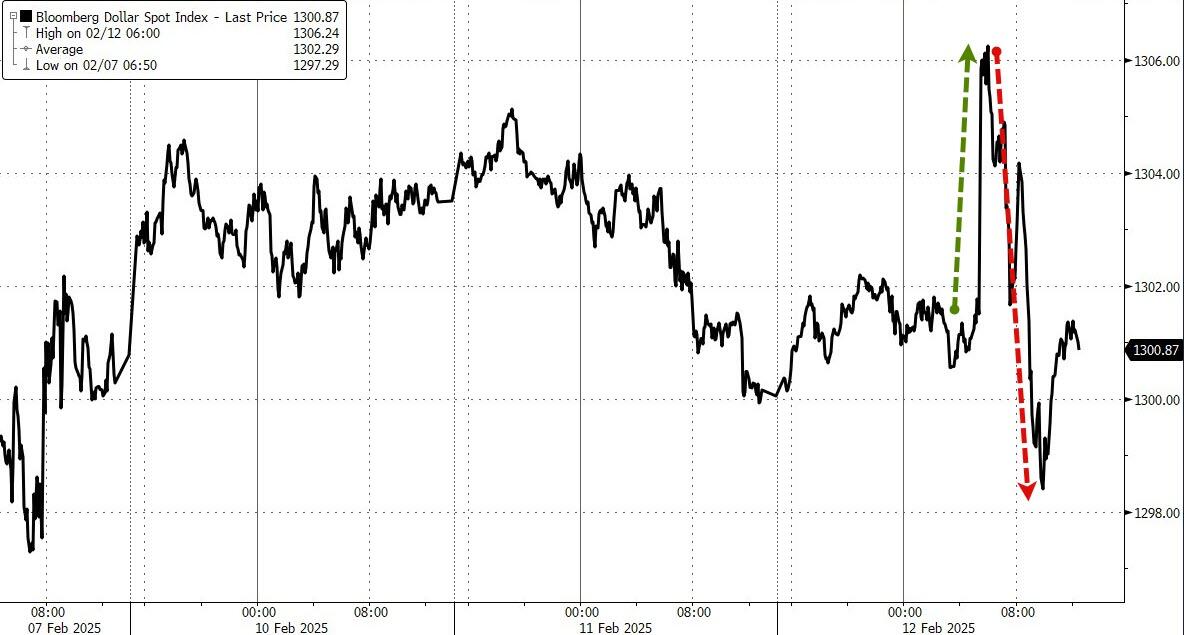
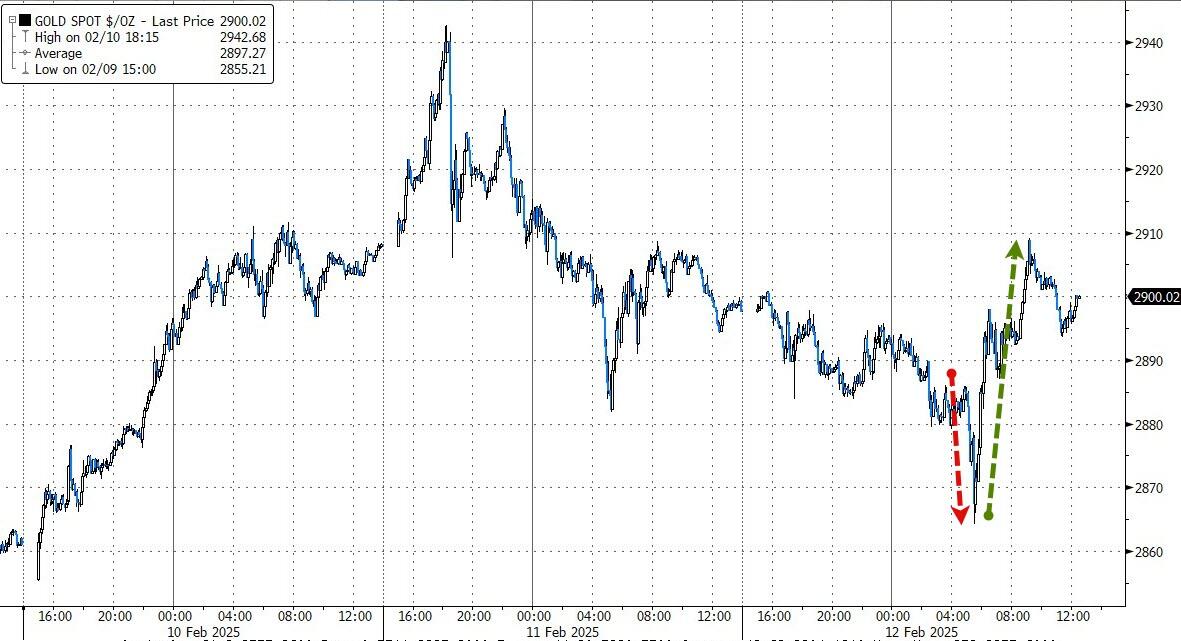
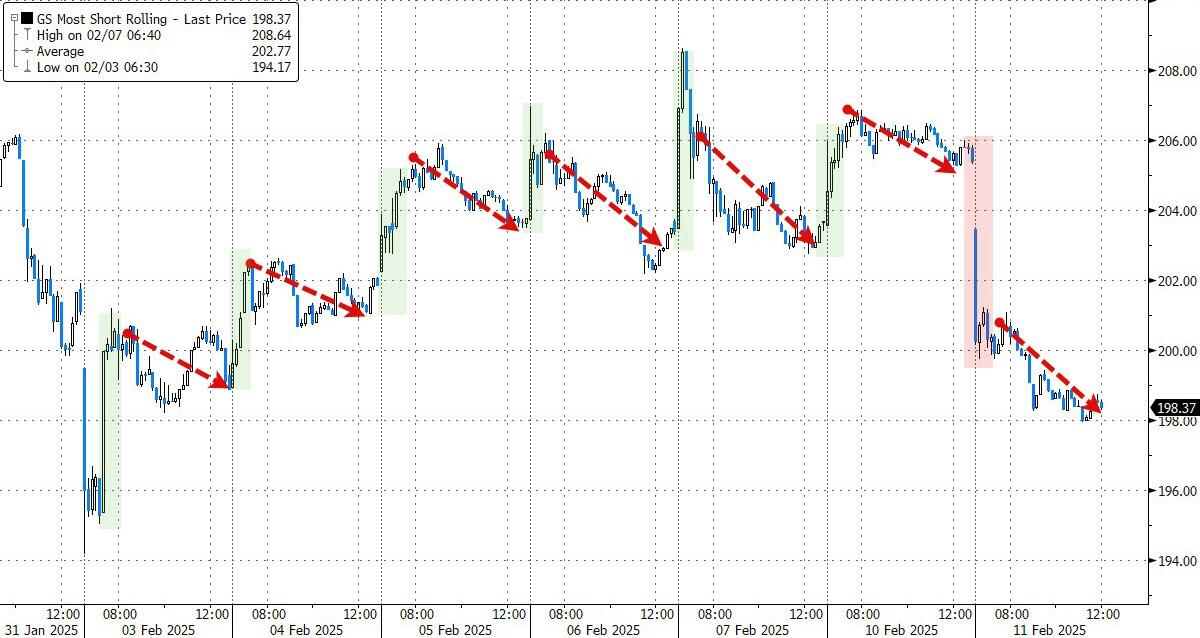
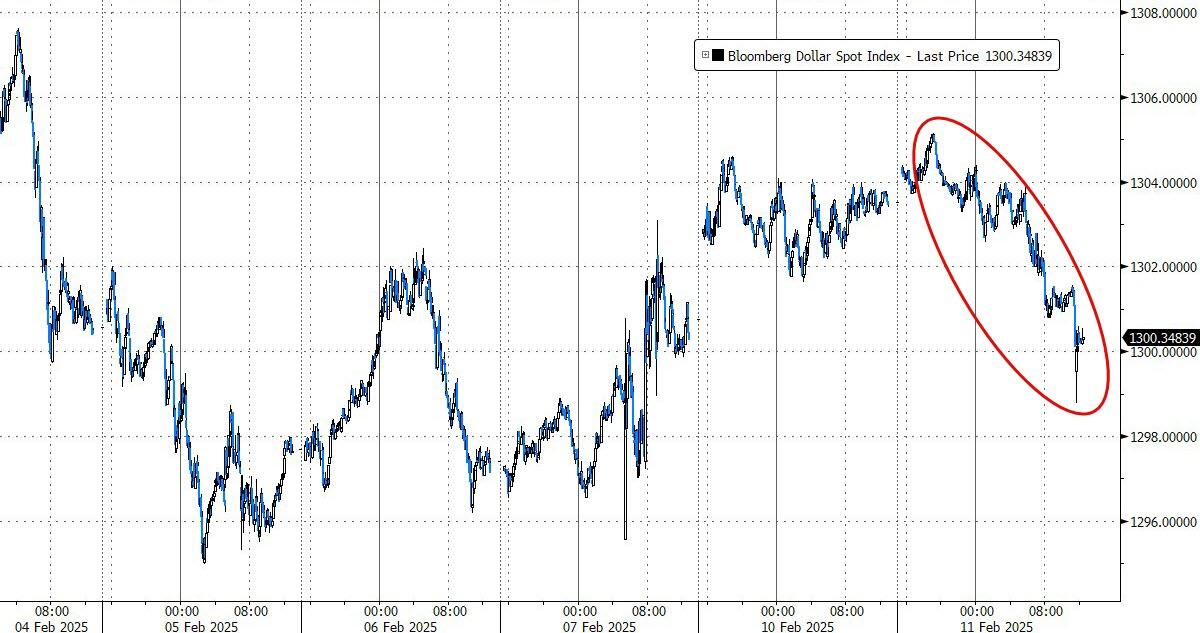
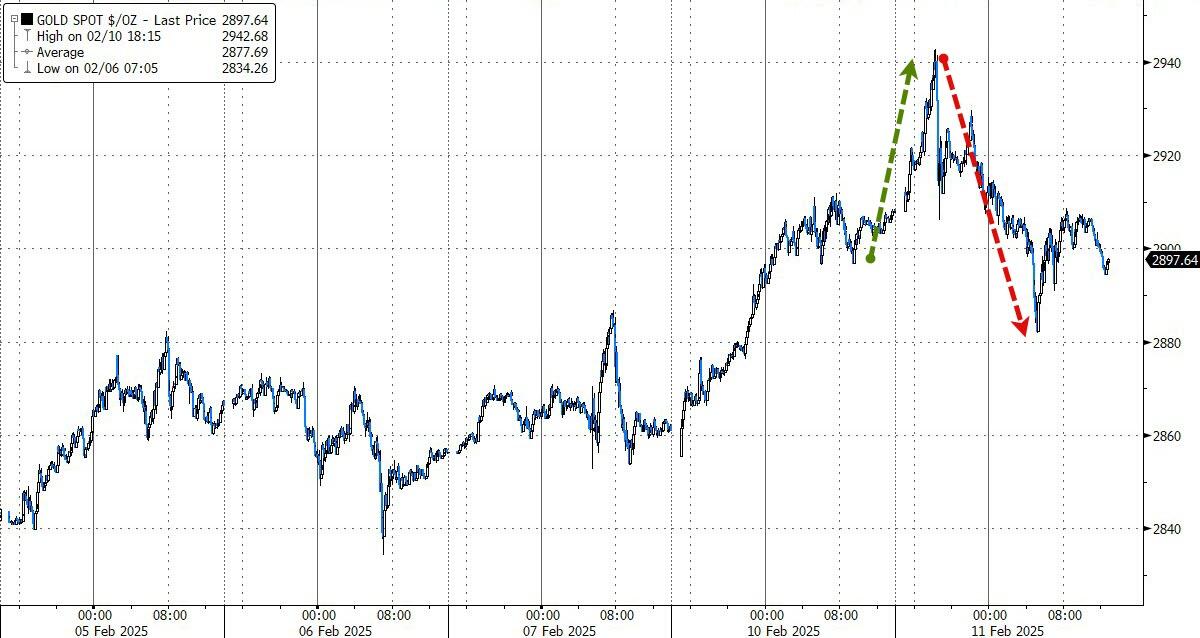
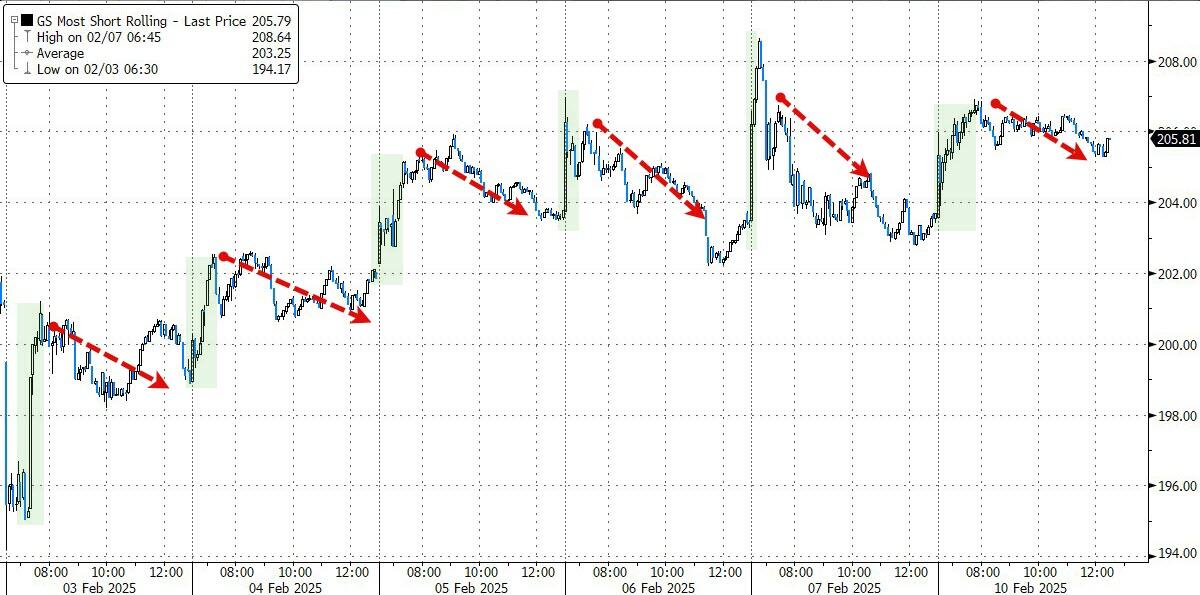
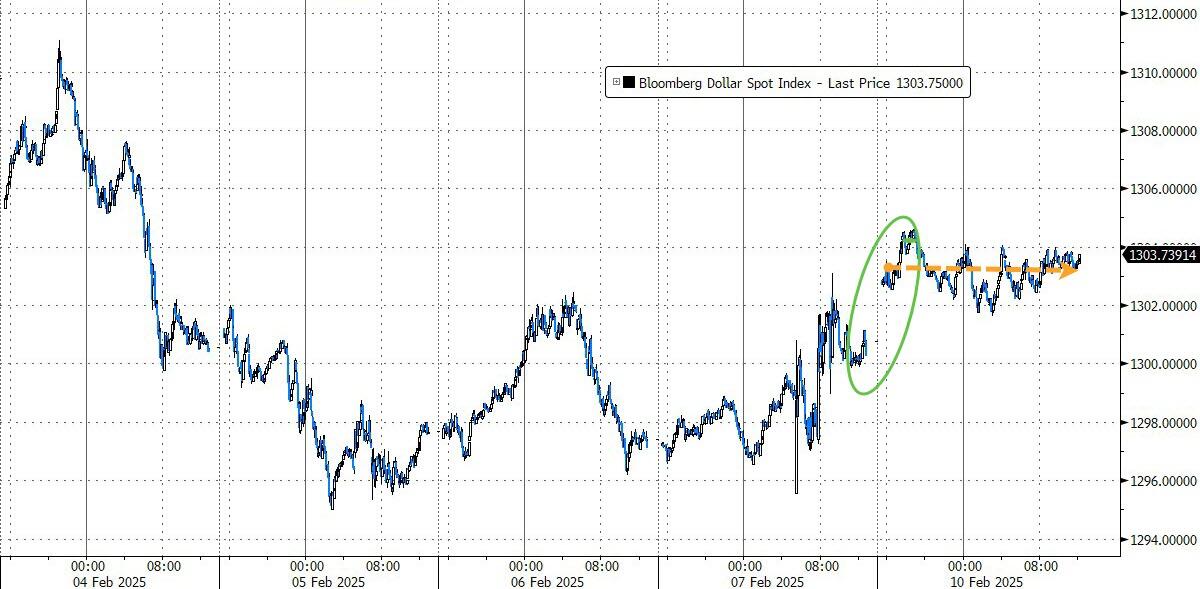
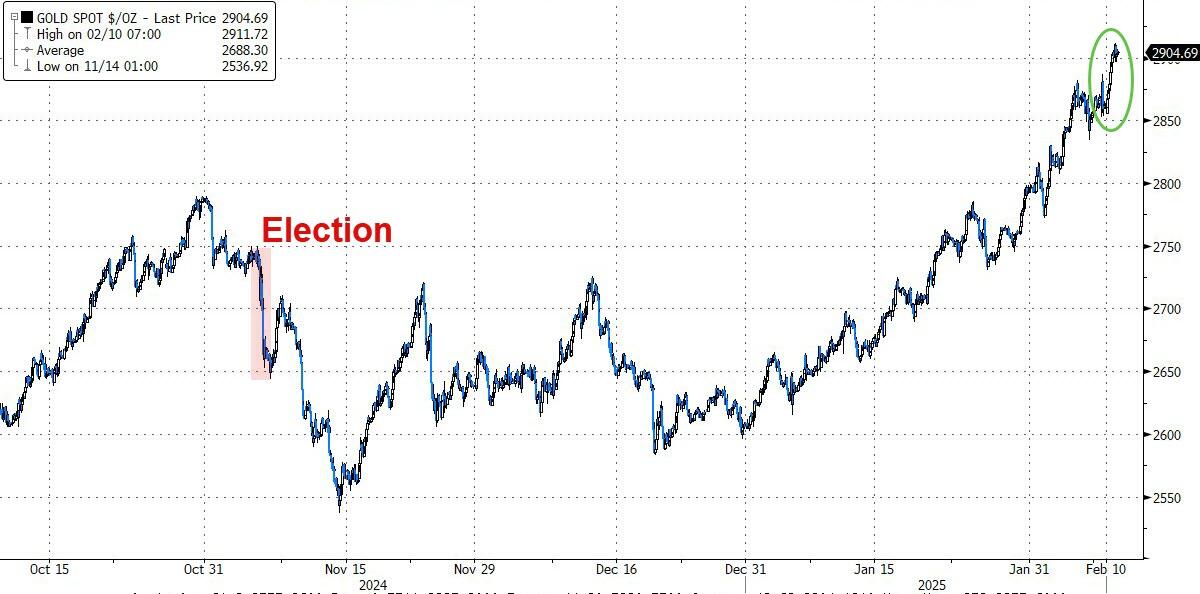
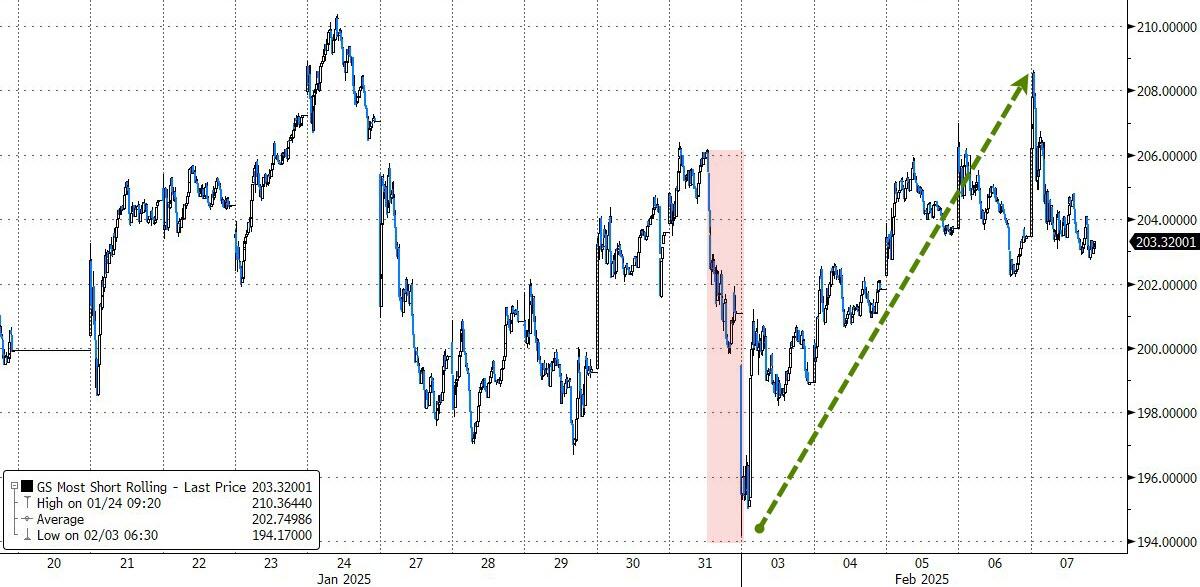
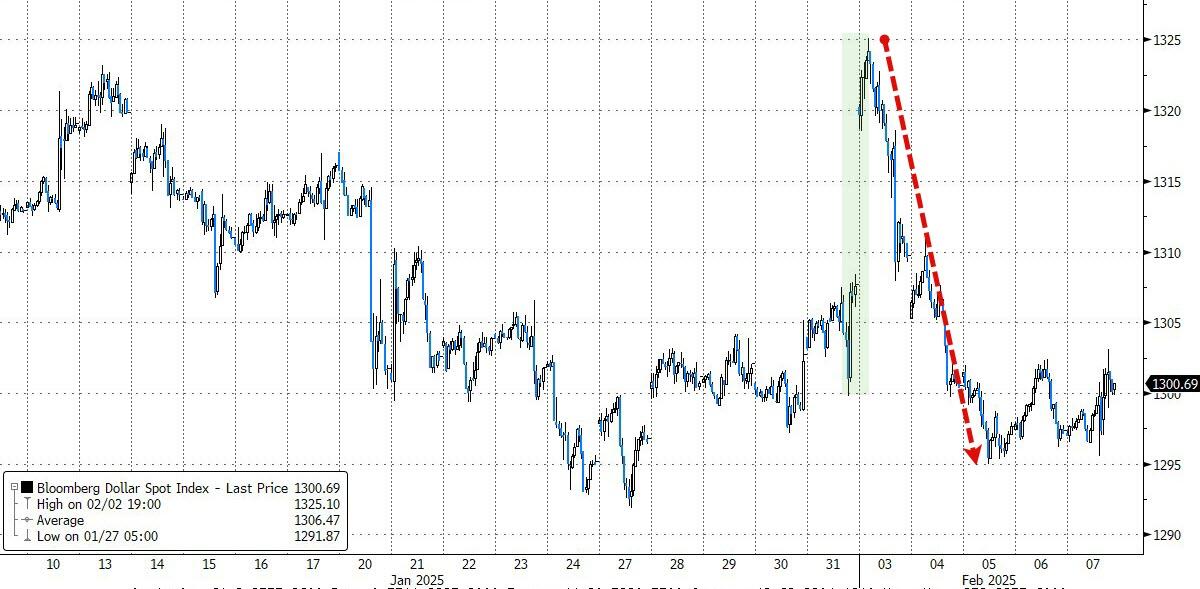
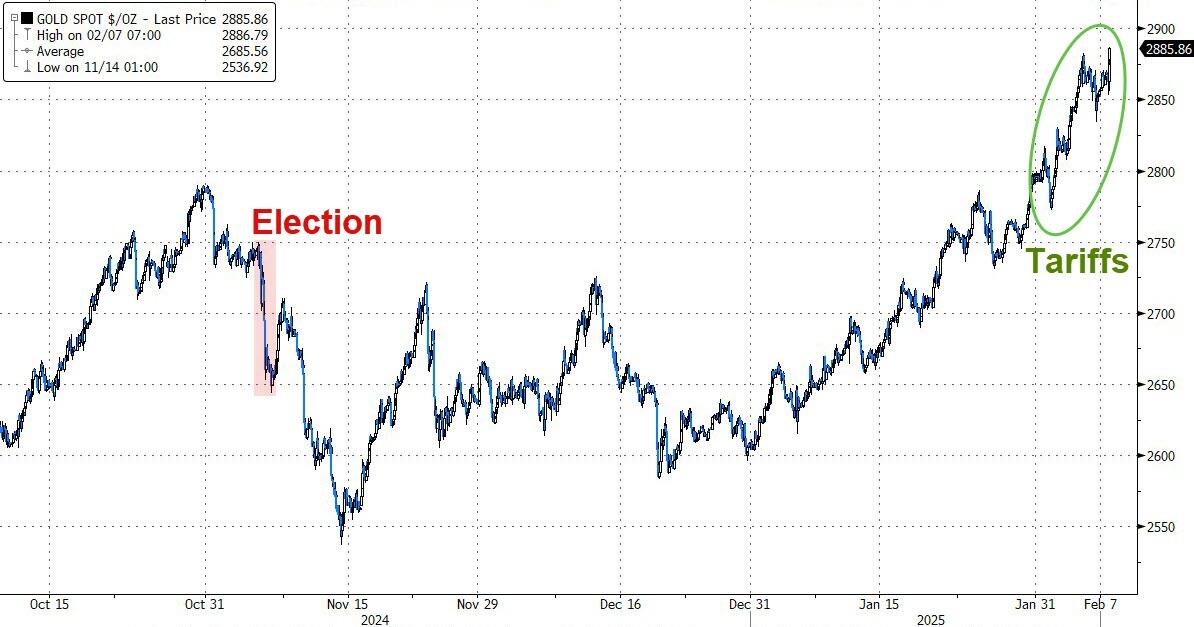
The most shorted stocks rallied, supporting bullish sentiment, alongside the semiconductor sector. The dollar closed at a three-week low, which helped gold to bounce back.
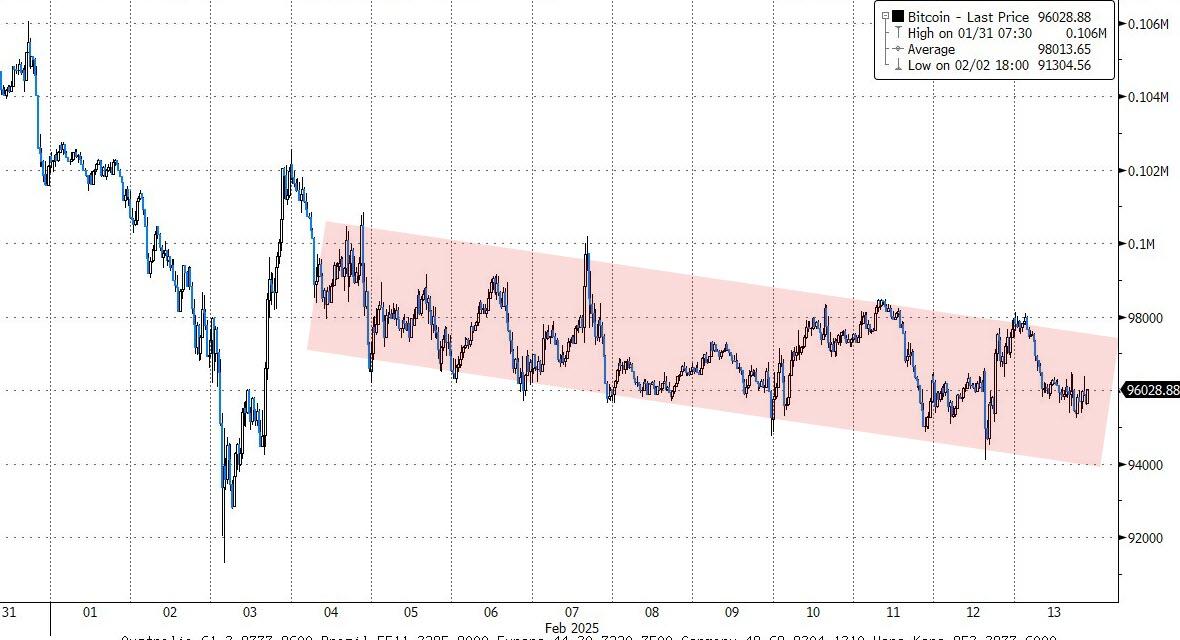
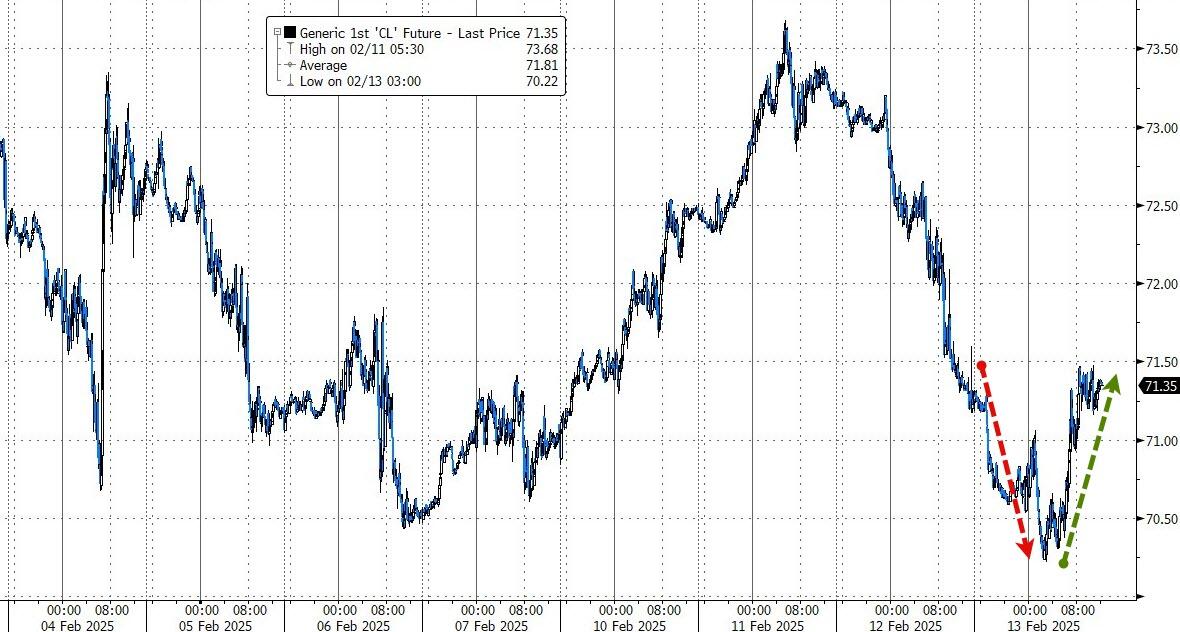
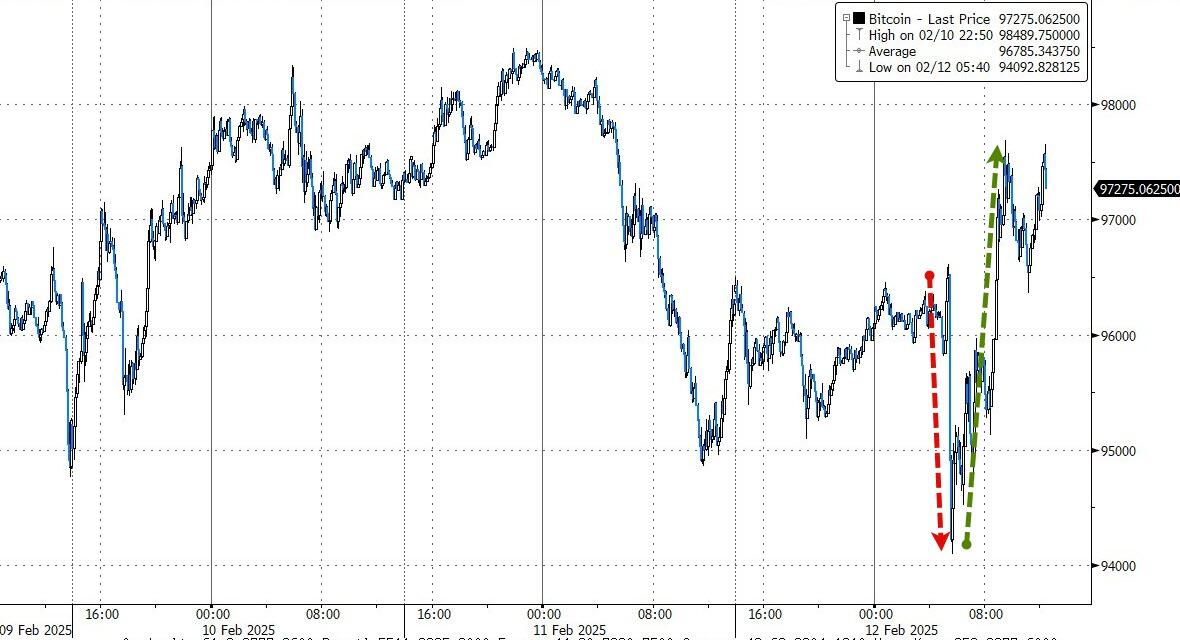
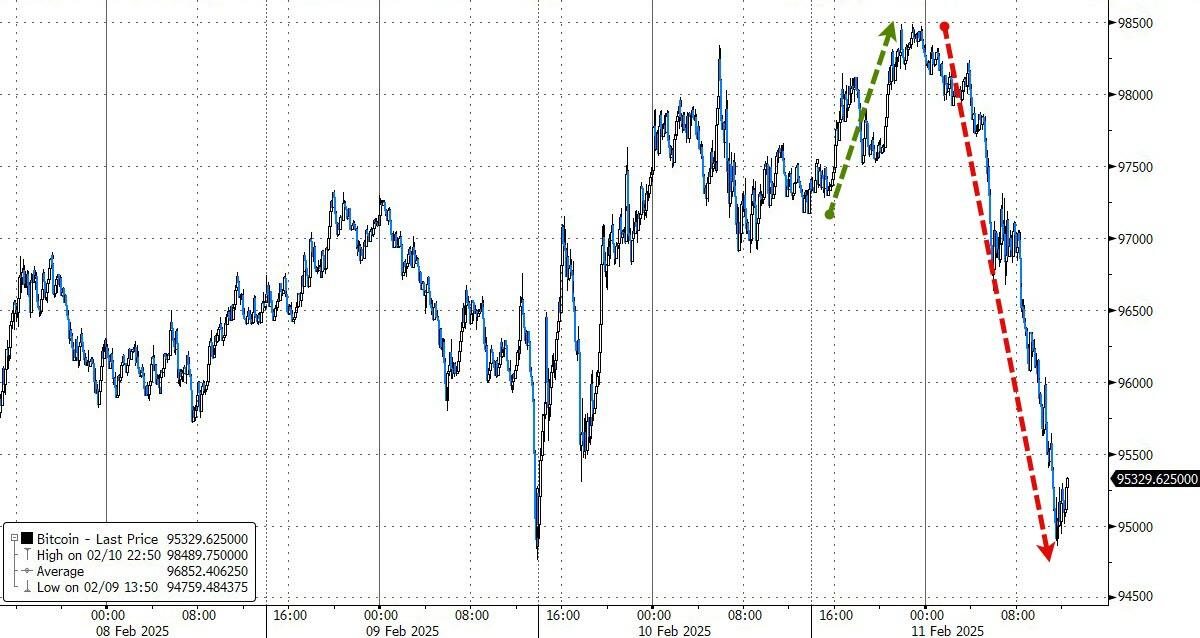
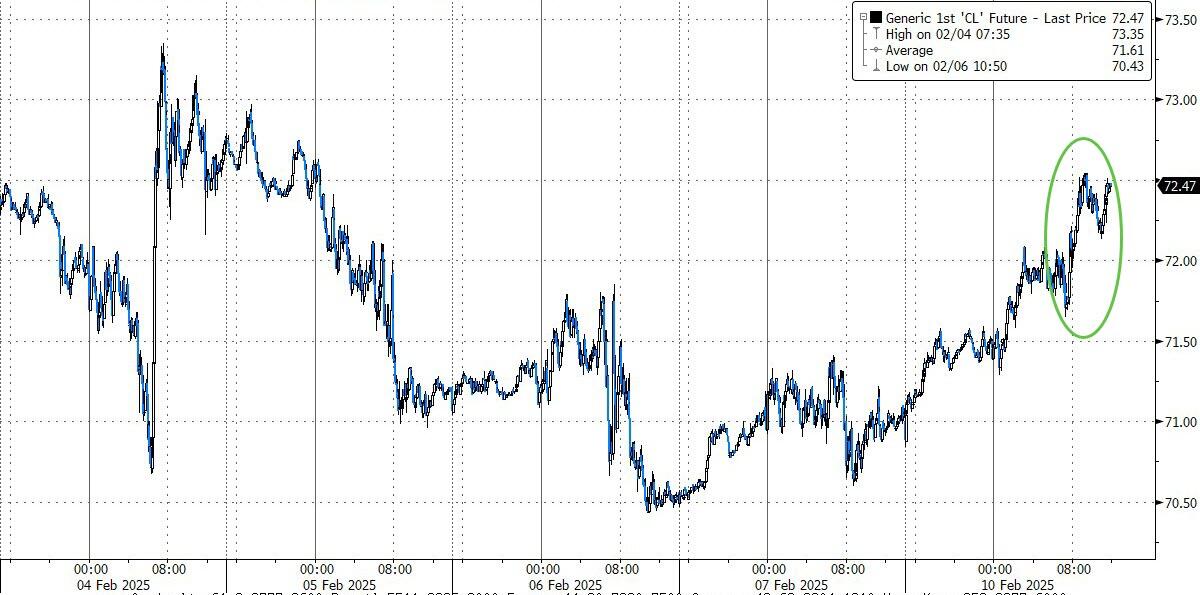
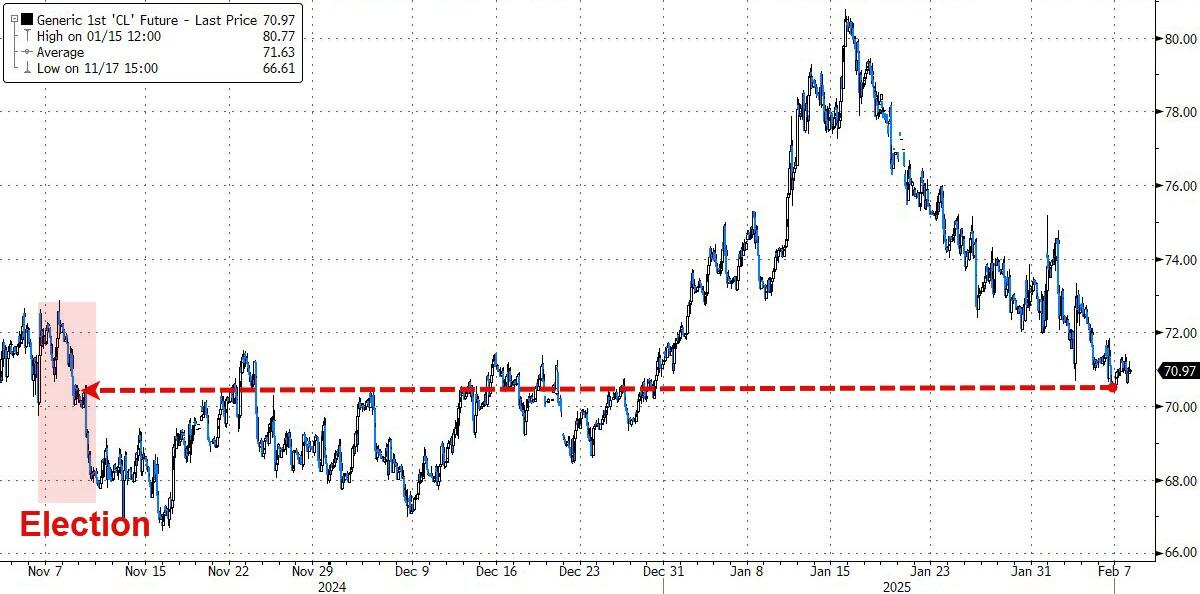
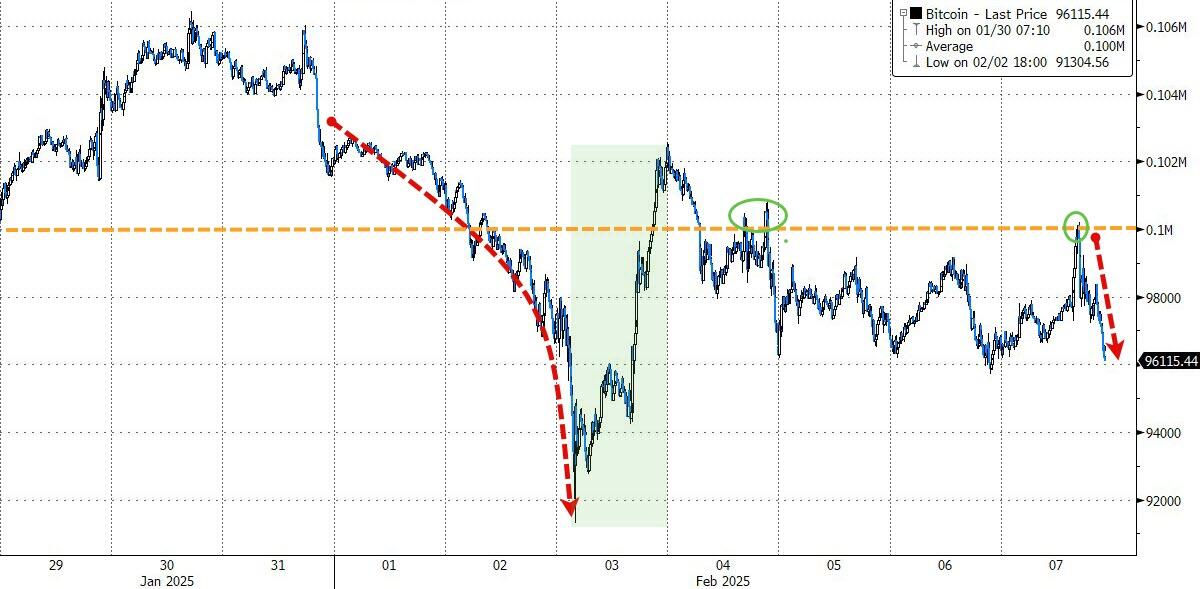
Bitcoin slid but found support at $96,000, while crude oil experienced volatility but closed relatively unchanged.
After a choppy week, traders are eagerly anticipating tomorrow’s PCE release, which is expected to come in better than anticipated, potentially pushing bond yields lower and equity prices higher.
Will they be right?
Read More