1. Moving the Markets
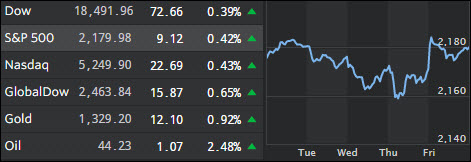
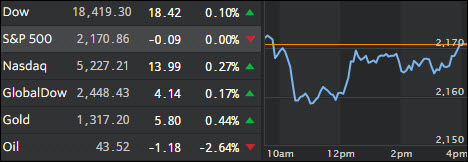
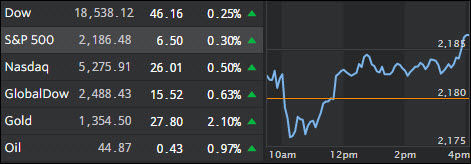
Stocks remained in positive territory today, even after the weakest reading on the services sector of the economy in six years, as traders returned from the long holiday weekend. It seems that Wall Street is still digesting Friday’s August jobs report (which most investors say will keep the Federal Reserve from hiking interest rates later this month), however, it bared no exuberant motions in trading today. Given the horrific economic data points as of late which, in a normal market would have pushed the major indexes south, it’s become clear that the Fed is politically motivated to support the encumbent party by keeping the markets as elevated for as long as possible.
More and more investors are somewhat on edge amid a stock market that continues to hover near all-time highs but is trading at way above-average valuations. All three major U.S. stock indexes kicked off the week within 1% of their all-time highs hit in mid-August and there is no apparent “market moving” indication that the situation will change anytime soon. That is until a black swan event reverals the magnitude of the air pocket below.
In deal news today, we heard that Volkswagen intends to take a $256 million, or 16.6%, stake in Navistar International (NAV) in an effort to get exposure in the U.S. heavy-truck market. Navistar’s shares jumped more than 50%, while VW stock was off by about 8%. The deal includes technology sharing and joint purchasing and related cost savings, the companies said Tuesday. In addition, Bayer AG upped its offer for Monsanto for a second time to $127.50 per share, which would price any deal at close to $56 billion.
 By Wolf Richter,