[Chart courtesy of MarketWatch.com]
- Moving the market
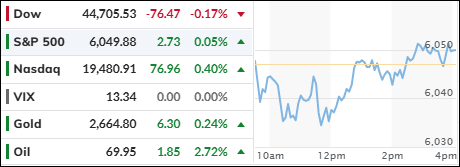
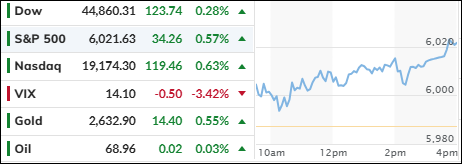
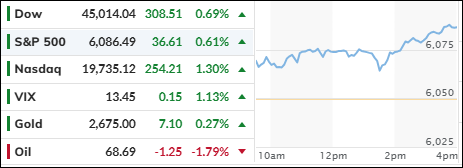
Equities began the session on a bullish note, with the S&P 500 and Nasdaq reaching new record highs.
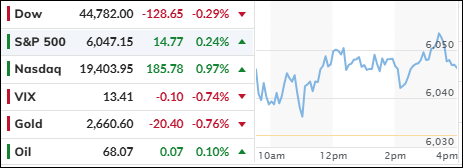
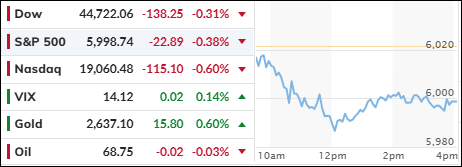
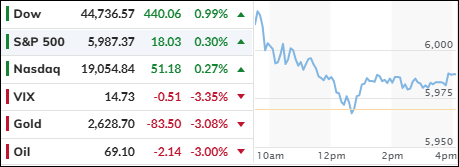
Following yesterday’s mixed performance, the major indexes appeared to shift back into bullish mode. However, it remains uncertain whether we will see a repeat of the post-election surge.
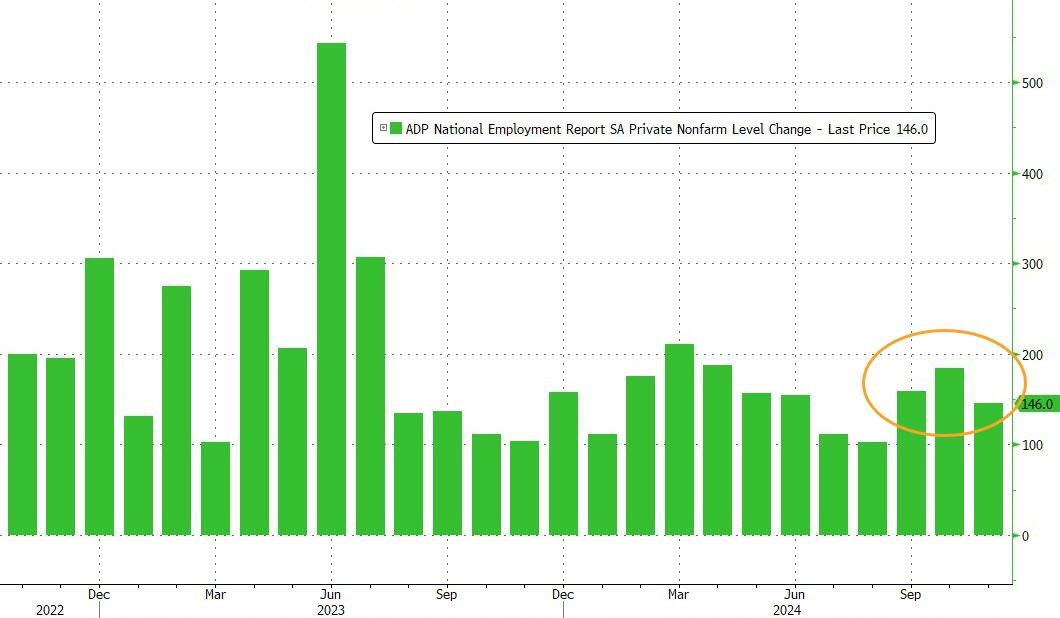
Private payrolls, as reported by ADP, grew less than expected in November, with only 146,000 positions added compared to the anticipated 163,000. Additionally, the October surge of 233,000 jobs was revised down to 184,000. This will be followed by Friday’s November labor report, which could significantly impact the market.
Traders are also focused on Fed Chair Powell’s speech in New York this afternoon, which will be a moderated discussion.
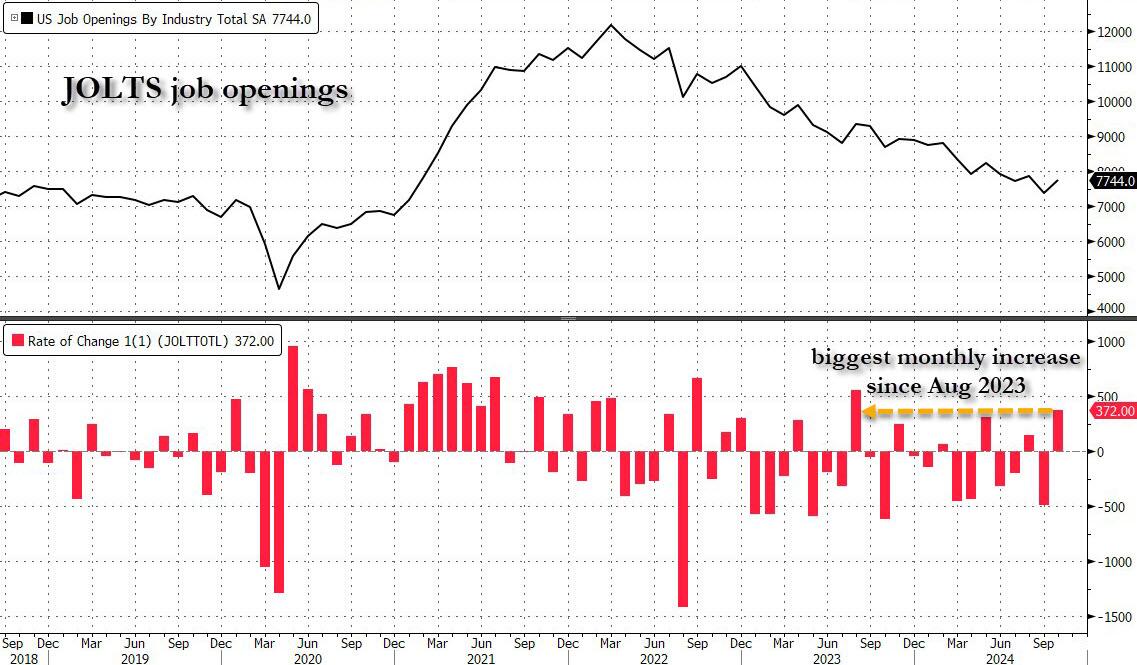
The Fed’s Beige Book was released, indicating that the sluggish, flat, and declining conditions observed in September and November had reversed. This, combined with a strong jobs report on Friday, could be enough for the Fed to pause rate cuts for the foreseeable future.
This news propelled the markets into overdrive, with the major indexes achieving solid gains after some mid-day sideways movement. The Nasdaq led the charge, while Small Caps lagged.
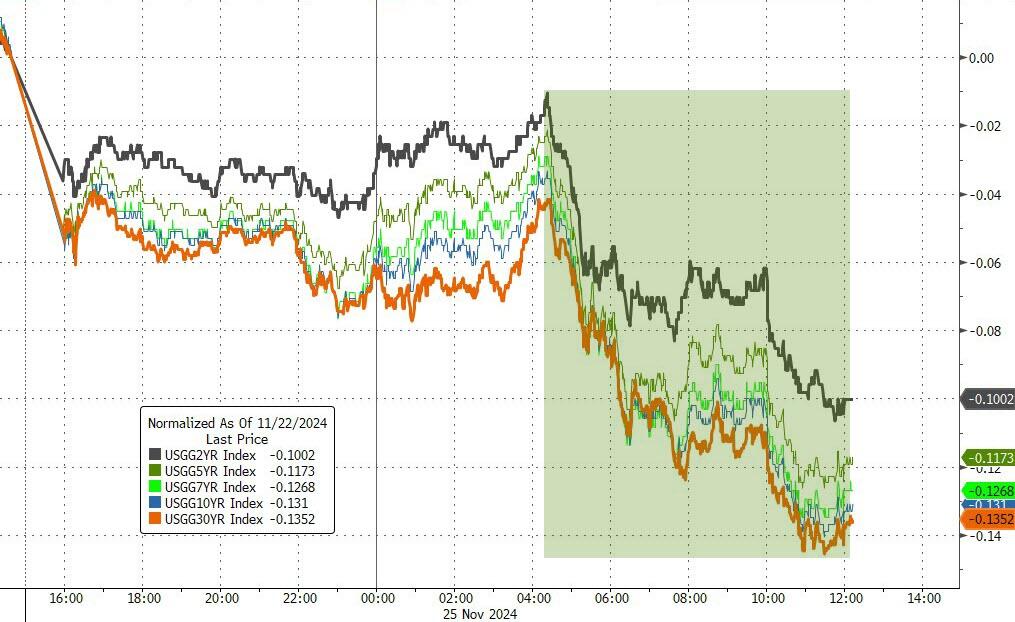
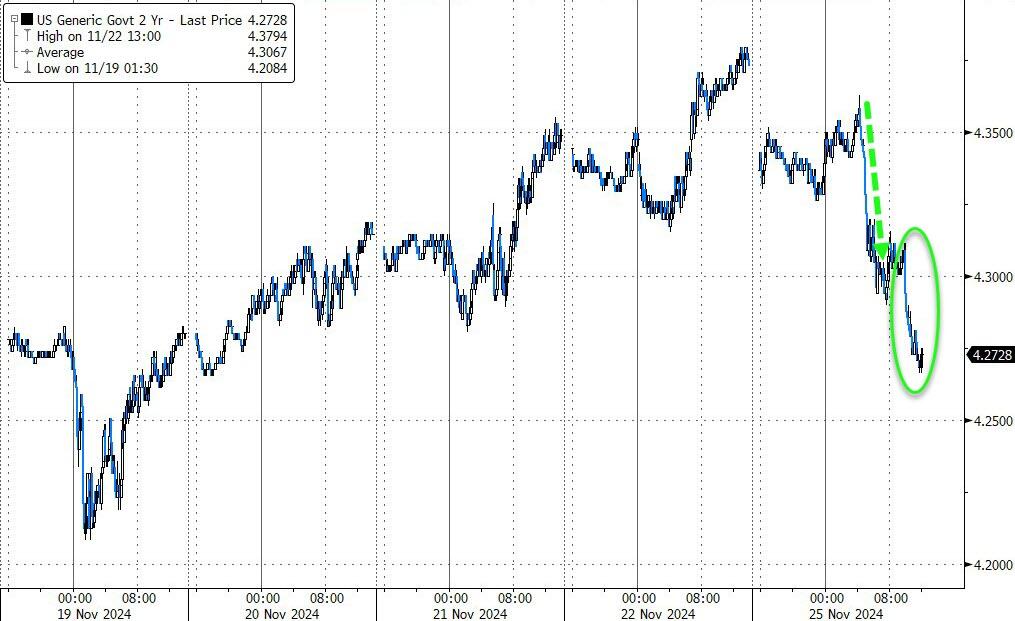
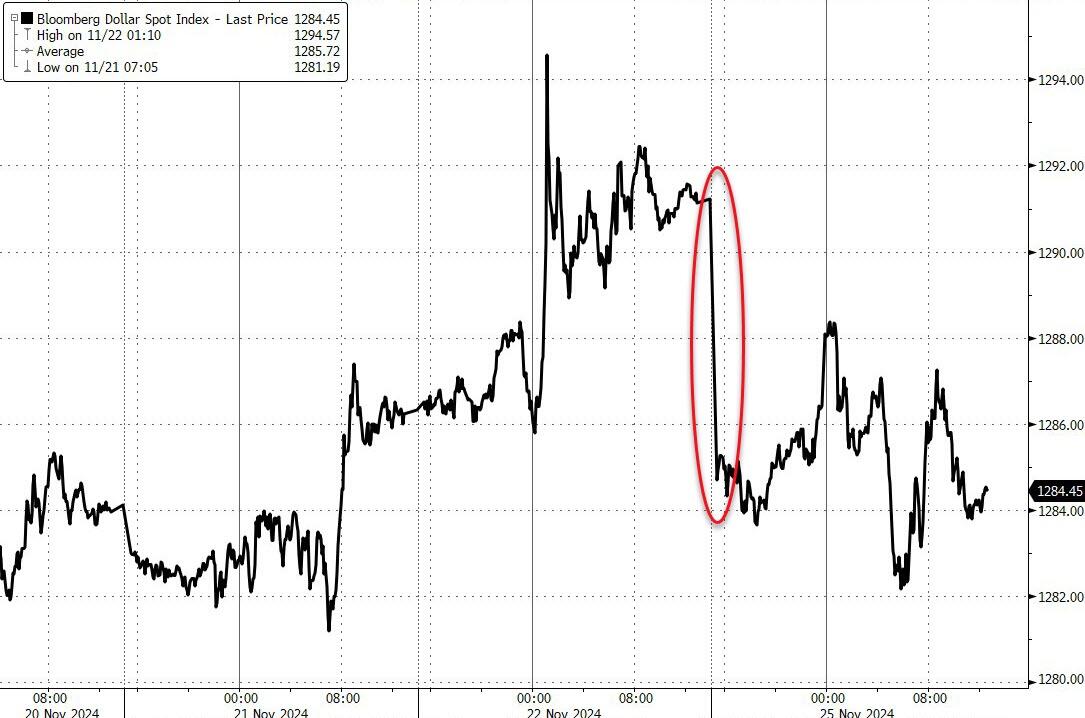
The Mega-Cap tech basket surged to a new record high as bond yields retreated. The dollar came off its highs for the day and ended unchanged, while gold swung wildly but closed at the upper end of its recent trading range.
Bitcoin benefited from the nomination of a pro-digital asset SEC head and the fall of the French government, rising slightly above the $99,000 level.
Currently, there is a tug-of-war between investors who believe in the Santa Claus rally and those who remain skeptical after November’s stellar performance.
Read More